Pycnogenol for menopause
All In Nutritionals
Subscribe to IHR Magazine
Home Blog

The One-Hour Accept Rule Behind IHR Plugin’s Store Network

0
Shipping box on a health store counter labelled accept in 1 hour, ship in 3 hours, beside a kitchen timer set to 60 minutes

Shipping box on a health store counter labelled accept in 1 hour, ship in 3 hours, beside a kitchen timer set to 60 minutes

An order from IHR Plugin’s network will reach your store with a clock already running. The platform promises shoppers that a store will accept each order within one hour and ship it within three, and the person who keeps that promise is whoever happens to be behind your counter when the alert arrives.

IHR Plugin links the websites of independent health stores so that an online order is filled from the nearest shelf holding the product. It is now scheduled to go live in spring 2027, later than the September 2026 date given in earlier reports, and it has published its prices and service terms for the first time. Most coverage so far, ours included, has described what the network lets a store sell. With the terms public, the more useful question for an owner is what the network asks a store to do when it ships for someone else, and whether the pay covers the work. On small orders it does not, and the stores most likely to earn from it are the ones with unusual stock and a second pair of hands.

Disclosure: IHR Plugin and IHR Magazine share ownership.

What the network pays a store to ship

When a shopper buys on one member’s site and another member’s shelf fills the order, the retail margin is divided 60/40 in favour of the store that ships. The platform’s worked example is a $100 sale with $55 going to the brand’s wholesale price and $5 to the platform fee on the free Starter plan, which leaves $40 of margin. The shipping store’s share of that is $24. The customer pays shipping at checkout, and Stripe settles every party’s share within about 48 hours, so a fulfilling store is never chasing another retailer for money.

Expressed as a share of the sale, the shipping store keeps about 24 cents of every retail dollar on a product with that margin structure. That ratio is the number to carry into the next calculation, because network orders will rarely be $100.

The smallest order worth packing
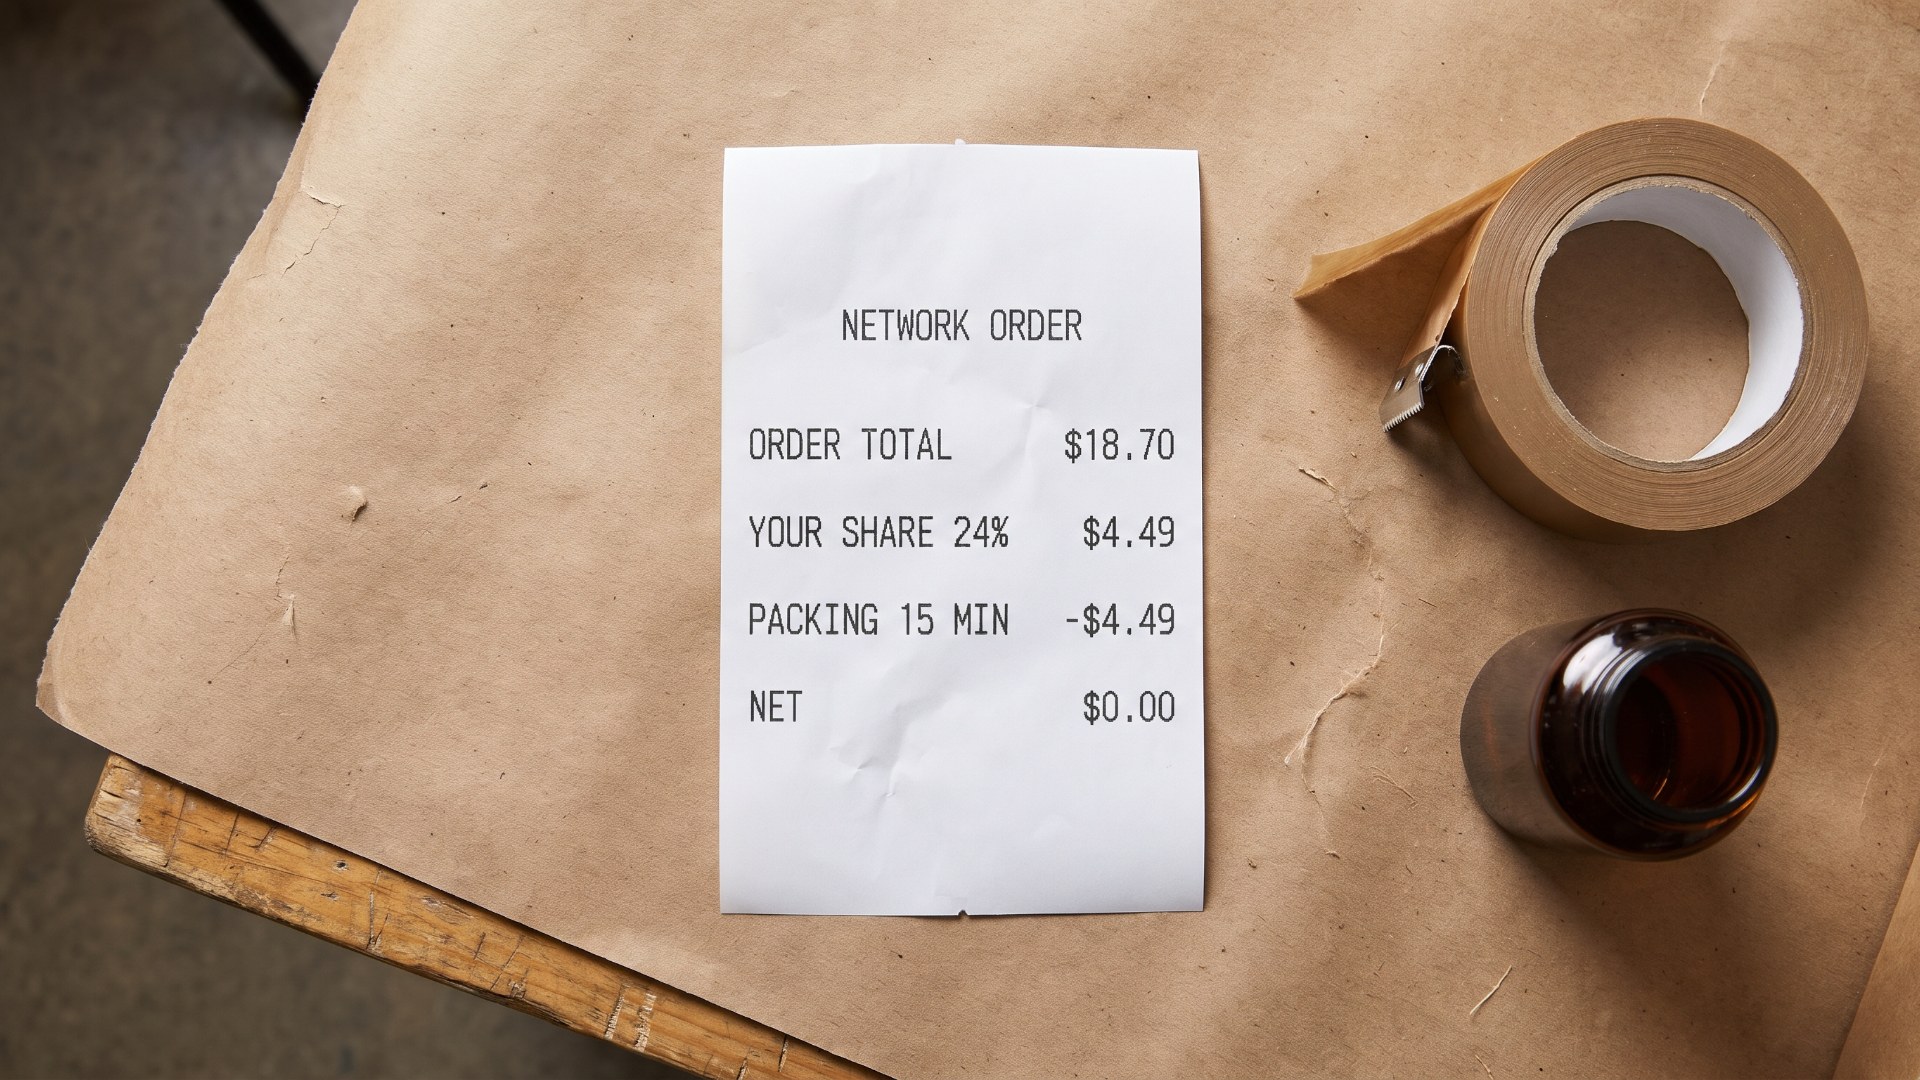
Packing slip reading network order total $18.70, your share 24 per cent $4.49, packing 15 minutes minus $4.49, net $0.00
Illustration: IHR Magazine.

A fulfilment order costs labour before it earns anything. Someone has to accept it, pull the unit, pack it, print the label and hand it to the carrier. At Ontario’s general minimum wage of $17.95 an hour, which took effect on October 1, fifteen minutes of that work costs $4.49 in wages alone. Divide by the 24-cent share and the break-even order comes out at about $18.70 in retail value. Below that, a store paying minimum wage loses money on every order it ships for the network, before the box and the void fill are counted.

The threshold rises as margins thin. If a product leaves 30 per cent of the retail price as margin after wholesale and the platform fee, the shipping store keeps 18 cents on the dollar and the same fifteen minutes needs an order of about $25 to break even. A single tin of tea or a small bottle of vitamin D sits under both lines. A month of protein powder or a practitioner-grade multivitamin clears them easily.

These figures are illustrative. They use the platform’s own margin example and a fifteen-minute handling time, and they leave out packaging materials, payroll costs above the base wage and any card fees the store already carries. Owners should time ten real orders from accept to label and use their own number.

Why unusual stock earns more orders than a big floor
A single distinctive bottle on a health store shelf of common supplements, with a sticky note reading only one in town
Illustration: IHR Magazine.

Routing follows a short published rule. The selling store’s own shelf is checked first, then the order goes to the store nearest the customer that has the product in stock, and stock is reserved at checkout so the last unit cannot sell twice. Only when no store can fill it does the order fall to the IHR distribution centre, a distributor or the manufacturer.

That rule rewards depth in the right places more than size. A best-selling magnesium or omega-3 will sit on many shelves in any city, so each order for it goes to whichever stocked store is closest to the shopper, and a member mostly ships those to its own neighbourhood. A line that no other member nearby carries behaves differently. Every network order for it in the region comes to the one store holding it, however far away the shopper lives. A specialist carrying a practitioner brand or a small regional label can expect more fulfilment orders from fewer products than a larger generalist with a familiar range.

The rule also exposes inventory accuracy. A unit reserved against a count that was wrong becomes an order the store accepted and cannot ship, with the shopper waiting on a service promise the store has already broken.

When shipping for the network does not pay

The one-hour window is easy for a store with two people on the floor and hard for one with a single clerk serving a lineup. The platform has not yet published what happens to an order a store fails to accept in time, and it has not explained the “priority fulfilment routing” listed on its US$399-a-month Professional plan. Until both are spelled out, a store on the free plan cannot know how often a contested order will reach it, or what a missed window costs.

For a single-staff store with mostly low-ticket online orders, that changes the advice. Connect during the free preview, list the catalogue, and treat fulfilment orders as occasional extra income that no budget depends on. A store with staff depth and lines its neighbours lack is in the opposite position, and it has the most to gain from being live on the first day.

Four things to measure before March 31

  1. How many minutes does it take us to accept, pick, pack and label one online order, timed over ten orders?
  2. In how many opening hours each week do we have two people on the floor?
  3. What is our average online order, and how much of it is margin after wholesale?
  4. Which lines do we carry that no other store within an hour’s drive stocks?

Frequently asked questions

When does IHR Plugin launch, and what happened to September 2026?

The company now gives spring 2027 as the launch, with live transactions starting then. Founding access closes on March 31, 2027, and stores can connect and use the platform in preview mode before that.

Does it cost anything to be a fulfilling store?

The Starter plan has no monthly fee and charges 5 per cent per fulfilled order. Growth costs US$149 a month at 4 per cent, Professional US$399 at 3 per cent, and Enterprise is priced individually.

Which carriers ship network orders?

The platform selects what it describes as the cheapest reliable carrier for each order from Canada Post, UPS, FedEx, Purolator and others.

Can the selling store discount a product I ship?

Not below the brand’s minimum advertised price. MAP monitoring is included on every plan, and brands choose which resellers may carry their lines.

What is checked before a product can be sold through the network?

The catalogue is verified against Natural Product Numbers, and the company says the platform aligns with PIPEDA, Quebec’s Law 25 and Canada’s Anti-Spam Legislation for customer data and marketing consent.

Who can join as a store?

Health food stores, pharmacies, grocers, practitioners and clinics. Brands and distributors join on the vendor side.

Sources: ihrplugin.com, accessed October 28, 2026; Ontario Ministry of Labour minimum wage announcement, effective October 1, 2026, as reported by Hicks Morley, April 1, 2026. IHR Plugin terms are as published before launch and may change.
Natural Health Trends Just Showed What a Black Friday Discount Does to a Supplement Business

0
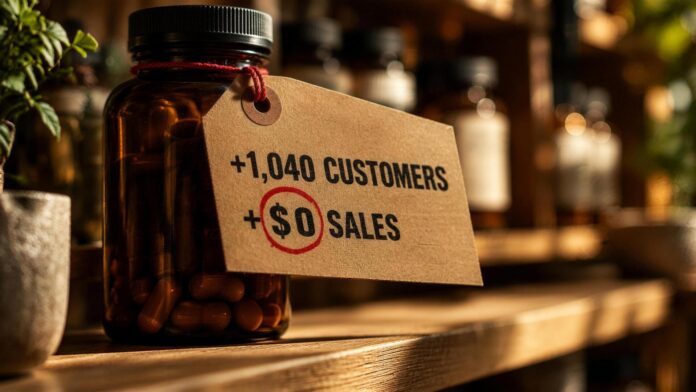
Natural Health Trends results on a supplement price tag: plus 1,040 customers, plus zero dollars in sales
Illustration: IHR Magazine.

Natural Health Trends results on a supplement price tag: plus 1,040 customers, plus zero dollars in sales

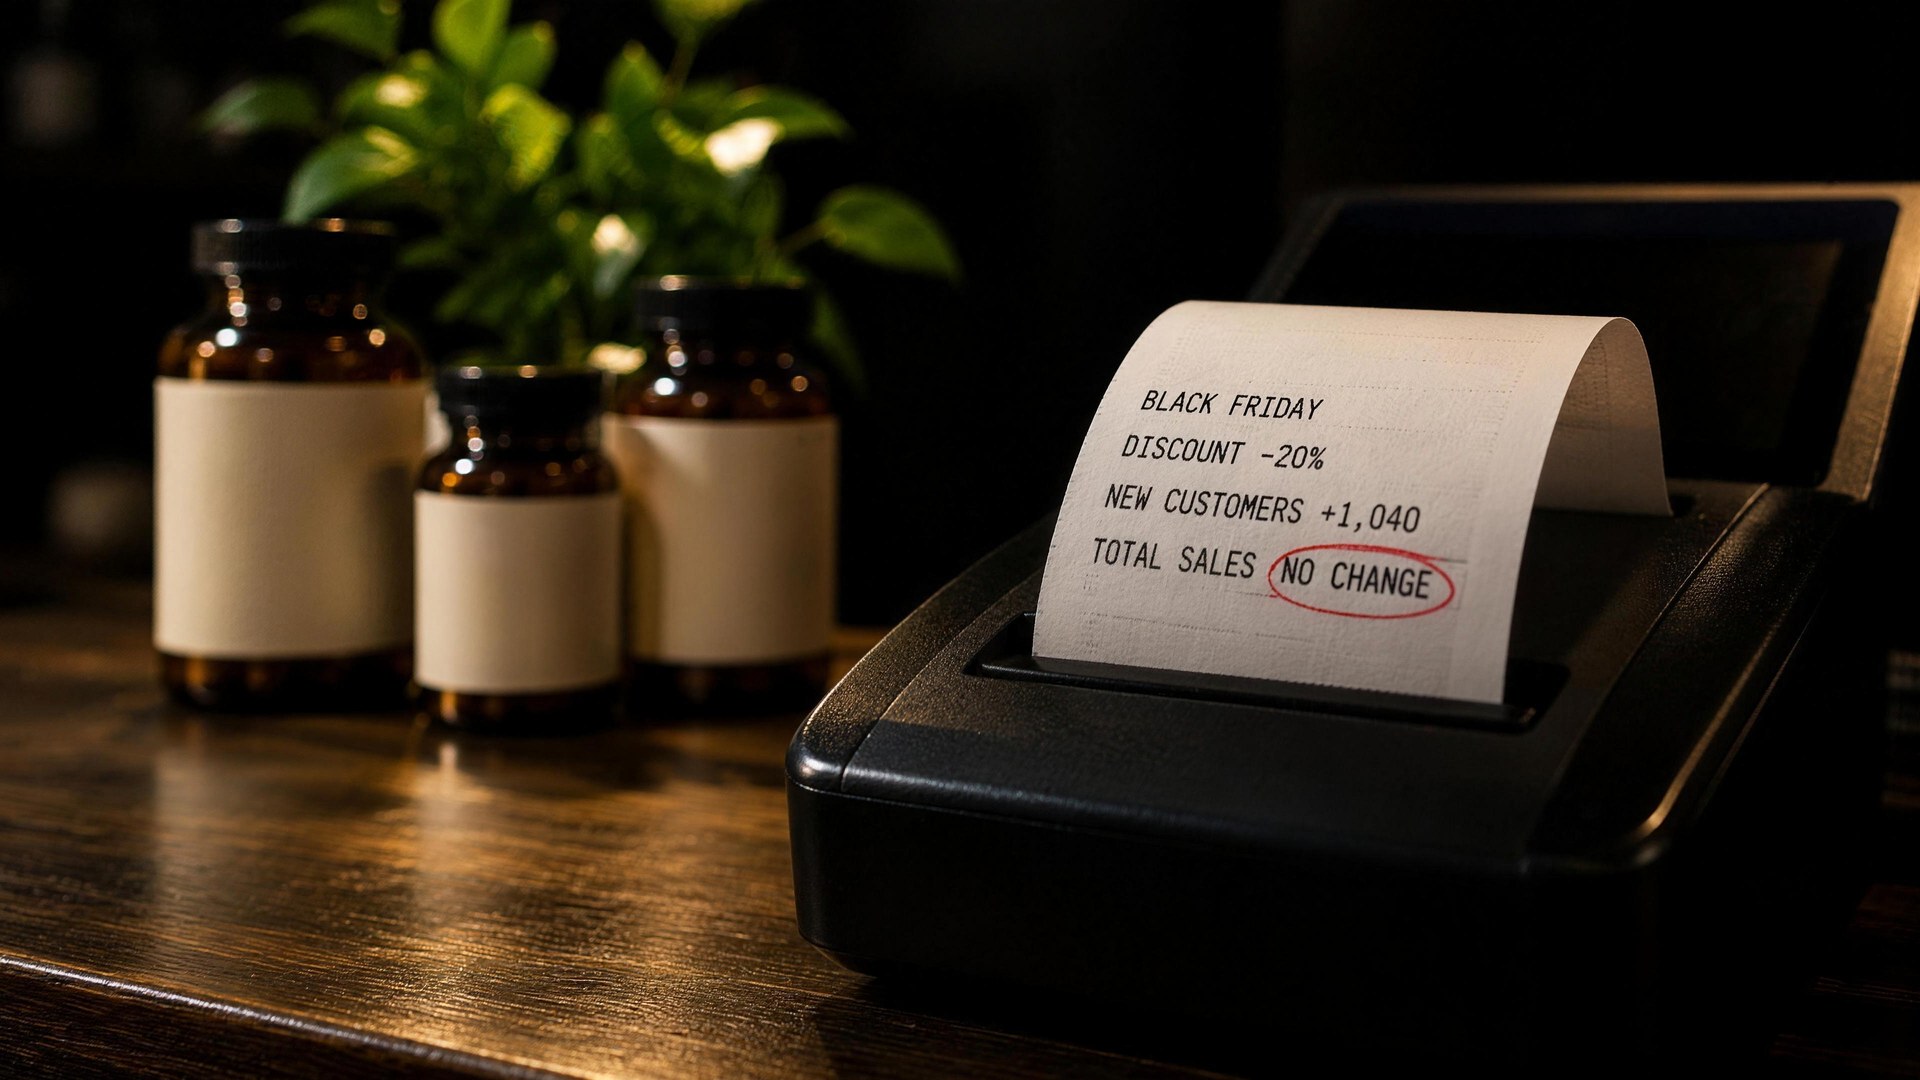
A discount brings in more customers but rarely more money, and the Natural Health Trends results released on October 28 put numbers on it. Natural Health Trends Corp. (Nasdaq: NHTC), a direct seller of supplements and personal care products, cut prices over the summer, gained 1,040 active members, and finished the third quarter with US$7.56 million in sales, the same as the quarter before. With Black Friday a month away, its books show the three things to check before marking anything down: what each customer spends, how many extra sales the discount needs, and who pays for it.

What did the Natural Health Trends discount buy?

Divide sales by active members and each one spent about US$280 in the quarter, down from US$338 a year earlier. Membership rose 4 per cent over the summer while spending per member fell by almost the same amount. According to its quarterly report, the company blamed its incentives and lower-priced packages for most of a 20 per cent drop in sales from last year. The promotion also cost a full point of gross margin. The smaller loss it reported came from paying its distributors less.

A store receipt reading Black Friday, discount minus 20 per cent, new customers plus 1,040, total sales no change
Illustration: IHR Magazine.

When a discount is worth it

The company had a reason to accept that trade. About 83 per cent of its revenue comes through Hong Kong from shoppers in mainland China, where demand has weakened, and it lost more than 3,000 members in the year to June. Keeping customers who were already leaving justified a lower price. A store whose regulars are steady has no such reason, and a deep November discount risks handing them money they would have spent at full price.

What makes a regular price legal in Canada?

A “was $60, now $45” tag in Canada must stand up under the Competition Act. The Competition Bureau accepts a regular price only if more than half of the product’s sales were at that price or higher. Failing that, the price must have been offered in good faith for a substantial period. Both tests usually look at the year either side of the sale. The Bureau warned last November of a surge in complaints about inflated regular prices around Black Friday.

Before you mark anything down

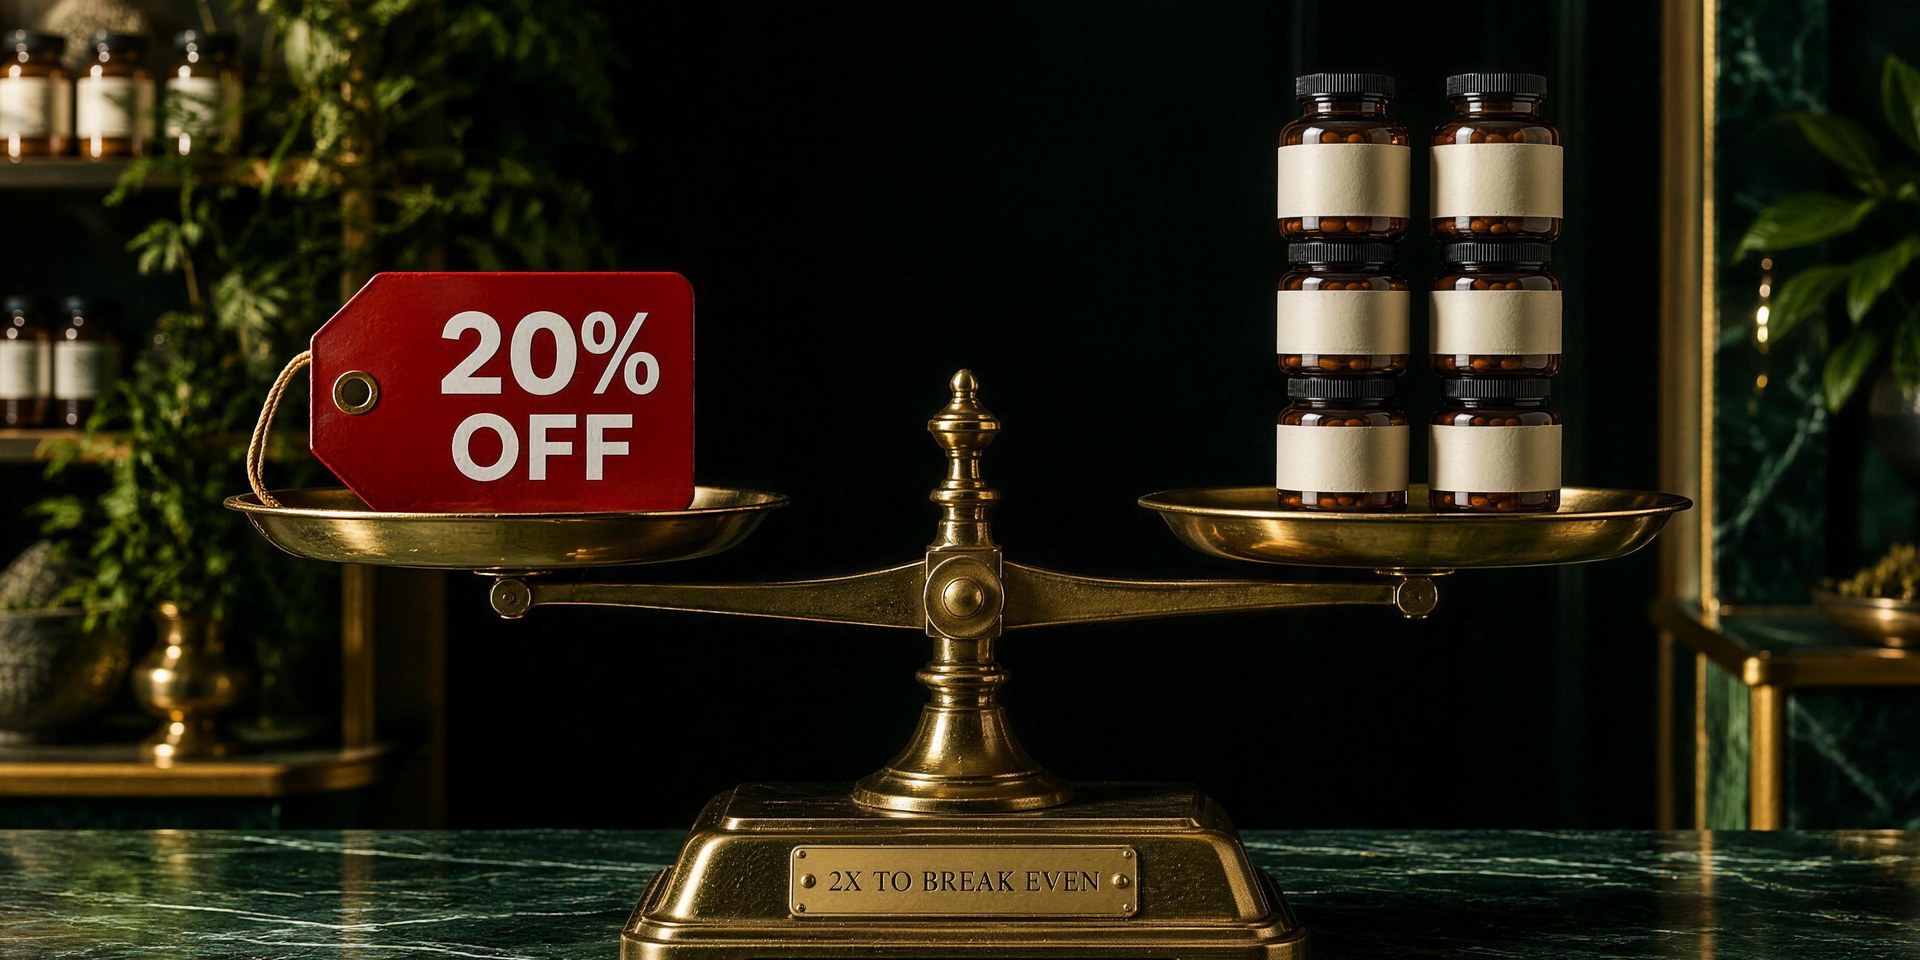
A brass balance scale with a 20 per cent off tag on one side and twice the stock of supplement bottles on the other
Illustration: IHR Magazine.
  1. Divide last November’s sales by the number of customers who bought, and judge this year’s discount against that figure rather than against foot traffic.
  2. Work out the volume you need. Your margin divided by your margin minus the discount gives the multiple of units required to earn the same gross profit. At a 40 per cent margin, 10 per cent off needs a third more units and 20 per cent off needs twice as many.
  3. Keep the sales records behind every regular price you advertise, and ask each supplier whether it or you will fund the discount.

Frequently asked questions

What were Natural Health Trends’ third quarter 2026 results?

The company reported a net loss of US$232,000, or US$0.03 a share, for the quarter ended September 30, against US$431,000 a year earlier. Its operating loss was US$277,000, and it gave no forecast for the fourth quarter.

Does Natural Health Trends sell in Canada?

Yes. Canada sits in its Americas segment with the United States, Mexico, Peru and Colombia, and Canadian sales are not reported separately.

Is a bundle safer than a percentage discount?

Only when no saving is advertised. “Save $15 when you buy two” is a savings claim, so it needs the same sales records behind it.

Is the company financially stable?

Its cash and securities fell to US$17.6 million from US$28.9 million in December, through buybacks, dividends and losses, and it declared no third quarter dividend.

Sources: Natural Health Trends third quarter 2026 release and Form 10-Q, October 28, 2026; second quarter 2026 release; Competition Bureau of Canada, ordinary selling price guidance and Black Friday notice of November 25, 2025. Figures in US dollars. Spending per member is IHR’s calculation from reported sales and active members.

Visa’s Small Merchant Rate Expansion: What It Is Worth to a Health Store

0
Customer tapping a credit card on a payment terminal at a natural health store counter

Visa is opening its lower interchange rate to stores with up to $750,000 in Visa sales. Newly eligible health retailers can keep thousands a year, while stores already in the program face a 2027 network fee that erases their cut on small baskets.

On October 24, Visa opens its lower small merchant interchange rate to businesses with up to $750,000 in annual Visa sales, more than double the previous ceiling of $300,000, and trims the rate for everyone already in the program. The Canadian Federation of Independent Business (CFIB), which announced the change, also flagged the catch. In April 2027 Visa will add a fixed network fee of 1.8 US cents to every domestic transaction, matching a fee Mastercard is rolling out now.

For a health retailer those two moves pull in opposite directions, and the store’s size and average basket decide which one wins. Owners who have just crossed into eligibility stand to keep well over a thousand dollars a year. Owners who were already in the program will see the fee absorb most of their cut, and on a $14 sale of a kombucha and a protein bar it absorbs all of it.

The program dates from a 2023 agreement between Ottawa, Visa and Mastercard that took effect in fall 2024 and brought in-store credit interchange for small merchants down to a weighted average of 0.95 per cent. Mastercard’s eligibility ceiling of $175,000 is staying put.

Who qualifies now

Eligibility is measured on Visa volume alone. Debit, Mastercard, American Express and cash sit outside the calculation, so a store with $1.5 million in total sales can easily fall under the new line. Retailers who assumed they had outgrown the program should add up the Visa totals from their last twelve monthly statements before drawing that conclusion.

The two networks now treat the same store differently. A shop with $400,000 on Visa and $250,000 on Mastercard qualifies for the lower Visa rate while paying full price on every Mastercard sale.

Health grocers have the most to gain from checking. When the original deal was finalized, the Canadian Federation of Independent Grocers said its thresholds were too low for any small or medium grocer to benefit. The higher Visa ceiling brings part of that group in, although full-line stores with several million in sales may still be over it.

What the saving comes to

Visa’s published general rate for in-store consumer credit is 1.25 per cent on Classic, Gold and Platinum cards and 1.57 per cent on Infinite. Some merchant categories already pay less through industry programs, such as 0.95 per cent under Grocery and Food Retail. Under the new schedule, small merchants pay 0.70 per cent in store on Classic cards and 0.89 per cent on Infinite, down from 0.77 and 0.99.

Take a newly eligible store running $500,000 a year through its Visa terminals. Each tenth of a percentage point on that volume is $500, so moving off the general Classic rate keeps $2,750 in the business and moving off the grocery rate keeps $1,250. On Infinite cards the gain is $3,400. Dan Kelly, CFIB’s president, said these merchants “will save thousands each year,” and at that volume he is right.

A store already in the program with $200,000 in Visa sales gets $140 a year from the Classic reduction and $200 from the Infinite one.

These figures are illustrative. They treat all volume as in-person consumer credit at a single rate and leave out processor markups, business cards and online sales, which carry their own rates.

How the 2027 fee changes the sum

Interchange is charged as a share of the sale, so a rate cut is worth more on a big basket. The network fee is a fixed amount. At the October 1 exchange rate of C$1.42 to the US dollar, it comes to roughly 2.6 Canadian cents per Visa transaction, whatever the customer buys.

For an existing small merchant, the cut and the fee cancel out at about $37 on a Classic card and about $26 on an Infinite card. Any smaller sale will cost the store more after April 2027 than it did before this October. The kombucha and protein bar save 1.4 cents in interchange and pick up 2.6 cents in fees.

The newly eligible store barely feels it. At a $45 average ticket, its $500,000 in Visa sales comes from about 11,100 transactions, so the fee totals under $300 a year against savings of $1,250 or more.

Mastercard got there first. CFIB says its fee now covers all domestic transactions, and the network fee notice from processor Moneris lists Mastercard’s Network Access and Brand Usage fee at US$0.022035 per domestic transaction from October 19, a little above CFIB’s figure. Retailers should budget from what their own statement shows. Corinne Pohlmann, CFIB’s executive vice-president of advocacy, called it “disappointing to see Visa and Mastercard increase their own slice of the payment fees.”

Why some stores will never see the cut

All of this assumes the processor passes the new rate along. Merchants on interchange-plus pricing pay interchange at cost plus a disclosed margin, so their statements reflect the lower rate automatically. Blended and flat-rate plans, common with tablet point-of-sale systems and e-commerce platforms, charge one percentage per sale, and the processor keeps any drop in interchange unless it decides to reprice. Network fees cut the other way on those plans. Some providers absorb them, and others recover them at the next rate review.

The account also has to be coded as a small merchant, and nothing on a statement total shows whether that has happened.

The case for leaving customers alone

A cent or two lost on a small basket is no reason to steer shoppers toward debit or put a minimum on card purchases. One $6 add-on at the till earns more margin than the fee gap on several dozen small sales, and pressure at the counter makes that add-on less likely. Supplement-led stores have even less to worry about. With average baskets above $40, an existing small merchant still comes out ahead on both card types after April.

Questions to put to your processor

  1. Will my account be coded for Visa’s small merchant rate on October 24, and what annual Visa volume are you basing that on?
  2. Am I on interchange-plus pricing, and if not, will my rate change when interchange falls?
  3. Which network fees do you charge me per transaction, and what will Visa’s April 2027 fee add to my annual cost?
  4. What would my effective rate be on interchange-plus at my current volume?

Frequently asked questions

Does American Express offer a similar small business rate?

No. The 2024 agreements covered Visa and Mastercard only. CFIB is calling on Mastercard and the other card brands to follow Visa’s lead and has pushed for American Express to join since the original deal.

Are online sales included?

Yes, at separate card-not-present rates. Visa’s small merchant online rate drops from 1.30 to 1.20 per cent on Classic cards and from 1.55 to 1.45 per cent on Infinite.

What happens with premium cards such as Visa Infinite Privilege?

Their rates fall too, from 1.80 to 1.70 per cent in store and from 2.30 to 2.20 per cent online. Infinite+ online transactions go from 2.20 to 2.05 per cent.

Are debit costs changing?

Slightly. Moneris reports that the Interac switch fee on card-present debit rises from $0.015803 to $0.016315 per transaction on November 1, 2026.

Figures current as of October 20, 2026. Rate arithmetic is illustrative.

Sources

Have That Conversation: What Canadian Health Retailers Need to Know About Kratom

0
A customer's basket at a health food store till holding a tincture, grapefruit juice and capsules, mid-conversation with a store associate

Health Canada has never approved a kratom product. Your customers use it anyway, and some of what they buy from you changes how it works.

He comes in most Thursdays after work. Tonight it is a CBD tincture, a litre of grapefruit juice and a bottle of kava for sleep. While you bag them, he mentions, almost in passing, that he is trying to cut back on kratom. He used to buy the powder. Now he orders tablets online.

You have about ten seconds to decide whether to say anything. Most staff say nothing, because nobody has ever told them what kratom is or why that particular basket matters. This article is for the store that wants its people to speak up.

The tablet is not the leaf

Kratom comes from the leaves of Mitragyna speciosa, a tree native to Southeast Asia, and it has no legal route to the Canadian market. Health Canada seized it from shops in Edmonton, Milton and the GTA in 2017 and 2018, and stated that it “has not authorized the sale of any product containing kratom.”

What your regular is taking today is something else. The leaf holds only a trace of 7-hydroxymitragynine, or 7-OH, under 0.05 per cent by weight. Manufacturers have learned to concentrate or synthesize it, and in lab tests 7-OH is about 13 times as potent as morphine. A Canadian-facing website updated in March sells 7-OH tablets from 20 mg to 60 mg. It ships from inside Canada, takes Interac e-Transfer and prints “not intended for human consumption” on the label.

The United States shows where this leads. Poison centre calls involving kratom rose 1,200 per cent between 2015 and 2025, according to Centers for Disease Control and Prevention figures cited in Health Affairs, and the steepest climb came after the concentrated products appeared. Washington is now moving 7-OH toward Schedule I. Ottawa has not scheduled it at all.

Why his basket matters

Mitragynine, the main alkaloid in kratom, partly switches on the mu-opioid receptor, the same receptor that morphine and oxycodone act on. In small amounts it feels more like strong coffee. In larger amounts it behaves like an opioid. Sellers like to say it spares breathing, but rat studies on 7-OH tell a different story: breathing slowed, and repeated doses brought tolerance and withdrawal.

The part your staff can do something about happens in the liver. One enzyme, CYP3A4, clears mitragynine from the body and also turns some of it into 7-OH, a conversion researchers confirmed in human volunteers in 2024. Anything that slows that enzyme changes the dose your customer actually receives. Kratom slows it too. In a 2023 clinical study, a single cup of kratom tea raised blood levels of midazolam, a standard test drug, by 39 per cent, and many benzodiazepines, statins and some blood pressure pills are cleared the same way.

Look at the Thursday basket with that in mind. These are the kratom interactions most likely to start on your own shelves.

Product What it does with kratom How solid the evidence is
CBD oil Raised mitragynine levels 2.8-fold and delayed the peak, which tempts people to take a second dose too soon One rat study
Grapefruit and other CYP3A blockers Pushed up both mitragynine and 7-OH and multiplied their opioid effects Rat studies; the researchers named citrus juice as a concern
Goldenseal Cut the activity of a second liver enzyme, CYP2D6, by about half; mitragynine blocks the same enzyme in lab tests Human study for goldenseal
Kava, valerian, passionflower, hops Pile sedation on top of an opioid; a kava and kratom drink left one man in hospital with withdrawal from both Pharmacology and a 2025 case report
Caffeine, yohimbe, bitter orange Add to the racing heart and seizure risk Health Canada already lists for kratom Pharmacology
St. John’s wort Speeds up CYP3A4, which could lower mitragynine but raise 7-OH Never studied

Two of those rows need a closer look. CBD runs through almost every kratom user’s routine, and in one U.S. survey about 92 per cent of kratom users had also used cannabis. Grapefruit is the sneakier one. Kratom forums recommend it as a way to make kratom hit harder, so a customer who pairs grapefruit extract with a sleep aid may know exactly what he is doing.

Kratom that doesn’t say kratom

For the store itself, the bigger risk is a product that arrives in a distributor’s box under another name.

In Burnaby, chemists at the British Columbia Institute of Technology bought products labelled “kratom extract” and put them through the lab. They found 22 to 75 mg of 7-OH per gram, more than the labels promised, plus compounds that never occur in the leaf. Their conclusion, published this year in the Journal of AOAC International, was that such levels are “achievable only by synthetic means.”

The drinks fridge has its own version of the problem. In September, Arizona sued Botanic Tonics, the company behind the “feel free” shot. The state says the bottle was designed to look like an energy shot, sold as a kava drink with “other ancient plants” and pitched to sober-curious young adults, and that some users were drinking seven bottles a day. Attorney General Kris Mayes said there is “real danger of addiction and other mental and physical harm.” The company had already settled an earlier class action for $8.75 million.

If your store carries alcohol alternatives, functional shots or botanical blends, read the ingredient panel as closely as you would a supplement label. Mitragyna speciosa, “kratom extract” or a vague “botanical blend” without a Canadian product licence means the item does not belong on your shelf.

Your staff and your premises

Kratom can also become a staffing issue. Since June 1, 2023, Ontario employers who know, or ought to know, that a worker may be at risk of an opioid overdose have had to keep a naloxone kit on site with a trained worker nearby. If you learn that an employee is taking 7-OH tablets, get advice on whether that rule now applies to you. Ottawa’s powers have grown as well. Vanessa’s Law, extended to natural health products in 2023, lets Health Canada order recalls and label changes when a product poses a serious risk.

Don’t overcorrect

Most kratom customers are not in danger, and treating them as though they are will cost you their trust and their business. Much of the interaction research comes from rats or from a dozen healthy volunteers given a single cup of tea. That same 2023 study found no effect on CYP2D6, even though test-tube work had predicted one. Even the BCIT chemists drew a firm line between the traditional leaf and synthetic 7-OH.

Your policy should draw the same line. Concentrated or disguised products get zero tolerance on the shelf. The customer who drinks leaf tea gets patience and good information, because a lecture only sends him back to the forum that told him about grapefruit.

How to have the conversation

At the till, it can be short. During the usual chat about what else he takes, ask: “Do you use kratom, including tablets, shots or gummies?” If the answer is tablets, steer him away from the CBD, grapefruit and kava combination today and suggest he run his routine past a pharmacist. Then write down the date and what you suggested, which protects the store and gives you the details Health Canada asks for if you ever file a report.

Away from the till, three jobs are worth finishing this quarter. Look up every tonic, shot and botanical blend in Health Canada’s Licensed Natural Health Products Database, and pull anything without a valid NPN or DIN. Ask botanical suppliers for a certificate of analysis that tests for alkaloids, so that a “kratom-free” claim comes with a lab result attached. Finally, get at least one person on each shift trained on naloxone through a provincial program, and report suspected reactions through the Canada Vigilance Program.

When American shelves empty, those tablets will go looking for new buyers. The stores that have already had this conversation will see them coming.

Frequently Asked Questions

Does naloxone reverse a 7-OH overdose?
Yes. The American College of Medical Toxicology reports that naloxone has reversed 7-OH-related breathing problems in animal studies and in human case reports. Toxicologists warn against taking 7-OH alone or with alcohol or benzodiazepines, since a person who stops breathing needs someone nearby to give the naloxone.

How is kratom or 7-OH dependence treated?
Doctors treat it the way they treat opioid dependence. Buprenorphine and methadone, the standard medications for opioid use disorder, have been used successfully for people coming off 7-OH. Supplements are not a substitute, so a customer asking for help should be sent to a physician, pharmacist or addiction service.

Is a “kratom” gummy the same thing as kratom leaf?
Often not. A 2025 audit cited in Health Affairs found hundreds of 7-OH products on the U.S. market, mostly tablets, shots and gummies, and more than 93 per cent of them were sold simply as kratom. Customers often do not know which one they have, so ask about the form.

Is the United States banning 7-OH?
A ban is close. The DEA’s latest proposal, published for public inspection in October 2026, covers products with more than 1 mg of 7-OH per gram or millilitre, or a mitragynine-to-7-OH ratio below 100. Plain leaf under those limits would stay legal, so the target is concentrated products.

What happens to a Canadian store caught selling kratom?
Health Canada treats kratom as an unauthorized health product, and selling one is illegal. Earlier cases ended with stock seized from the store. The regulator also works with the Canada Border Services Agency to stop shipments at the border before they reach distributors or retail shelves.

This article is for trade education and is not medical or legal advice. Retailers should consult a pharmacist, physician or regulatory adviser on specific cases.

IHR Magazine is Canada’s business intelligence publication for the natural health, nutraceutical and personal care industry, covering regulation, retail strategy and ingredient science at ihrmagazine.com.

Sources

Blood-Sugar Botanicals Have a Dose Problem

0
Turmeric, cinnamon and dried herbs in laboratory test tubes — natural products for blood sugar under the evidence lens
Photo: Josianne Pinard / Unsplash

Turmeric, fenugreek and cinnamon sell on their names. The evidence says the dose, the delivery form and the licence decide whether they earn the shelf.

Five grams a day. That is the point where fenugreek starts to lower blood sugar in clinical trials, and it takes more than eight 600 mg capsules to get there. Natural products for blood sugar are bought by ingredient name. Their results depend on dose, delivery form and licence.

That gap matters because the shopper base is enormous. Diabetes Canada counts 11.9 million Canadians living with diabetes or prediabetes in 2024, or 30 per cent of the population. Diagnosed diabetes is projected to grow another 32 per cent by 2034. Globally, glucose-management supplements were worth about US$9.9 billion in 2025, according to Persistence Market Research, with 6.4 per cent annual growth forecast through 2032.

A big category resting on small trials

A new narrative review in Nutrients (2026, 18(20):3318), from Texas Tech University researchers Deshmukh, Kshirsagar and Gollahon, takes stock of the evidence. It covers curcumin, fenugreek, cinnamon, garlic, ginger, cumin, coriander, honey, shilajit and guduchi.

The verdict is cautious. Most of the support comes from cell and animal studies. Human trials are few, small and built on inconsistent formulations. The authors describe the best candidates as “possible additions to conventional diabetes pharmacotherapy” and ask for standardized chemical profiling and multicentre trials before routine use.

Read as a buyer, that is not a dismissal. It is a sorting tool.

What natural products for blood sugar actually deliver

Fenugreek has the clearest dose signal. A meta-analysis in Nutrition Journal pooled 10 trials with 278 participants. Fasting glucose fell by an average of 0.96 mmol/L and HbA1c by 0.85 percentage points, the latter from only three trials. The effect appeared at 5 g a day or more of powdered seed. Low-dose extracts under 2 g showed nothing significant. The trials were also of low methodological quality.

Curcumin’s headline trial is a decade old. The study the review highlights was published in 2016. It gave 70 adults with type 2 diabetes 80 mg a day of curcumin in a nano-micelle form for three months. HbA1c, fasting glucose, triglycerides and BMI all fell. The delivery system is the point: ordinary curcumin is poorly absorbed and quickly cleared, so a standard turmeric capsule cannot borrow that result.

Garlic and honey are weaker plays. Garlic’s clinical signal is a modest drop in cholesterol, not glucose. Honey’s effect swings with its composition, and it is still a carbohydrate.

Canada licenses less than the shelf promises

Diabetes is a Schedule A disease. Under section 3 of the Food and Drugs Act, no product may be advertised to the public as a treatment or cure for it. Natural health products get one exemption: prevention, which Health Canada reads as risk reduction. Even that claim needs randomized trial evidence and must appear on the licence.

Here is what the three best-known ingredients can actually say:

  • Cassia cinnamon may claim it “helps to support/maintain healthy blood glucose levels” at 3 to 6 g of dried bark a day, with no single dose above 4 g.
  • Fenugreek’s current monograph covers only topical use on minor skin wounds. An oral glucose claim exists only if that specific product earned it through its own licence application.
  • Berberine, sold online as “nature’s Ozempic,” is not automatically a glucose product either. One leading Canadian brand’s licensed berberine is authorized for healthy lipid levels and carries a diabetes caution.

The practical rule follows. A claim is an asset only when it matches the NPN word for word. U.S. structure-function copy, an influencer quote on a shelf talker, or a sign reading “for diabetics” can turn a licensed product into a Schedule A advertising problem. That exposure lands on the store, not just the brand.

Cinnamon: licensed, contested and full of coumarin

Cinnamon is the strangest case on the shelf. It holds the only monograph glucose claim of the three, yet the research cannot agree on whether it works.

The largest recent pooling, published in Nutrition Reviews in 2025, combined 28 randomized trials and 3,054 adults with type 2 diabetes. It found fasting glucose about 0.85 mmol/L lower and HbA1c down 0.56 points. But the studies disagreed sharply with each other, with heterogeneity near 90 per cent. A 2023 dose-response analysis in Nutrients covered 15 trials and 965 people and found no significant change in fasting glucose or HbA1c at all. What it did find was better blood lipids: lower triglycerides and LDL, higher HDL. The Texas Tech review lands in the middle, calling results across 24 trials inconsistent.

The commercial read is that cinnamon is a modest, whole-metabolism product. Selling it as a glucose fix overpromises. Selling it as part of a metabolic routine is honest.

The bigger issue is a compound called coumarin. Cassia bark carries roughly 2,100 to 4,400 mg of it per kilogram, according to Germany’s Federal Institute for Risk Assessment. Ceylon cinnamon contains only traces. In large amounts, coumarin can damage the liver. Europe’s tolerable daily intake is 0.1 mg per kilogram of body weight, or 6 mg for a 60 kg adult. On the institute’s numbers, that ceiling is reached at about 1.4 to 2.9 g of cassia a day.

Put that beside the licence. Health Canada’s cassia monograph supports the glucose claim at 3 to 6 g a day and sets no coumarin limit. It does require a pregnancy contraindication and a diabetes caution from 1 g a day, plus a practitioner check for use beyond six weeks at 4 g or more. The claim is legal. The coumarin load at that dose deserves a direct question to every supplier.

One more flag sits in the spice aisle. In 2024 the U.S. FDA warned about lead in several ground cinnamon brands. The CFIA said it was monitoring and knew of no Canadian distribution, but stores selling bulk cinnamon should ask for heavy-metal testing.

The safety file just got thicker

Health Canada’s summary safety review of oral turmeric and curcuminoids examined 12 Canadian case reports and more than 60 international ones. Three deaths were reported, two attributed to liver injury. The agency found a possible link and called the risk idiosyncratic: unpredictable and unrelated to dose. Licence holders are now expected to list warning signs such as yellowing skin and dark urine. Labels must also tell anyone with a liver disorder, or on medication, to check with a professional.

Guduchi carries a sharper signal. A multicentre study in Hepatology Communications documented 43 patients across 13 Indian centres with liver injury linked to the herb, appearing a median of 46 days after starting it. Some shilajit products raise a different worry: possible contamination with toxic metals.

Then there is the customer’s medicine cabinet. Someone on metformin, insulin or a GLP-1 drug who adds a glucose-active botanical can stack effects. Diabète Québec tells people with diabetes plainly that natural products cannot replace medication and that blood glucose should be checked more often when trying one.

Four moves for the next reset

  1. Run a dose audit. Compare each SKU’s daily dose with the dose that was studied. A 500 mg fenugreek extract is not the 5 g of seed in the trials.
  2. Run a licence audit. Pull every NPN and strip any shelf, web or email copy the licence does not carry.
  3. Raise the supplier bar. Ask for the studied form and dose, coumarin per daily serving for cassia, heavy-metal certificates for shilajit and bulk spice, and proof that turmeric labels carry the new liver warnings.
  4. Train one question. Staff should ask what medication a customer takes before recommending anything, then point them to a pharmacist for interaction checks.

The brands that will own this category are the ones paying for the trials the review asks for. Retailers who stock to the studied dose today will be ready to carry them.

Frequently Asked Questions

Do natural products for blood sugar work?

Some show measurable effects, but the evidence is thin. A 2026 review in Nutrients found most support comes from cell and animal studies, with small, inconsistent human trials. Researchers describe the strongest candidates, such as nano-curcumin and high-dose fenugreek, as possible additions to diabetes medication rather than substitutes for it.

How much fenugreek is needed to affect blood sugar?

In a meta-analysis of 10 trials, fenugreek lowered fasting glucose only at doses of 5 g or more of powdered seed per day. Low-dose extracts under 2 g a day showed no significant effect. A single 500 to 600 mg capsule supplies roughly a tenth of that, so the daily label dose matters.

Is cassia or Ceylon cinnamon better for blood sugar products?

They trade off. Cassia is the species with a Health Canada glucose monograph, but it is rich in coumarin, which can harm the liver at high intakes. Ceylon contains only trace coumarin. Buyers stocking cassia at the licensed dose should ask suppliers how much coumarin each daily serving delivers.

What blood sugar claims can natural health products make in Canada?

Only the claim on the product’s licence. Diabetes is a Schedule A disease, so treatment or cure claims to the public are prohibited. Cassia cinnamon is the clearest licensed route, with a monograph healthy-glucose claim. Fenugreek, berberine and most other botanicals need product-specific evidence approved by Health Canada for any glucose wording.

This is independent editorial analysis for the natural health trade, based on published research and Health Canada guidance. It is not medical advice and does not endorse any ingredient, brand or product. Verify NPN status and licensed claims for every SKU.

Jamieson Shareholders Approve Kirin Takeover, With 29.5% Opposed

0
Jamieson Wellness Kirin shareholder vote: a Jamieson vitamin D3 bottle handed from one person to another, illustrating the sale of the company to Kirin Holdings
Photo: Jamieson Wellness

With court approval in hand, the deal now waits on federal regulators, and retailers have a short window to settle their terms before a new owner takes over.

Updated October 8, 2026, after the Ontario court’s final approval of the arrangement.

Jamieson Wellness shareholders approved the company’s sale to Kirin Holdings at a special meeting on Wednesday, September 30, accepting C$45.75 a share in cash. The resolution received 70.51 per cent of votes cast, against a required two-thirds.

Had roughly 1.2 million shares, or less than 4 per cent of the votes, gone the other way, the resolution would have failed. For a recommended offer, the cushion was small. Jamieson’s board backed the sale unanimously, BMO Capital Markets and Canaccord Genuity provided fairness opinions, and both ISS and Glass Lewis advised investors to support it.

Executives shake hands over a signed acquisition agreement, illustrating the Kirin Jamieson Wellness transaction
Kirin agreed to pay C$45.75 a share in cash. (Illustration)

A question of price

The company has not disclosed who voted against the deal, but the offer itself points to a likely explanation. Kirin is paying about 16 times trailing adjusted EBITDA, a premium of roughly 27 per cent to Jamieson’s average share price in the weeks before June 24.

That price values Jamieson as a mature consumer staple. Its recent growth, however, has come mainly from China and the United States, where sales have been rising several times faster than in Canada, as IHR reported in August. Investors who expected that growth to continue had grounds to hold out for more.

The transaction now gives anyone buying or selling a large Canadian supplement business a public reference point. Buyers are likely to cite the multiple Kirin paid, while sellers can argue that a sizable block of Jamieson’s own investors considered it too low.

Less visibility for retailers

Jamieson vitamins and supplements including Iron, Glucosamine Plus and Chewable C, products now headed for Kirin ownership
Jamieson products. Photo: Jamieson Wellness

When the sale closes, Jamieson’s shares will be delisted from the TSX and the company will no longer file public reports. Its quarterly results have given retailers and suppliers a regular view of Canadian VMS demand, including which need states were growing, how much category volume depended on promotion, and how busy its contract manufacturing lines were. After closing, those numbers will be folded into Kirin’s group accounts, where the Canadian business will be one segment among many.

Category managers who read Jamieson’s results alongside their own scan data when planning sets will need to find that context elsewhere, whether through supplier meetings, syndicated data or industry associations.

Before the deal closes

The Ontario Superior Court of Justice (Commercial List) issued its final order approving the arrangement on October 5, which leaves regulatory clearance as the main step before closing. Jamieson says that process is still under way. Given its size, the transaction may face a net benefit review under the Investment Canada Act, and any undertakings Kirin gives Ottawa would be the first binding commitments on Jamieson’s head office, plants and investment in Canada. Both companies expect to close in the fourth quarter.

That timing overlaps with 2027 line reviews. Retailers negotiating promotional funding and listing terms with Jamieson this fall should make sure those agreements specifically survive a change of control. Brands that rely on Jamieson’s plants for contract manufacturing would be wise to settle capacity and renewal terms with the current management team.

Retailers should not expect Kirin’s other supplement brands to arrive on Canadian shelves quickly. The group owns Australia’s Blackmores and Japan’s FANCL, but each of their products would need its own Natural Product Number from Health Canada before it could be sold here.

Competing brands may find buyers more receptive in the coming months. Decisions at acquired companies often slow while new reporting lines are put in place, and a supplier able to offer stable pricing and quick answers on promotions will have an easier time winning shelf space.

Frequently Asked Questions

Why did the Jamieson Wellness deal need two separate shareholder votes?

Ontario plans of arrangement need approval from at least two-thirds of the votes cast. Securities rule MI 61-101 also requires a simple majority of minority shareholders, which leaves out shares held by insiders who receive benefits other holders do not. At Jamieson, only 82,354 shares were excluded, and the second count came in at 70.43 per cent.

How much is Kirin paying for Jamieson Wellness in total?

Kirin values Jamieson’s equity at about C$1.9 billion, or roughly 218 billion yen, and the enterprise value including debt is about C$2.5 billion. The agreement includes a C$70 million fee payable to Kirin if Jamieson accepts a superior offer. The sale process started after an unsolicited proposal in March 2026.

Will Jamieson Wellness keep paying a dividend before the sale closes?

Yes. The agreement lets Jamieson continue its regular quarterly dividend until closing. The latest payment, C$0.25 a share, went out on September 15, 2026, up from C$0.23 previously. Dividends end once the transaction is completed and shareholders are paid out in cash.

Which brands are included in the Kirin acquisition?

Kirin is acquiring the entire portfolio: Jamieson, a brand founded in 1922, along with youtheory, Progressive, Smart Solutions, Iron Vegan and Precision. The products are sold in more than 50 countries. Kirin has said it plans to use the business as a North American platform for its health science division.

Sources: Jamieson Wellness obtains final court approval for plan of arrangement with Kirin (Newswire, Oct. 5, 2026) · Jamieson Wellness obtains shareholder approval for sale to Kirin (Newswire, Sept. 30, 2026) · Jamieson Wellness enters definitive agreement with Kirin (Newswire, Aug. 2026) · Management information circular filing (Jamieson Wellness) · ISS and Glass Lewis recommendations (Newswire, Sept. 16, 2026) · Kirin Holdings notice of acquisition · Kalkine: Jamieson dividend ahead of the Kirin takeover

Sobeys Can No Longer Block the Pharmacy Next Door. The Paperwork Hasn’t Caught Up.

0
Sobeys Can No Longer Block the Pharmacy Next Door

You have found the unit. It is an end space with its own entrance, two doors from a Sobeys, in a plaza whose lot is full by five o’clock. The landlord has been trying to fill it since spring. You have already sketched the fit-out: dispensary at the back, a supplement wall along the front window, a cooler by the till. Then the leasing agent calls back, sounding apologetic. The anchor has an exclusive, he says. No pharmacy, and nothing that sells food.

On September 22, that answer lost its legal footing wherever the anchor belongs to Empire Company Limited, owner of Sobeys, Safeway, IGA, Foodland, FreshCo, Farm Boy, Marché Bonichoix and Les Marchés Tradition. The Competition Bureau registered a consent agreement with the Competition Tribunal that carries the force of a court order. Empire can no longer enforce or create exclusivity clauses against specialty food retailers, a group the Bureau says includes pharmacies, and it has given up restrictive covenants altogether.

The agreement does not reach into your landlord’s filing cabinet, though. The exclusive stays in the anchor’s lease, and any covenant stays registered on title, until someone asks Empire to release it. What you get back then turns on two definitions buried in the agreement’s text: whether your store counts as a specialty food retailer, and whether the clause blocking you is about food at all. The independents who read those definitions and move first this fall will get the good units, while everyone else keeps getting the old phone call.

Where Canada’s grocers stand on property controls, September 2026

Grocer What has changed How binding
Empire (Sobeys and banners) No covenants; no exclusivity against specialty food retailers, pharmacies included; no radius clauses Consent agreement registered with the Competition Tribunal, in force for 10 years
Loblaw Covenants removed or waived; exclusivity waived in Halifax, in one-grocer towns and for specialty food stores (pharmacies not named) Public commitment, monitored by the Bureau since June 2025
Walmart Canada Competitive retail restrictions in its leases waived, November 2024 Company decision, landlords notified
Metro and other grocers Nothing announced by the Bureau Investigation ongoing
Any grocer in Manitoba Grocery property controls void unless re-registered Provincial law since 2025

Why a grocer cares who sells vitamins

Sobeys fills prescriptions inside many of its stores and owns the Lawtons Drugs chain. The executive who signed the agreement for Empire, Doug Nathanson, carries the title General Counsel and Chief Pharmacy & Development Officer, which puts pharmacy and real estate development under one desk. An independent pharmacy two doors down competes for the same prescriptions and the same front-shop vitamin sale. A health food store goes after something the grocer values even more: the shopper whose basket is full of organic, gluten-free and supplement products, the highest-margin cart in the building. Seen from an anchor’s real estate office, an exclusive that keeps both out is cheap insurance.

Covenants were the more durable weapon, because they bind the land itself and survive a change of owner. The Bureau’s guidance calls them “particularly concerning” for exactly that reason. In Crowsnest Pass, a Rocky Mountain community of a few thousand people, Empire’s IGA was the only grocery store in town, and a covenant Empire had held since 2017 kept a competing grocer out. It came off only in January 2025, after the Bureau stepped in, clearing the way for a second store. The same logic means a vacant box where a Sobeys closed years ago can still be fenced off by a document nobody has looked at since.

How many of these documents exist is anyone’s guess, because no national count has been published. The one jurisdiction that forced them into daylight is Manitoba. When its new law gave grocers 180 days to re-register any control they wanted to keep, at least 46 were submitted for confirmation and 23 more were surrendered for removal, in a province of about 1.5 million people.

Which side of the line your store sits on

The consent agreement, now posted on the Competition Tribunal’s website, answers the question the announcement left open. A Grocery Store is one whose primary business is selling grocery food products and which offers a full assortment of them. A Specialty Food Retailer sells only “a subset or limited assortment,” and the agreement names bakeries, butchers, frozen food stores, pharmacies, dollar stores and convenience stores, while excluding any business “operating as tantamount to a Grocery Store.” For most health food stores that is good news. A shop whose primary business is supplements and natural health products cannot be a Grocery Store under that test, however much kombucha sits in its cooler. The exposure belongs to the full-line natural grocer, whose produce wall, bulk bins and frozen aisle start to look like a full assortment.

The same definitions set a limit that no announcement mentioned. Every obligation turns on “Grocery Food Products,” meaning food and beverages customarily sold by a grocery store, from produce and dairy to confectionery and prepared meals. The agreement expressly excludes any restriction that applies solely to other products. Vitamins, natural health products and prescriptions appear nowhere in the list. The deal therefore frees a pharmacy’s snack aisle and a health store’s cooler, while a lease clause that bars a tenant from dispensing or from selling supplements sits outside it. Before you celebrate, find out which kind of clause is in your plaza.

Full grocers get thinner protection still. Empire must stop enforcing existing exclusives in its own grocery leases in only 19 local markets, listed in a schedule to the agreement: Bonnyville, Alta.; Bishop’s Falls, N.L.; Grand Bay-Westfield, N.B.; Paris and Thornbury, Ont.; New Glasgow, New Ross, Pictou, Coldbrook and Truro, N.S.; and Cadillac, Lac Brome, Grenville, Repentigny, Victoriaville, Terrebonne, Contrecoeur, Saint-Hippolyte and Paspébiac, Que. Radius clauses, which reach beyond the plaza, are dead everywhere. Nothing in the agreement, however, stops Empire from signing new exclusives against full grocery stores inside its own plazas. Its promise to narrow those lives only in the voluntary policy it published in July.

Asking for the release

Anyone with a business interest in the site can make the request, including a landlord, a tenant, a prospective tenant, a purchaser or a developer. Empire takes requests through empireco.ca/propertycontrols, and the agreement puts it on a clock. It must acknowledge a request within five business days. Within 20 business days it must discharge, waive or amend the control, or decline in writing with reasons. That clock is the most useful thing in the document, because a landlord will rarely risk a default notice from its anchor on the strength of a press release, but will act on a signed waiver. Keldon Bester of the Canadian Anti-Monopoly Project, reacting to Empire’s first pledge in July, urged regulators to “trust, but verify.” The four questions below are how a retailer does the verifying.

  1. To the landlord: “Which clause are you relying on, whose lease is it in, and does it restrict food or something else?” The answer tells you whether you are dealing with Empire, a grocer from the table above, or a restriction the agreement does not touch.
  2. To Empire: “Is my store a Specialty Food Retailer as the consent agreement defines it, and will you confirm in writing that you will not enforce against this address?” If the answer is no, the reasons have to come in writing too.
  3. To your real estate lawyer: “Is a covenant registered on this parcel, or a neighbouring one, in favour of Empire, a former Empire store or a company Empire partly owns, and has a discharge been filed?” The agreement only obliges Empire to ask such companies for a waiver once it learns of a covenant, and says outright that it need not search the land registry. That matters because Empire holds a 41.5 per cent interest in Crombie REIT, a national owner of grocery- and pharmacy-anchored shopping centres.
  4. To yourself, with your current lease open: search for “food”, “grocery”, “supermarket”, “pharmacy” and any cap on floor area devoted to food. A restriction your landlord once agreed with an anchor may be what stops you adding a fridge wall or bulk section at the store you already run.

What comes next

Empire is the first grocer to turn its property control pledges into an order a tribunal can enforce, filed under section 90.1 of the Competition Act. It admits no wrongdoing and says it disagrees with the Bureau’s conclusions, but has agreed not to contest them. The Bureau says its investigation of other grocers continues, and in June it opened a broader examination of competition across the food supply chain, from processing to retail pricing. Landlords should note the section the Bureau used. Since the amendments of December 2023, section 90.1 can reach anti-competitive agreements between parties who do not compete with each other, such as a grocer and the owner of its plaza, and the Bureau’s guidance notes that administrative monetary penalties are available.

For pharmacists and natural health retailers, the result is a new supply of locations. Every unit that comes vacant beside a Sobeys, Safeway or IGA from here on is one they can bid on, and the landlord now has a reason to take the call.

Frequently Asked Questions

Does Loblaw’s commitment help a store trying to lease beside a Shoppers Drug Mart?
Partly. Loblaw said that from November 2024, new Shoppers Drug Mart and Pharmaprix leases would carry no restrictions on the sale of food products. It also pledged not to enforce or sign exclusivity clauses reaching beyond the land its own store occupies. Older Shoppers leases fall under its voluntary commitment rather than a tribunal order.

What can I do if Empire refuses a waiver or keeps enforcing a clause?
Report it to the Competition Bureau through its online complaint form. Empire must also file a sworn affidavit with the Commissioner within 90 days and every year after, listing each removal request and how it was handled, so a refusal is on the record. Because the agreement is registered with the Tribunal, a breach can be taken back before it rather than argued from scratch.

Is there a limit on how long a grocer’s exclusivity clause can reasonably run?
The Bureau’s June 2025 guidance sets no fixed term. It says a competitor property control should last only as long as needed to protect the incentive to enter or invest, cover the smallest area necessary and restrict no more products than necessary. Decades-long exclusives covering an entire plaza are the kind it questions.


This is independent editorial analysis by IHR Magazine and is not legal advice. Retailers considering a lease or a waiver request should have the consent agreement, the anchor’s lease and the title record reviewed by a real estate lawyer. Facts are current to September 23, 2026.


Pycnogenol® and the New Brain-Health Shopper: What the Research Shows at Every Life Stage

0
A university student, a professional woman, a retired woman and a father browsing the supplement shelves of a Canadian natural health store

Cognitive health used to be a seniors’ category. Today students, working professionals, older adults and parents are all shopping for it, and Pycnogenol® has published research that speaks to each of them.

A university student, a professional woman, a retired woman and a father browsing the supplement shelves of a Canadian natural health store
Students, working professionals, older adults and parents now all shop the brain-health shelf.

Spend an afternoon in almost any natural health store this fall and you will see brain-health shoppers of every age. A university student is stocking up before midterms. A manager in her mid-forties wants something for the afternoon slump. A retiree hopes to stay as sharp as the people she plays bridge with, and a father has questions about his son’s focus at school. A few years ago, the retiree would probably have been the only one in that aisle. Most stores still serve these customers with different products in different parts of the store.

For brands, a wider customer base is good news, but only for ingredients that have research at more than one stage of life. On September 23, Horphag Research outlined the cognitive research behind Pycnogenol®, its standardized French maritime pine bark extract, with published studies in children, students, working professionals and older adults. Horphag says the extract has been studied in more than 160 clinical trials across all areas of health. For retailers, the appeal is practical. A single, well-documented ingredient can earn a place in more than one section of the store, and staff can talk about it with confidence wherever a customer comes across it.

Life stage What the research looked at Where this customer shops How the store can respond
Children Children with ADHD, compared with methylphenidate and placebo over ten weeks At the counter, usually a parent with a question Refer to the pharmacist or family doctor, with the study on hand
Students Healthy students aged 18 to 27 over eight weeks Exam season, energy and focus Staff knowledge and a seasonal feature
Working professionals Healthy adults aged 35 to 55 with high oxidative stress over twelve weeks Stress, energy and antioxidants Staff knowledge and a second shelf location
Older adults Healthy adults aged 60 to 85 in a double-blind, placebo-controlled trial over three months Healthy aging The main shelf location and the core staff message

Older adults: the strongest place to start

The most rigorous of the four studies was carried out at Swinburne University of Technology in Australia and published in the Journal of Psychopharmacology in 2008. Researchers recruited 101 healthy adults between 60 and 85 and matched them in pairs by age, sex, body mass, diet and intelligence. Half took 150 mg of Pycnogenol® daily for three months while the other half took a placebo. Neither the participants nor the researchers knew who was getting which.

By the end of the study, the Pycnogenol group had improved significantly on memory tasks, particularly spatial and numeric working memory. Their blood work also showed lower levels of F2-isoprostanes, a marker of oxidative damage, which fits with the antioxidant activity Horphag describes. This is the study staff should know best. The participants were healthy, the trial was blinded, and the researchers measured a change in the blood as well as on the tests. A customer in her sixties will usually respond better to who was studied and what they found than to a word like “supports” on a shelf-talker.

Students and working professionals: where the category is growing

A professional woman in her forties reading a supplement bottle in the stress and energy section of a health store
Working professionals are already shopping the stress, energy and antioxidant shelves.

These two groups are where cognitive health is growing fastest, and where many stores have yet to find the right way in.

In an eight-week observational study published in Panminerva Medica in 2011, 53 healthy students aged 18 to 27 who took Pycnogenol® scored better than a comparison group on tests of sustained attention, memory and executive function. Their average exam marks were 7.6 per cent higher, and they failed fewer exams. A twelve-week study of healthy professionals aged 35 to 55, published in the Journal of Neurosurgical Sciences in 2014, reported gains in attention, memory, executive function and mood, as well as better scores on everyday work tasks. Plasma free radicals in the Pycnogenol group dropped by a median of 30.4 per cent.

Neither study used a placebo. Both compared people taking the extract with similar people who were not, so they work best as supporting evidence next to the older-adult trial. What they give a retailer is a broader audience. The same product can now be part of a conversation with a customer in her forties as well as one in her sixties.

Dr. Fred Pescatore, a physician and author, made the same point in Horphag’s announcement. “People often don’t start thinking seriously about cognitive health until they’re older, but focus, memory and mental stamina matter much earlier in life,” he said.

Children: a conversation for the pharmacist

A pharmacist in a white coat talking with a mother at a pharmacy consultation counter, with a printed study on the counter
When a parent asks about a child’s attention, the pharmacist is the right person to take the question.

The research in children shows where scientific interest is heading, and it needs the most care in store. In a ten-week, double-blind randomized trial at the University of Antwerp, published in the Journal of Functional Foods in 2022, 88 children with ADHD were given Pycnogenol®, methylphenidate or a placebo. Teachers reported significant improvement in overall ADHD symptoms, and in hyperactivity and impulsivity, among the children taking Pycnogenol compared with placebo. Side effects were reported far more often with methylphenidate.

Some parents will have read about this study before they walk in. Because ADHD is a diagnosed condition, the question belongs with the pharmacist or the child’s doctor. Having the reference printed and ready, and offering to make the introduction, shows the parent that the store is taking the question seriously. It is also a good reason for the pharmacist and front-shop staff to agree ahead of time on how they will handle it.

What the shelf can say

Talking about research and printing claims are two different things. In Canada, anything on a sign or shelf-talker has to match the product’s licence. Licensed Pycnogenol® products carry specific approved wording, including relief of perimenopausal symptoms such as poor concentration and focus. In practice, staff can describe what the studies found and who took part, while printed material sticks to the licence.

Questions to ask your Pycnogenol® representative

  1. Which daily dose did each cognitive study use, and how do the directions on our products compare? The older-adult and professional studies both used 150 mg a day, which helps staff answer questions about serving size.
  2. Which licensed claims does each of our Pycnogenol products carry? If a product sits in more than one section of the store, the signage in each spot needs to match what is on that box.
  3. Is there point-of-sale material that summarizes the older-adult trial in approved language? A short card saves stores from writing their own and keeps the description consistent.

Over the next few years, more brands are likely to launch cognitive products aimed at specific life stages, from formats for children to blends for adults over 60. The ingredients that hold their place in those lines will be the ones with research at each stage and licences to match. Retailers who sort out shelf placement and staff training now will be ready when those products arrive.

Frequently asked questions

How long should a customer take Pycnogenol® before judging the results?
The older-adult trial assessed participants every month, not just at the end. In the children’s trial, methylphenidate showed results by week five, while the teacher-rated effects of Pycnogenol built up later in the ten weeks. Canadian labels advise speaking with a practitioner about use beyond three months, which is a natural time for a follow-up conversation.

What do Canadian dosing directions say?
Licensed Canadian 100 mg products direct one capsule a day for antioxidant, inflammation-marker and knee osteoarthritis uses, and one capsule twice a day for perimenopause symptoms. Directions vary by product and licence, so staff should check the specific box.

Where does Pycnogenol come from?
It is extracted from the bark of French maritime pine trees grown in managed forests in the Landes region of southwest France. It is standardized to a consistent profile of procyanidins, bioflavonoids and phenolic acids, which is why the research on Pycnogenol applies to Pycnogenol specifically and not to generic pine bark extracts.


Retailers should confirm each product’s NPN and licensed claim wording before making signage or marketing decisions.

Sources: Horphag Research, “Pycnogenol® Offers Clinically Backed Cognitive Support Across Generations,” GlobeNewswire, September 23, 2026. Weyns A-S et al., Journal of Functional Foods, 2022. Luzzi R et al., Panminerva Medica 2011;53(3 Suppl 1):75-82. Belcaro G et al., Journal of Neurosurgical Sciences 2014;58(4):239-48. Ryan J et al., Journal of Psychopharmacology 2008;22(5):553-62, doi:10.1177/0269881108091584. Natural Factors Canada, Pycnogenol 100 mg product listing.

What a networked order actually pays an independent retailer

0
What a networked order actually pays an independent retailer

When an IHR order is fulfilled by a store that did not sell it, the retailer margin splits 60/40: 60% to the store that packs and ships, 40% to the store that took the order. That single rule is what makes a shared fulfillment network work in practice, and it is the part of IHR that has never been spelled out in public.

The network idea itself is not new, and we have written about it before: independent shelves pooled into one catalogue, orders routed to whoever is nearest with stock. What retailers keep asking, and what no explainer has answered, is simpler and more practical. When that order lands, who gets paid, how much, and when.

Walk one order through the money

A customer in Sherbrooke buys a $60 bottle from a store in Montreal. The Montreal shop does not have it. A shop in Magog does.

  1. The vendor’s wholesale cost comes off the top. That money is the brand’s and is never in play.
  2. IHR’s platform fee comes off the sale. On the entry plan that is 5%.
  3. What is left is the retailer margin, and it is the only pool the two stores divide.
  4. Magog packed and shipped, so Magog takes 60% of that margin. Montreal made the sale and takes 40%.
  5. Stripe Connect settles each share directly to each bank account. Neither store invoices the other.

If Montreal had the bottle on its own shelf, it would have shipped it and kept the whole margin. The split only exists because two different businesses did two different jobs.

Who did what Share of retailer margin
Packed and shipped the order 60%
Took the order on its own site 40%
Did both 100%

Who absorbs the shipping?

The customer pays shipping by default. The exception matters more than the rule: if a store advertises free shipping, that store eats the cost, and only that store. The shop that fulfilled the order is never billed for a promotion it did not run.

This is the first question most owners ask, and it is deliberate design. A fulfilling store’s economics cannot be quietly degraded by another retailer’s marketing decision, or nobody would agree to fulfil anything.

What happens on a refund?

IHR does not impose a return policy. Each store sets its own window, its own restocking fee and its own position on who pays return shipping, and that policy is what governs the refund.

Behind the customer-facing part, three things happen automatically:

  • The vendor and retailer shares are clawed back, so no party keeps money on a sale that reversed.
  • The IHR commission is not refunded and is excluded from the customer’s refund amount.
  • The return cost follows the selling store, not the fulfilling one, mirroring the shipping rule.

What does the platform actually charge?

Earlier coverage of the plugin described it as free during beta. That was accurate then and is worth correcting now that the plans are set. IHR earns a percentage of fulfilled sales rather than a per-seat licence, so the entry plan carries unlimited products and full network access with no monthly fee, and the paid tiers buy a lower rate plus growth tooling.

Plan Fee per fulfilled sale Seats Adds
Starter 5% 3 Unlimited products, full network access, MAP enforcement
Growth 4% 5 AI ads, automations, subscriptions, SEO tooling, funnels
Professional 3% 12 Multi-location, API access, priority routing
Enterprise Negotiated 25+ White-label, ERP integration, dedicated support

The fee is charged on sales that are fulfilled, not on listings, traffic or catalogue size. A store that lists ten thousand network products and sells none of them pays nothing.

Who decides where an order ships from?

The retailer does, not the network. Each store picks a fulfillment strategy and the routing engine works inside that choice: the full IHR network, up to five of the store’s own distributors, a third-party logistics provider, a corporate centre for chains, or an IHR distribution centre. If the chosen fulfiller is out of stock the order backorders and alerts the store, unless network fallback is switched on.

Within whatever pool the store has authorised, the engine scores each node on proximity, shipping cost, stock depth, rating and node type, then reserves the unit atomically so two orders can never claim the same last bottle.

Where does the brand sit in this?

Vendors are not passive suppliers here. They set minimum advertised pricing, authorise which retailers may list their catalogue, define territories, and receive alerts when a price floor is broken. Where no retailer in the network holds an item, the vendor can ship it directly and stay inside the network rather than watching the sale leave it. In that case the originating retailer receives a reduced share, because it made the sale but did not fulfil it.

That is the trade brands are being offered: open distribution without losing governance over price and channel.

What about compliance?

The network operates under Canadian rules rather than adapting American ones. PIPEDA and Quebec’s Law 25 govern the handling of customer data, CASL governs the marketing side, and natural health product disclaimers are built into the flows rather than left to each retailer to remember. Every order, split, payout and refund is recorded, which is what makes a multi-party split reconcilable at year end.

https://ihrplugin.com

Frequently asked

How much does a store earn for fulfilling another store’s order?
60% of the retail margin on that order. The store that took the order keeps the remaining 40%.

When does the money arrive?
Each party’s share settles to their own bank account through Stripe Connect as part of the transaction. There is no inter-store invoicing and no month-end reconciliation between retailers.

If I offer free shipping, does the fulfilling store pay for it?
No. Only the store that advertised free shipping absorbs that cost.

Is the IHR commission refunded when a customer returns an order?
No. The commission is retained and excluded from the customer’s refund, while the vendor and retailer shares are clawed back automatically.

Do I have to let the network ship my orders?
No. A store can fulfil from its own distributors, a 3PL, a corporate centre or an IHR distribution centre instead, and decide separately whether the network acts as a fallback.

Does joining mean rebuilding my website?
No. IHR connects to the store already in place, with native connections for Shopify, WooCommerce, Wix, BigCommerce and Amazon, and an embed widget for anything else.

Ubiquinol Just Won a Healthspan Award. Here Is How to Use It on a Canadian Shelf

0
A health store associate showing a customer an open jar of golden CoQ10 supplement powder at a wooden wellness shelf

A health store associate showing a customer an open jar of golden CoQ10 supplement powder at a wooden wellness shelf

A customer in her late fifties stops at the CoQ10 bay with her phone out. An AI assistant has just told her about mitochondria, cellular energy and something called healthspan, and it mentioned ubiquinol by name. Her question is simple: which of these bottles should she buy, and is the expensive one worth it?

More shoppers will arrive with that question this fall. Kaneka Ubiquinol has been named Healthspan Ingredient of the Year at the NutraIngredients-Asia Awards, and the recognition gives Canadian health retailers a timely reason to talk about CoQ10. The catch is that a Canadian label can only promise what ordinary CoQ10 already promises, while the ubiquinol form costs about two and a half times as much per milligram. Stores that turn this award into sales will be the ones whose staff can tell the story in the words Health Canada allows and explain the price difference honestly.

What the award is worth at the counter

The ceremony took place in Bangkok on September 2, with a record 256 entries across the program. It is the ingredient’s third consecutive recognition from these awards, following a healthy ageing win in 2024 and a women’s health shortlisting in 2025. Kaneka counts it as its seventh international honour. According to publisher Gary Scattergood, the judges were impressed by the scientific evidence behind ubiquinol and by “significant evidence of commercial success across the region.”

For a buyer, that combination is the useful part. An independent panel reviewed both the research file and the sales record, which makes ubiquinol a lower-risk listing and gives staff a credible reply when a customer wonders whether it is a passing fad.

Kaneka is also using the moment to promote “mitoceuticals,” its term for nutraceuticals formulated to support mitochondrial function. Ubiquinol, the reduced form of coenzyme Q10 that cells use in energy production, sits at the centre of that idea. To make the point, the company’s release cites an eLife study estimating more than 5,000 mitochondria in every heart cell. Kaneka describes itself as the sole global manufacturer of ubiquinol. Even so, a March 2026 trial in Clinical Pharmacology in Drug Development tested a ubiquinol cocrystal from a Chinese developer. Suppliers should be able to say whose raw material is in their product, since research on one source does not automatically transfer to another.

The raw material itself usually travels as a powder. Alongside its standard ingredient, Kaneka supplies an air-stable ubiquinol powder, Kaneka Q30, which it says suits capsules, stick packs, powdered beverages and nutrition bars, and its product developers work in formats from gummies to fast-dissolving powders. For the shelf, that means one ingredient can arrive in several forms, and the format a customer prefers is as much a reason to choose a product as the ingredient inside it.

Demand at home is real. A Global Burden of Disease analysis published this summer in The Lancet Public Health measured the gap between lifespan and years lived in good health. Worldwide, it reached 10.7 years in 2023, up from 8.8 in 1990. Canada’s gap was wider still, at 13.7 years. People facing that prospect are looking for ways to stay well for longer, and many of them are already in the aisle.

Telling the story the Canadian way

None of the award’s vocabulary appears on a Canadian label. Health Canada’s Coenzyme Q10 monograph, revised on January 31, 2025, names ubiquinone-10 and allows three kinds of claim: support for cardiovascular health, antioxidant protection, and fewer migraine headaches when taken preventively. Ubiquinol products are licensed here too, and they use the same language. Natural Factors’ Ubiquinol Active CoQ10, which contains Kaneka’s ingredient, says it “helps support cardiovascular health” and “provides antioxidants for the maintenance of good health.”

Those words matter beyond the bottle, because Canada’s consumer advertising guidelines for health products treat in-store promotional material as advertising. A retailer may paraphrase a product’s approved claims but cannot go beyond them. Awards and seals from recognized organizations are acceptable as long as the claims beside them stay within the licence and the advertiser can document the recognition. A shelf-talker reading “Award-winning Kaneka ubiquinol. Helps support cardiovascular health and provides antioxidants” meets that standard, provided a copy of the award announcement is kept on file. “Cellular energy for healthy ageing” would not.

One line from Kaneka’s release should stay off the shop floor entirely. The company describes ubiquinol as supporting health “from preconception to healthy ageing,” yet every CoQ10 product sold under the monograph must tell pregnant and breastfeeding customers to speak with a practitioner first. Ubiquinol therefore belongs nowhere near a fertility or prenatal display.

Which bottle she should take home

Back at the bay, the price difference is the first thing she notices. Here is how it looked at Nutrition House’s Canadian online store on September 16:

Product Form Price Cost per 100 mg
Natural Factors, 100 mg, 120 softgels Ubiquinol $74.95 about 62 cents
Preferred Nutrition, 150 mg, 180 softgels Ubiquinone $61.97 about 23 cents
NOW, 400 mg, 60 softgels Ubiquinone $62.29 about 26 cents

Absorption accounts for part of that gap. In the comparison most often cited, a 2014 study by Peter and Alena Langsjoen, 12 healthy volunteers took 200 mg a day of each form for four weeks. Blood CoQ10 rose from 0.9 to 2.5 µg/mL with ubiquinone and from 0.9 to 4.3 µg/mL with ubiquinol, a gain slightly more than twice as large.

At that dose, ubiquinol costs about $1.25 a day and raised blood levels by 3.4 units, or 37 cents per unit. Ubiquinone costs about 46 cents a day for a rise of 1.6 units, which works out to 29 cents per unit. These figures are illustrative, drawn from one retailer’s prices and one small open-label study with no placebo group, and they assume absorption behaves the same way at other doses. A blood level is also not a health outcome.

What emerges is a natural two-tier shelf. Ubiquinone is the value option and still delivers blood CoQ10 slightly more cheaply. Ubiquinol is the convenience option, reaching a higher level from fewer servings, which appeals to customers who dislike taking several capsules a day. Showing cost per 100 mg on both tags lets her make that choice herself, and those who trade up bring a larger ticket and more margin dollars without feeling pushed. The 2026 cocrystal study also reported roughly double the exposure, but its results apply only to that formulation and should not be quoted for other brands.

Beyond the CoQ10 bay

The Lancet study also shows where the rest of her basket could come from. Musculoskeletal disorders, depression and anxiety, hearing loss and falls account for more than half of the world’s unhealthy years, and none of them is a CoQ10 claim. A healthy-ageing destination built on that evidence groups products by approved need-states such as joints, bone, sleep, mood and heart. CoQ10 sits in the heart section beside other cardiovascular products, many omega-3 formulas among them. The neighbouring sections give staff an easy next conversation once the first purchase is settled. An award that brought one customer to one bottle can end in a basket that covers several of the years she hopes to keep healthy.

Frequently Asked Questions

Which other cautions must a CoQ10 product carry in Canada?
Beyond the pregnancy and breastfeeding warning, every product under Health Canada’s January 2025 monograph must advise consulting a practitioner before use with blood pressure medication. Products supplying more than 100 mg a day must also caution people taking blood thinners, a threshold most ubiquinol softgels pass at their upper recommended dose.

What dose does Health Canada allow for the CoQ10 migraine claim?
Adults may take 150 to 300 mg a day preventively, and the label must direct use for at least three months before judging the effect. The cardiovascular claim covers 30 to 300 mg a day, and antioxidant claims cap at 300 mg. A 100 mg softgel therefore needs at least two daily servings to carry the migraine claim.

How can a retailer check exactly what a CoQ10 product is allowed to claim?
Search the product’s eight-digit NPN in Health Canada’s Licensed Natural Health Products Database, which shows the recommended use, dose and cautions on the licence. Natural Factors Ubiquinol CoQ10 100 mg, for example, is listed by Canadian retailers under NPN 80028985. Signage and website copy should follow that record rather than supplier sales sheets.

Do women and men face the same healthspan gap?
No. The Lancet Public Health analysis found that women spend an average of 12.1 years in poor health, compared with 9.3 years for men, despite living longer. For a healthy-ageing set, that makes women over 50 the larger share of demand, which argues for giving bone, joint and mood products as much space as heart health.

This is independent editorial analysis by IHR Magazine. It references Kaneka Ubiquinol as one example of the mitochondrial health trend and is not an endorsement of any product or supplier. Retailers should verify each product’s NPN and licensed claims before merchandising. Prices were recorded on September 16, 2026, and will change.