All In Nutritionals
Home Blog Page 3

Canada’s Natural Health Product Rules Are Changing in 2026: What Retailers and Brands Need to Know

1
Compliance and regulation concept representing Canada's 2026 natural health product rules — IHR Magazine.

Two decades of light-touch oversight are ending. Here’s the intelligence retailers and brands need before the shelf resets.

It started with an audit.

In the spring of 2021, Canada’s federal auditors pulled back the curtain on the natural health products industry and found a system running largely on trust. Health Canada was approving products on paper but rarely inspecting the sites that manufactured them. When auditors examined a sample of licensed products, 88% carried potentially misleading claims. And on the rare occasion a genuinely unsafe product reached the shelf, the regulator had no power to pull it — it could not order a recall.

That report lit a fuse. Five years on, its findings have hardened into the most consequential regulatory overhaul the Canadian supplement industry has seen since the Natural Health Products Regulations first took effect in 2004. For retailers and brands, 2026 is the year it stops being a policy debate in Ottawa and starts rearranging what sits on the shelf.

The stakes are not small. Roughly 77% of Canadians reach for natural health products regularly, and the market they support is worth about $2.8 billion and climbing near 7.6% a year. A category that large, that trusted, and that lightly policed was never going to stay untouched once the auditors had spoken. Three changes now carry the response — and each one lands on a different line of the balance sheet.

Teeth: how $5 million changes the math

The first and bluntest change is enforcement. Folded into the federal government’s 2023 budget bill, Bill C-47 stripped natural health products of their long-standing exemption from the Protecting Canadians from Unsafe Drugs Act — Vanessa’s Law. Much of the industry, by its own account, was caught off guard.

The effect is a regulator with real leverage for the first time. Health Canada can now order a recall, compel a company to change a label or its packaging, demand internal records, and levy penalties for serious violations of up to $5 million. Under the old regime, the ceiling sat in the low thousands.

That is not a tougher edition of the same rulebook. It is a different order of risk. For a brand that once filed a borderline claim under “cost of doing business,” the downside just grew by three orders of magnitude — and moved from the back office to the risk register.

The label becomes the battleground

If Vanessa’s Law is the stick, the new labelling regime is the daily grind. Since 21 June 2025, natural health products must carry a standardized “Product Facts” table — plain-language, bilingual, set in a minimum type size — modelled on the panels Canadians already read on over-the-counter medicines. It is a direct answer to that 88% misleading-claims finding: make every label legible, comparable, and honest.

Products licensed before that date get a three-year runway, so the whole market must comply by 21 June 2028. On the surface it reads like a design refresh. On the ground it is a capital decision taken one SKU at a time. Relabelling costs real money, and for a slow mover the numbers often will not justify the reprint. The likeliest casualties are the small, differentiated lines — the artisanal tinctures and single-origin botanicals that give an independent store its character and, frequently, its fattest margins. Many of those products won’t be reformulated or redesigned. They’ll simply disappear.

Who pays to be regulated

The third change still hangs over the industry: cost recovery. Health Canada has proposed billing the sector for the cost of overseeing it — a $317 annual right-to-sell fee for every natural product number, a site licence fee near $4,784, and pre-market evaluation fees from roughly $1,100 to more than $58,000, softened by remissions for qualifying small businesses.

For now the plan is paused, parked while the wider modernization framework is settled. But paused is not repealed. When the fees return — and Health Canada has signalled they will — they reprice a company’s entire catalogue at a stroke. A flat per-product charge is a rounding error for a national brand spreading it across millions in sales; for a small supplier with a long tail of niche NPNs, it can push a whole shelf underwater overnight. The operators running that math today are the ones who will still be trading when the invoice arrives.

The industry pushes back

None of this has happened quietly. The Canadian Health Food Association’s “Save Our Supplements” campaign has become one of the most visible advocacy pushes the sector has ever mounted — more than 100,000 petition signatures and over a million postcards sent to MPs, Health Canada and the Prime Minister’s Office. Its argument isn’t that the industry opposes safety, but that the cost and complexity of the new regime will thin choice and lift prices for the 77% of Canadians who count on these products.

That tension — consumer protection on one side, access and affordability on the other — is the real story beneath the regulations, and it is far from resolved. The pause on cost recovery is evidence the pressure is landing. Retailers and brands who read that politics will forecast the next 18 months far more accurately than those treating the rules as fixed.

What it means on the floor

Strip away the policy language and the message for retailers is plain: your shelf sits downstream of all of it. Recall and liability exposure now travel with the products you carry, which turns supplier due diligence into part of buying rather than a formality — asking for compliance attestations is no longer overcautious. The 2028 deadline and the eventual return of fees will thin the supplier base from the bottom up, and the products most exposed are exactly the high-margin, hard-to-replace lines you can least afford to lose. The retailers who come out ahead will flag their at-risk SKUs early and start the supplier conversations now, well before the delisting notices land.

For brands and their marketers, the calculus has flipped. Compliance used to be overhead; in this market it is a moat. A clean regulatory file, genuine substantiation behind every claim, and demonstrable retail velocity are increasingly what buyers reward and acquirers pay up for. Marketing teams carry the sharpest new exposure of all: under Vanessa’s Law, an unsupported claim is no longer a ticket but a seven-figure liability. The discipline that wins is claims that sell and survive an audit — every assertion mapped to its evidence before it reaches a label, a landing page, or a shelf-talker.

The year to get ahead of it

For all the unease, none of this shrinks the prize. Canadians are buying more natural health products, not fewer, and demand across supplements, functional foods and condition-specific formulas keeps rising. What’s changing is the barrier to entry — and, with it, who gets to compete. Tighter rules reward scale, discipline and evidence; they punish the casual operator. That is uncomfortable for parts of the industry and a real advantage for the businesses ready to meet the moment.

The rules arriving through 2026 aren’t a storm to wait out. They’re a filter. The retailers and brands treating this as a planning year — auditing assortments, pressure-testing claims, modelling the cost of what’s coming — will find the reshuffle tilting their way. The rest will spend 2028 reacting.

Frequently asked questions

Why is Canada changing its natural health product rules?

A 2021 federal audit found Health Canada’s oversight fell short: it rarely inspected manufacturing sites, 88% of reviewed products carried potentially misleading claims, and the regulator had no power to order a recall. The 2026 changes are the government’s response to those findings.

Does Vanessa’s Law apply to natural health products in Canada?

Yes. Bill C-47 (Royal Assent, June 2023) removed the NHP exemption, giving Health Canada authority to order recalls, mandate label and packaging changes, compel records, and impose penalties of up to $5 million for serious non-compliance.

When do the new NHP labelling rules take effect?

The improved-labelling provisions came into force on 21 June 2025. Products licensed before that date have a three-year transition, so all NHP labels must comply by 21 June 2028.

What are the proposed NHP cost-recovery fees?

The proposed schedule includes a $317 annual right-to-sell fee per NPN, a site licence fee of about $4,784, and pre-market evaluation fees up to $58,332, with remissions for qualifying small businesses. Implementation is currently paused.

What should retailers do now?

Ask suppliers how they are handling the 2025 labelling requirements and Vanessa’s Law compliance, identify at-risk SKUs in your assortment, and plan changes ahead of the 2028 deadline.
Who Ships Your Orders? IHR Plugin’s New Fulfilment Strategy Selector Puts the Answer Back in Retailers’ Hands

0

Ahead of its September 2026 launch, the decentralized health commerce platform, now in beta, previews a feature that lets every store, independent or chain, choose exactly who fulfils its online orders, from its own distributors to a corporate logistics centre, without giving up the network’s safety net.

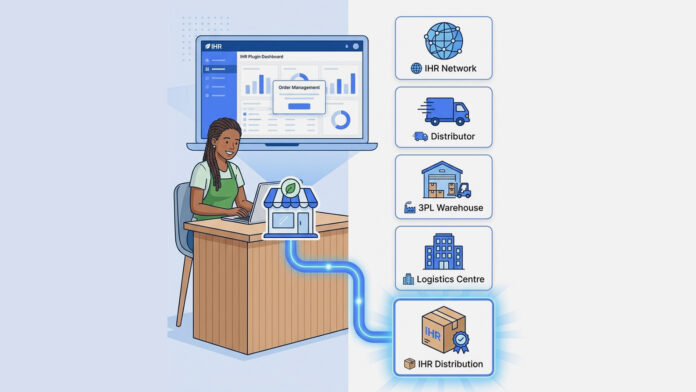
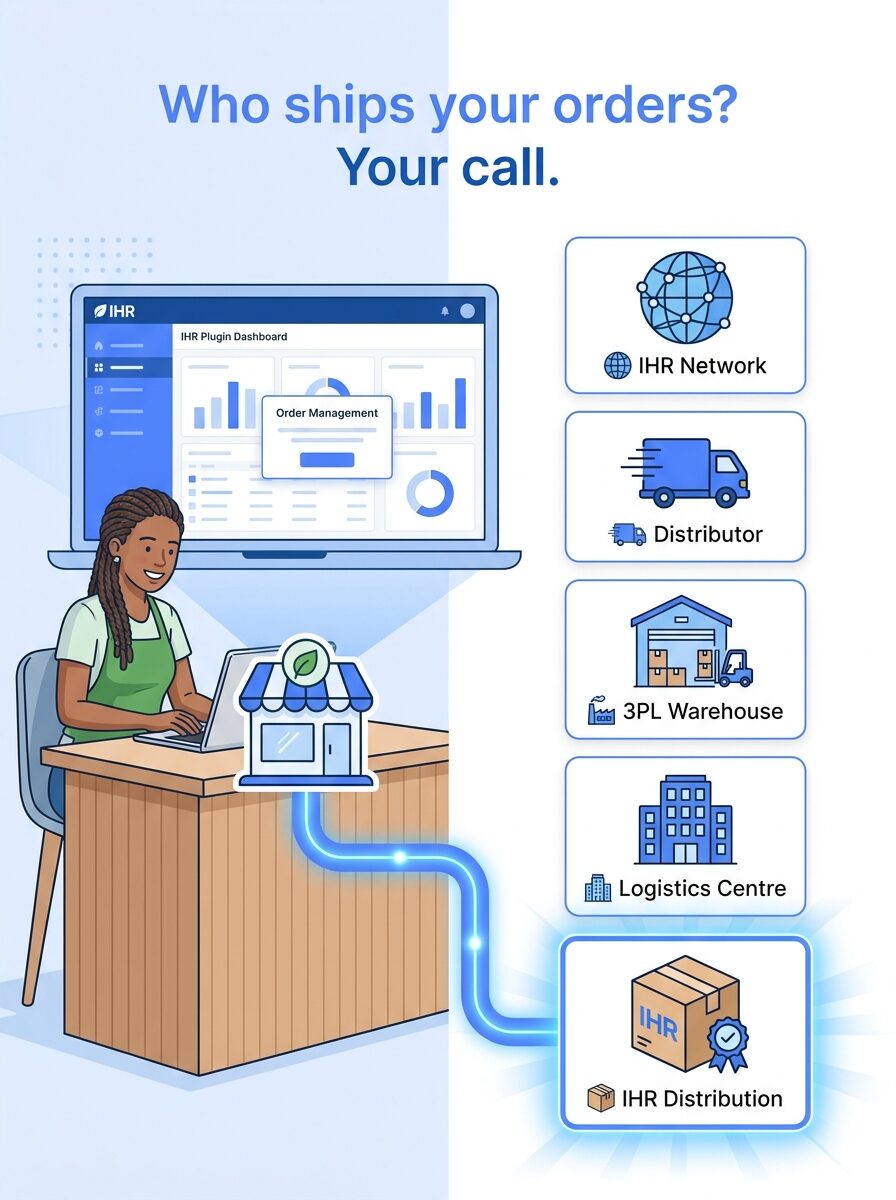
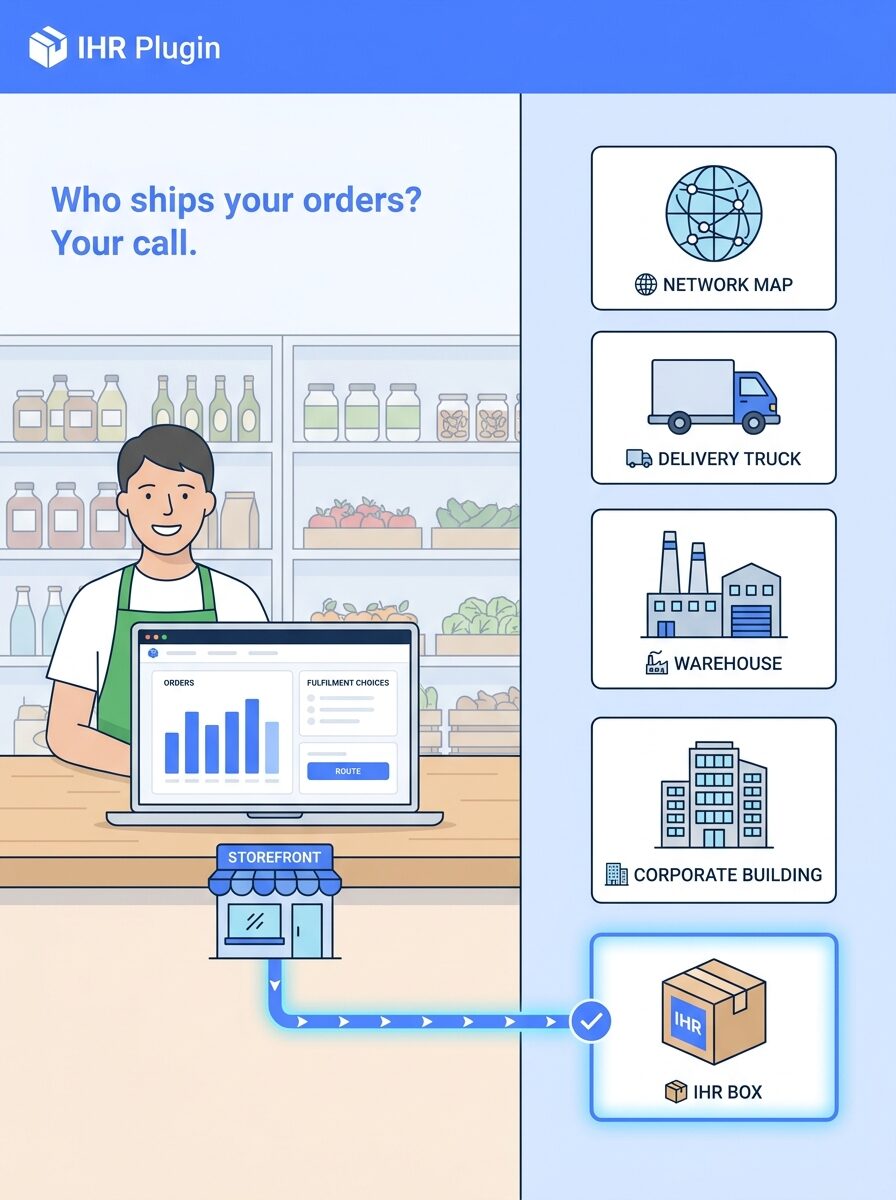
What is the fulfilment-strategy selector? It is a new IHR Plugin setting that lets each health food store choose who fulfils its online orders: the IHR network, up to five of its own distributors, a 3PL warehouse, a corporate logistics centre, or an IHR distribution centre—and enforces that choice across manual, Shopify, and WooCommerce order routing.

Key takeaways

  • Retailers pick one of five fulfilment strategies; the IHR network remains the zero-setup default.

  • Every entered location becomes a routing node, and all order channels honour the choice — orders ship only from the chosen fulfiller(s).

  • Out-of-stock orders backorder and alert the store by default; an optional per-store toggle allows IHR network fallback.

  • The IHR Plugin is free, currently in beta, and launches in September 2026.

The IHR Plugin’s core promise to natural health food retailers is simple: connect your store to a decentralized network of inventory, and stop worrying about who ships what. Every participating retailer becomes a micro-warehouse, orders route to the closest available stock, and stores can offer an “infinite shelf” without carrying the inventory themselves.

That model works for many shops. But as the platform’s beta program has drawn in multi-store groups, banner chains, and retailers with long-standing distributor relationships, one piece of feedback keeps coming back: not every store wants the network to decide where its orders ship from. Some have negotiated distributor terms they need to honour. Some chains route everything through their own logistics centre. Some retailers simply want their trusted 3PL to keep doing the job.

The fulfilment-strategy selector — one of the features the IHR Plugin is previewing ahead of launch, answers that directly. It turns what would otherwise be a fixed, network-first routing model into a choice the retailer makes and the platform enforces.

Five Ways to Fulfil

The selector presents each store with five clickable fulfilment strategies:

• IHR Plugin network. The default, and the zero-setup option. Orders route through the decentralized network of participating retailers, vendors, and distribution points. Stores that are happy with network fulfilment don’t need to touch anything.

• My distributor(s). For stores with established wholesale relationships, this option lets them register one to five of their own distributors, entering each location individually. Orders then flow to those distributors and nowhere else.

• 3PL warehouse. Retailers who have outsourced logistics to a third-party fulfilment provider can point the platform at that warehouse and keep their existing operation intact.

• Corporate logistics centre. Built for groups and chains. A banner with fifteen storefronts can designate a single corporate centre, and every store in the group ships from it , one node, one inventory pool, one set of shipping rules.

• IHR distribution centre. Stores that want dedicated fulfilment without running their own logistics can route orders through an IHR distribution centre.

Each location a retailer enters becomes a routing node in the platform. That matters more than it sounds: the selector isn’t a preference that gets consulted sometimes. Every order-routing path the platform supports, manual orders, Shopify storefronts, WooCommerce stores, now honours the store’s choice. If a retailer picks its two distributors, orders go to those two distributors, period. The network doesn’t quietly step in.

The Out-of-Stock Question

Any retailer who has run a dropship or distributor program knows where this design gets tested: what happens when the chosen fulfiller doesn’t have the product?

The IHR Plugin’s answer is deliberately conservative. By default, the order backorders and the store is alerted. Nothing ships from an unexpected source, no surprise invoice arrives from a fulfiller the retailer never chose, and the store decides how to resolve it wait for restock, contact the distributor, or cancel and refund.

For stores that would rather never make a customer wait, there’s a per-store toggle: allow IHR network fallback. Flip it on, and an out-of-stock order at the chosen fulfiller automatically falls back to the IHR Plugin network, shipping from the nearest participating node instead. It’s the best of both worlds for retailers who want distributor-first routing with the network as insurance, and it stays off unless the store turns it on.

That default-off choice is worth noting. Plenty of platforms would have made fallback automatic and called it a feature. Making it opt-in signals that the IHR Plugin treats fulfilment relationships as commercial commitments, not just logistics plumbing.

Why This Matters for the Trade

Distributor relationships survive the move online. The biggest quiet objection to network-based fulfilment has always been channel conflict. A store that has spent a decade building terms, rebates, and credit with its regional distributor doesn’t want an e-commerce plugin rerouting that volume elsewhere. The selector lets that store digitize without disintermediating anyone.

Chains get the control they’re used to. Multi-store groups typically centralize purchasing and logistics for good reasons: volume pricing, consistent stock, one receiving operation. The corporate logistics centre option maps the platform onto that reality instead of asking the chain to restructure around the network.

Independents keep the zero-effort path. Nothing changes for the single store that joined precisely because it didn’t want to think about fulfilment. The network remains the default, with no setup required.

Suppliers keep their guardrails. The platform’s brand controls , minimum advertised pricing and supplier control over which retailers carry their goods, apply regardless of which fulfilment strategy a store selects.

The Bigger Picture

The natural health retail channel has spent the past several years squeezed between consumer delivery expectations set by the major e-commerce platforms and the economics of small-format retail. The IHR Plugin’s pitch , decentralized inventory, shared fulfilment, and AI-driven marketing, with a free subscription, is about giving independents the infrastructure to compete.

The fulfilment-strategy selector shows a platform maturing before it even launches. A platform confident enough to let retailers route orders away from its own network is making a bet: that flexibility, not lock-in, is what keeps stores on the platform. For a channel built on independent operators, family-owned chains, and long-memory distributor relationships, that bet reads the room correctly.

In a category where trust is the product, that kind of control is not a small feature. It’s the difference between a platform stores use and a platform stores build on.

Frequently Asked Questions

When does the IHR Plugin launch?
The IHR Plugin is currently in beta and launches in September 2026. Features such as the fulfilment-strategy selector are being previewed ahead of launch.

How much does the IHR Plugin cost?
The subscription is free. Stores connect their storefront and choose a fulfilment strategy without a monthly fee.

Which fulfilment options can a store choose?
Five: the IHR Plugin network (default, zero setup), the store’s own distributors (one to five locations), a 3PL warehouse, a corporate logistics centre for groups and chains, or an IHR distribution centre.

What happens if the chosen fulfiller is out of stock?
By default the order backorders and the store is alerted nothing ships from an unapproved source. Each store can optionally enable an “allow IHR network fallback” toggle so out-of-stock orders ship from the nearest network node instead.

Does the selector work with Shopify and WooCommerce?
Yes. All order routing manual orders, Shopify, and WooCommerce honours the store’s chosen fulfilment strategy.

The IHR Plugin (ihrplugin.com) is a decentralized health commerce platform for natural health retailers, supporting order fulfilment, inventory, earnings, and network management across manual, Shopify, and WooCommerce order channels. Currently in beta, it launches in September 2026.


Acosta Group Creates a Chief Retailer Partnerships Officer Role — What It Signals for Natural Health Retail

0

Acosta Group has named Joe Mueller, a 35-year veteran of Kellanova and Kellogg Company, to the newly created role of Chief Retailer Partnerships Officer. The title itself is the story: a commercial services firm of Acosta Group’s scale rarely builds an executive seat around a function unless it expects that function to drive the next phase of growth.

Acosta Group sits at the centre of commercial execution for a large share of the brands stocked on Canadian and North American shelves, spanning mainstream CPG and the wellness labels increasingly moving into grocery and pharmacy. A dedicated retailer-facing executive seat is a bet on where that growth comes from: closer, better-structured retailer collaboration, not brand-side merchandising alone.

From brand advocacy to retailer partnership

Customer development leaders have traditionally been measured on how well they represent a brand to a retailer. Mueller’s mandate runs the other direction. Reporting to Mark Rahiya, Group President of Omnichannel Sales & Services, he’ll work across Acosta Group’s agency teams to strengthen retailer relationships directly, surface growth opportunities for clients and retail customers alike, and channel marketplace insight back into company strategy.

That’s a bet that retailers want partners who understand category economics and shopper behaviour on their own terms, not another pitch for shelf space. Mueller’s résumé backs it up: at Kellanova and Kellogg, he ran some of the company’s largest customer businesses and built retailer partnerships across channels, putting him on the other side of exactly these conversations for most of his career.

The commercial read for retailers and brands

Independent health food stores, pharmacy retailers, and grocery category managers are managing category resets around GLP-1-adjacent demand, protein reformulation, and gut and cognitive health — often with leaner buying teams than conventional grocery, while suppliers face growing pressure to prove category growth rather than just win distribution.

Read against that backdrop, Acosta Group’s move points to where buyer expectations are headed: more strategic engagement from suppliers pitching category resets, marketplace insight becoming as important as sales presence in winning shelf space, and retailer relationships getting professionalized in ways that will eventually reach specialty retail too, not just big grocery banners.

What to do with this

Expect other commercial services firms and larger manufacturers to formalize retailer-facing roles over the next year. For natural health brands and retailers, the practical move is to start treating retailer relationships as a capability to invest in deliberately — category insight, shopper data, joint planning — rather than something handled account by account as it comes up.

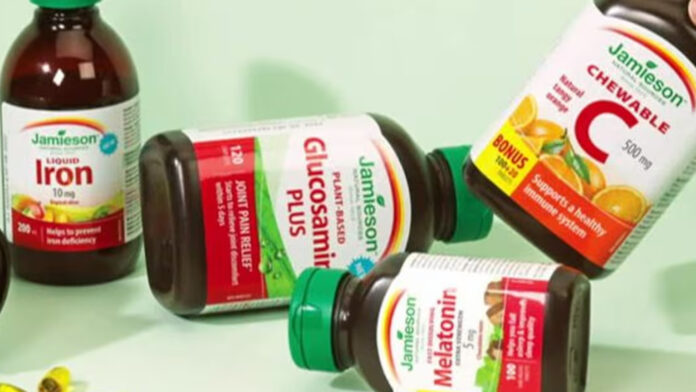
A Buyer Came Knocking at Jamieson. That’s Not the Same as a Sale

0

On June 24, Jamieson Wellness (TSX: JWEL) confirmed it had received an unsolicited proposal to be acquired. Its Board opened a process to enhance shareholder value and is in talks with interested parties, with BMO Capital Markets and Canaccord Genuity advising. The Board added that there is no assurance of a transaction, and that absent one it will continue executing its current plan.

Jamieson did not put itself up for sale. A buyer approached, the Board is obliged to weigh it, and a review is underway with no committed outcome. “Exploring options after an unsolicited bid” and “for sale” are different situations with different odds.

Confirmed versus speculation

Confirmed: a proposal arrived, the Board is reviewing it, other parties are in the conversation, and two banks are engaged. The company has signalled it won’t say more unless disclosure becomes required.

Everything else is open. The buyer, the price, the terms and whether anything closes are all unknown. The widely cited $2.5 billion, drawn from an analyst’s roughly $58.50-a-share estimate on 2026 EBITDA, is a model, not an offer; the stock traded near $36 into the announcement. Worth keeping the company’s statements, analyst math and market hope in separate columns.

Why the inbound matters more than the headline

A company that shops itself is telling you about its own needs. A company fielding an unprompted offer is telling you about the category’s pull, and that’s the version here.

The interest tracks a broader appetite for natural health assets. Private equity has been busy in supplements, drawn to defensive growth and a fragmented field. Church & Dwight is shedding VitaFusion and L’il Critters to Piping Rock; The Vitamin Shoppe changed hands through a PE partnership. GLP-1 adoption, meanwhile, is steering demand toward protein, fibre, hydration and companion products rather than away from supplements. None of that means Jamieson sells. It explains why someone tried.

The retail read

The review puts a question mark over the largest branded block in the Canadian vitamin aisle. A new owner could rationalize SKUs and reset trade terms; continued independence could mean management pushes its strategy harder to justify it. Retailers leaning heavily on one dominant brand are carrying risk worth pricing now: audit your VMS concentration, line up challenger brands that could backfill, and weight suppliers toward the categories actually growing.

The brand read

For everyone else, the takeaway isn’t a multiple, since none is confirmed. It’s that a scaled, distributed, vertically integrated business pulled in capital without asking. The traits that drew the approach, brand equity, multi-market distribution, controlled manufacturing and demand exposure, are the ones likely to draw the next one.

Outlook

Jamieson has gone quiet by design, so expect a holding pattern. A premium deal, a competing bid, and a clean walk-away all remain live. Assume nothing about the result, but don’t ignore what an unprompted, billion-dollar-range approach reveals about appetite for the category. The deal may not happen. The signal already has.

FAQ

Is Jamieson Wellness for sale?
Not in the sense of having put itself on the market. It received an unsolicited proposal and its Board opened a review, including talks with interested parties. The company says there is no assurance of a transaction and will otherwise continue its current plan.

What has the company actually confirmed?
An unsolicited proposal, a Board process to enhance shareholder value, discussions with interested parties, and BMO Capital Markets and Canaccord Genuity as advisors. No buyer, price or terms.

Is the $2.5 billion figure the offer price?
No. It’s an analyst estimate (about $58.50 a share on 2026 EBITDA), not a disclosed offer. The stock traded near $36 into the announcement.

Why does an unsolicited bid matter to the industry?
Unprompted interest in a scaled VMS business signals where capital is looking, even if no deal closes, reflecting active supplement consolidation and GLP-1-driven demand.

What should retailers and brands do now?
Audit concentration in dominant VMS brands, identify challenger options, and weight toward growing demand categories. Brands should note the traits that drew interest: equity, distribution, manufacturing and demand exposure.

Iovate Bets on a Scientist-Operator: What Raza Bashir’s CEO Appointment Signals for Active Nutrition Retail

0

The maker of MuscleTech and Hydroxycut promotes its Chief Innovation Officer to the top job — a move that reads less like a routine succession and more like a strategic reset toward science-first, consumer-led growth.

Iovate Health Sciences International has named Raza Bashir its new Chief Executive Officer, effective immediately, elevating the company’s former Chief Innovation Officer to lead one of the most recognizable portfolios in global active nutrition. For retailers, brand managers, and category buyers across the natural health and sports nutrition space, the headline matters less than the signal underneath it: a science-trained operator now sits at the helm of a company whose brands — MuscleTech®, Hydroxycut®, Six Star Pro Nutrition®, and Purely Inspired® — occupy premium shelf real estate in supplement aisles from independent health food stores to national grocery and pharmacy chains.

The appointment is being framed internally as a return to Iovate’s roots as a research-first, entrepreneurial innovator. That framing is worth taking seriously, because it tells the trade exactly where this Oakville, Ontario-based manufacturer intends to compete next — and where the commercial opportunity sits for the partners who stock and sell its products.

A leadership choice that doubles as a category strategy

Most CEO announcements are about the person. This one is about the playbook. Bashir spent close to two decades inside Iovate, most recently translating clinical science into consumer-ready formulations across the company’s flagship brands. Promoting the innovation lead — rather than importing an outside operator or a pure financial steward — is a deliberate statement that product science, not just distribution muscle, will drive the company’s next phase.

For the industry, that is a meaningful tell. Active nutrition is in the middle of a credibility reset. Consumers are more sceptical, more ingredient-literate, and more willing to interrogate claims than at any point in the category’s history. Retailers feel this at the shelf every day: shoppers want efficacy they can verify, not hype they have to trust. A manufacturer that puts a scientist-operator in the CEO chair is positioning itself for a market where evidence is the differentiator and the brands that can defend their formulations will hold pricing power.

Why this matters to retailers and category managers

The practical question for any buyer is simple: does this change what I should stock, how I should merchandise it, and what I can expect from the supplier relationship?

The strongest read is that Iovate is signalling continuity of brand investment paired with an acceleration of innovation. The company has flagged an intensified focus on its core franchises alongside breakthrough platforms across creatine, muscle health, performance, peptides, and weight-loss transformation. Each of those maps directly to a live retail opportunity:

Creatine has broken out of the bodybuilding niche and into mainstream wellness, with women, older shoppers, and cognitive-health buyers driving incremental demand — a basket-building opportunity for retailers who merchandise it beyond the sports-nutrition set. Muscle health and performance speak to the healthy-ageing and longevity shopper, arguably the highest-value demographic in the store. And the explicit nod to weight-loss transformation lands squarely in the GLP-1 era, where supplement retail is being reorganized around muscle preservation, protein adequacy, and metabolic support for consumers on or adjacent to weight-loss medications.

A supplier intent on innovating across those exact platforms is a supplier worth building deeper category partnerships with — provided the science holds and the supply chain delivers. Bashir’s stated emphasis on supply-chain resilience is not boilerplate; for retailers burned by out-of-stocks on hero SKUs, reliable replenishment is a margin and loyalty issue, not a logistics footnote.

The GLP-1 question Iovate is implicitly answering

No conversation about weight management in 2026 happens without GLP-1s in the room. The rise of these medications has reshaped how consumers think about weight loss, and it has forced legacy weight-management brands — Hydroxycut among them — to confront an existential question: what is our role when pharmacology is doing the heavy lifting?

Iovate’s framing of “weight-loss transformation” rather than simply “weight loss” hints at the strategic answer the smartest brands are converging on. The commercial future for supplements in this category is less about competing with GLP-1s and more about supporting the people using them: protecting lean muscle mass, maintaining nutrient intake, and managing the side effects and lifestyle shifts that come with rapid weight change. A research-led CEO is exactly the profile you would want steering a brand through that pivot, because the repositioning lives or dies on clinical credibility. Retailers who anticipate this shift — and merchandise companion nutrition alongside the weight-management set — stand to capture demand that pure pharma cannot serve.

Credibility as a competitive moat

Bashir’s external footprint reinforces the science-first thesis. He spearheaded Iovate’s research partnership with the University of Toronto, sits on the board and Sports Nutrition Committee of the American Herbal Products Association, and holds a master’s degree in Human Health and Nutritional Science from the University of Guelph. In a category where regulators, retailers, and consumers are all tightening their scrutiny of claims, institutional credibility of that kind is a commercial asset. It de-risks the brand for the buyer and gives sales teams a defensible story to tell.

For Canadian retailers in particular, having a globally significant active-nutrition manufacturer headquartered in Oakville and led by a scientist embedded in North American industry governance is a point of leverage — in compliance confidence, in NPN-era claims discipline, and in the credibility that comes from stocking brands built on real research rather than borrowed trends.

The outlook: agility meets evidence

The throughline of Bashir’s appointment is the attempt to fuse two things that large nutrition companies often treat as opposites: the rigour of clinical science and the speed of an entrepreneurial brand. The companies that win the next cycle of active nutrition will be the ones that can move at culture speed while standing on evidence — launching relevant products fast enough to matter, but backing them with science strong enough to survive scrutiny.

If Iovate executes on that ambition, the payoff for trade partners is tangible: fresher, more culturally relevant brands; formulations that hold up to consumer and regulatory questioning; and a supply chain built to keep hero products on the shelf. The risk, as always, is execution — strategy framed in a press release is not strategy delivered at retail.

For now, the actionable takeaway for buyers and brand partners is straightforward. Watch Iovate’s innovation pipeline across creatine, muscle health, and GLP-1-adjacent nutrition closely over the next several quarters, treat the core brands as anchored bets rather than declining legacy lines, and use the leadership change as an opening to renegotiate category partnerships around the platforms Iovate has told the market it intends to win.

FAQ

Who is the new CEO of Iovate Health Sciences? Raza Bashir is the new Chief Executive Officer of Iovate Health Sciences International, effective immediately. He previously served as the company’s Chief Innovation Officer and has spent nearly two decades at Iovate.

What brands does Iovate own? Iovate’s portfolio includes MuscleTech®, Hydroxycut®, Six Star Pro Nutrition®, and Purely Inspired® — leading names in sports nutrition, performance, and weight management.

Where is Iovate Health Sciences headquartered? Iovate is headquartered in Oakville, Ontario, Canada, and was founded in 1995.

What is Raza Bashir’s background? Bashir holds a master’s degree (MSc) in Human Health and Nutritional Science from the University of Guelph. He spearheaded Iovate’s research partnership with the University of Toronto and serves on the board and Sports Nutrition Committee of the American Herbal Products Association (AHPA).

What will change under the new CEO? Iovate has signalled an accelerated focus on its core brands and on breakthrough innovation across creatine, muscle health, performance, peptides, and weight-loss transformation, alongside a stronger emphasis on consumer relevance, trusted science, and supply-chain resilience.

Why does this leadership change matter to retailers? The appointment of a science-trained innovation leader signals continued brand investment and an evidence-first product strategy — relevant for category managers deciding how to stock and merchandise active-nutrition and weight-management products in the GLP-1 era.

The Cage-Free Reckoning: Why Egg Sourcing Is Becoming a Retail Trust Battleground

0

When The Humane League escalated its national campaign against Kroger this month to name Harris Teeter directly, it did more than target one premium American grocer. It signalled a structural shift that every Canadian health retailer, grocery category manager, and supplement brand should be tracking closely: animal welfare sourcing has moved from a back-of-house procurement detail to a front-of-store trust issue—and the gap between marketing promises and supply chain reality is now where reputations are won and lost.

The campaign’s mechanics are instructive. The Humane League is calling on Harris Teeter, which sources an estimated 429 million eggs annually and impacts roughly 1.5 million hens each year, to publish a clear roadmap for transitioning 100% of its egg supply to cage-free sourcing. The advocacy group anchored its push with a children’s book, Harriet the Dragon and the Secret of the Dungeons, a parody of the grocer’s mascot designed to reach the exact demographic Harris Teeter depends on: parents and loyal shoppers. The strategic logic is unmistakable. As The Humane League CEO Dan Shannon framed it, “You cannot claim to offer a premium grocery experience and care about your customers while not fulfilling basic animal welfare.” The pressure point is not the egg itself. It is the contradiction between an upscale brand promise and an opaque supply chain.

Why This Is a Canadian Story, Not Just an American One

It would be easy for Canadian operators to file this under “U.S. retail politics.” That would be a mistake. The same reckoning is already unfolding here, and the Canadian numbers are arguably more exposed.

In 2016, members of the Retail Council of Canada—including Loblaw, Metro, Sobeys, and Walmart Canada—voluntarily committed to sourcing 100% cage-free eggs by the end of 2025. That deadline has now passed. Yet a 2025 assessment from Mercy For Animals found that the country’s largest grocers have largely failed to deliver, with none of the top retailers assessed meeting their targets or publishing a detailed plan to get there. Loblaw was reported at roughly 16% cage-free. Sobeys sat at 17–18%, with little measurable progress over four years. Costco, which reports being 97% cage-free in the United States, was assessed at only 21.3% in Canada. Eight major companies received failing grades.

That last data point should stop every Canadian category manager cold. A retailer operating at 97% cage-free in one market and 21% in another is not facing a supply problem. It is making a sourcing choice—and it is a choice that becomes indefensible the moment a campaign group, a journalist, or a well-organized parent decides to make it visible.

The Supply Excuse Is Collapsing

For years, the standard industry defence against accelerated cage-free timelines was supply constraint: the systems simply were not in place to convert at scale without driving prices to unacceptable levels. That argument is now eroding in real time. As of April 2026, nearly half of the U.S. egg-laying flock—47.7%—is already cage-free, and producers continue investing in higher-welfare systems. With more than 57% of U.S. eggs sold through retail, grocers are not passive recipients of whatever the supply chain produces. Through pricing, shelf placement, and promotion, they actively shape what lands in the cart.

In other words, the lever was always in the retailer’s hands. As the market crosses the halfway mark on cage-free production, “we can’t source it” stops reading as an operational reality and starts reading as a positioning decision. For a premium banner, that is a dangerous place to be standing when the spotlight arrives.

The Competitive Divide: Transparency as a Moat

What makes the Harris Teeter campaign commercially significant is the contrast it draws between leaders and laggards. Ahold Delhaize has published detailed, year-by-year roadmaps to 100% cage-free sourcing. Target has released an updated commitment with a 2030 timeline, progress reporting by unit sales, and defined steps to guide shoppers toward cage-free options. Food Lion has moved ahead with more transparent sourcing plans. These retailers have effectively converted compliance into a marketing asset—and, just as importantly, into reputational insurance.

The retailers without a public roadmap are left holding all of the risk and none of the upside. They absorb the same long-term cost pressures as their competitors, but they forfeit the trust dividend that transparency pays. In a category where “quality” and “trust” are the entire brand premise, that is a structurally weak position. The lesson for Canadian retail leadership is direct: a credible, published, time-bound plan is no longer a nice-to-have sustainability gesture. It is competitive infrastructure.

What This Means for the Natural Health and Wellness Channel

For IHR Magazine’s core audience—natural health retailers, independent health food stores, pharmacy operators, and the supplement and functional food brands that supply them—the cage-free story carries a sharper edge than it does for conventional grocery.

The natural and organic channel built its entire value proposition on the promise of higher standards: cleaner sourcing, greater transparency, and a more trustworthy relationship between shopper and shelf. That promise is precisely what makes the channel both more credible and more vulnerable. A conventional banner caught with a 21% cage-free figure faces an awkward news cycle. A retailer or brand positioned on ethics and transparency caught in the same gap faces an existential one, because the contradiction strikes at the core of why customers chose them in the first place.

There is a corresponding opportunity. Independent health retailers have always been able to move faster than national chains, and the cage-free divide is a chance to demonstrate that agility commercially. Stocking and signposting verified higher-welfare eggs and egg-based functional products, sourcing from suppliers who can document their practices, and communicating those standards plainly at shelf converts an industry pressure point into a point of differentiation. For functional food and supplement brands using egg-derived ingredients—egg-white protein, certain lipids, and emerging formulation inputs—supply chain documentation is quietly becoming a procurement and retail-listing requirement, not just a values statement. Brands that can answer the sourcing question before it is asked will clear retail buying reviews faster.

The Strategic Outlook

The trajectory is now visible. Animal welfare transparency is following the same path that ingredient transparency and clean-label claims travelled over the past decade: from activist talking point, to differentiated marketing claim, to baseline expectation. The retailers and brands that treat the current moment as a communications nuisance will find themselves managing it as a crisis later. Those that treat it as an early signal will build the documentation, supplier relationships, and public roadmaps that turn a looming liability into a trust asset.

The Harris Teeter campaign is not really about one grocer’s eggs. It is a preview of how scrutiny now travels—fast, targeted, and aimed squarely at the gap between what a brand says and what its supply chain does. In Canada, where the 2025 cage-free deadline has already come and gone unmet, that gap is wide open. The smartest operators in natural health retail will read this campaign not as someone else’s problem, but as a countdown clock on their own credibility—and start closing the distance now, while doing so is still a choice rather than a reaction.

FAQ

What is cage-free egg sourcing? Cage-free sourcing means eggs come from hens that are not confined to battery cages and can move freely within a barn or housing system. It is a higher-welfare standard that retailers and brands increasingly use as a benchmark for responsible procurement and consumer-facing trust claims.

Why are retailers being pressured on cage-free eggs in 2026? Advocacy groups such as The Humane League are escalating campaigns because the supply-side justification for delay is weakening—nearly 48% of the U.S. egg-laying flock is already cage-free as of April 2026—while several major retailers still have not published transparent roadmaps. The pressure targets the gap between premium brand promises and opaque sourcing practices.

Have Canadian grocers met their cage-free commitments? Largely no. Major Canadian grocers committed to 100% cage-free sourcing by the end of 2025, but 2025 assessments found leading retailers well short—Loblaw near 16% and Sobeys around 17–18%—with none publishing a detailed completion plan, according to Mercy For Animals.

Why does egg sourcing matter to natural health and supplement businesses? The natural health channel is built on transparency and higher standards, so any gap between stated values and actual sourcing is a heightened reputational risk. It is also an opportunity: independent retailers and ingredient-led brands that can document higher-welfare sourcing gain a differentiation and retail-listing advantage.

Independent Health Retailers Aren’t Losing to Amazon Because They’re Small

0

Ask any independent health retailer what keeps them up at night and Amazon comes up quickly.

Not always by name. Sometimes it surfaces as a complaint about customers who “just order online.” Sometimes it’s the observation that foot traffic has softened despite a loyal base. Sometimes it’s the moment at the cash register when a customer mentions they tried to find a product on your website, couldn’t, and ended up ordering it elsewhere.

The elsewhere, more often than not, is Amazon.

The conventional diagnosis is that independent retailers are simply outgunned. Too small. Too local. Too limited in budget, inventory, and logistics capacity to compete with a company that has spent two decades and hundreds of billions of dollars building the most efficient retail infrastructure in human history.

It’s a reasonable diagnosis. It is also, in important ways, the wrong one.

The Real Reason Customers Go to Amazon
Amazon does not win health retail customers because it has better products. Natural health is one of the few retail categories where the independent operator has a genuine and durable advantage in product knowledge, customer relationships, and the kind of personalized guidance that no algorithm replicates.

Amazon wins on two things: availability and speed.

When a customer searches for a magnesium glycinate supplement and your store is out of stock, Amazon has it. When a customer needs a product delivered before the weekend and your store doesn’t offer fast shipping, Amazon does. When a customer visits your website at 11pm and your catalog lists 180 products where Amazon lists 18,000, the decision becomes reflexive rather than considered.

The independent retailer loses not because they are inferior. They lose because they are isolated.

One location. One inventory. One set of fulfillment capabilities bounded by the resources of a single business operating independently of every other health retailer in their region, their province, their country.

That isolation is the structural problem. And it is a problem that has nothing to do with how good the retailer is at their job.

What Isolation Actually Costs
The cost of an out-of-stock moment is rarely calculated accurately because it extends well beyond the immediate lost sale.

A customer who visits your store and finds the product they need goes home satisfied. They associate your store with reliability. They come back. They recommend you.

A customer who visits your store, finds the product out of stock, and orders it from Amazon goes home and begins building a habit. Not because they prefer Amazon. Because Amazon was there when you weren’t. The repeat purchase goes to Amazon. The next product they need, they search Amazon first. The subscription they eventually set up for their monthly supplement order goes to Amazon.

One out-of-stock moment does not cost you one sale. In a meaningful number of cases, it costs you a customer.

Independent health retailers across Canada collectively lose millions in revenue annually not to a competitor with better products or lower prices, but to an infrastructure gap — the gap between what a customer needs in the moment and what a single isolated store can reliably provide.

The Network Answer
The solution to an infrastructure problem is infrastructure.

Not the kind that requires a single retailer to build a warehouse network, hire a logistics team, or raise significant capital. The kind that already exists — distributed across hundreds of independent health retailers who collectively carry enormous depth of inventory, cover meaningful geographic area, and serve a shared customer base.

The IHR network connects independent health retailers into a shared fulfillment infrastructure. When a participating retailer is out of stock on a product, the network identifies the nearest node that carries it and routes the order there. The customer receives their product on time. The selling retailer earns a commission on the sale. The fulfilling retailer earns a fulfillment fee.

Nobody goes to Amazon.

The customer who typed your store’s name into their browser, found the product they needed, and placed an order — stays yours. Even if the physical product shipped from a retailer in the next neighbourhood. Even if your shelf was empty when the order came in.

This is what it means to stop being isolated. Not to become a large company. Not to build a warehouse. Simply to become part of a network that is collectively larger, better-stocked, and more capable than any single member within it.

Why This Matters More Now Than It Did Five Years Ago
Consumer expectations around delivery have compressed dramatically and show no signs of reversing. Two-day delivery, which Amazon introduced as a premium offering, is now a baseline expectation for a growing segment of online shoppers. Same-day delivery, once a novelty, is increasingly the differentiator in urban markets.

Independent health retailers who are not part of a fulfillment network are not competing on the same terms as the retailers who are. The gap between those two groups will widen, not narrow, as delivery expectations continue to rise.

The window to join a founding network — to establish a node rating, build fulfillment history, and position a store as a trusted regional hub before the network scales — is finite. The retailers who join early earn the routing advantages that come with an established track record. The retailers who join later inherit a more competitive landscape within the network itself.

This is not a criticism of retailers who haven’t yet made the move. The infrastructure to do this simply did not exist, at an accessible price point and with a realistic setup process, until recently.

It exists now.

Frequently Asked Questions
Does joining the IHR network mean giving up control of my store or my brand?
No. Retailers in the IHR network operate their own stores independently. The network handles fulfillment routing and revenue distribution behind the scenes. Your customer relationships, store branding, and product curation remain entirely yours.

What happens when my store is the fulfillment node for another retailer’s order?
You receive a fulfillment notification with the order details and a shipping window. You pack and ship the order as you would any of your own. You earn a fulfillment fee. The process is operationally identical to fulfilling one of your own orders.

Does being part of the network mean I compete with other retailers in it?
The network is designed around complementary geography and inventory depth, not competition. Routing favors the nearest node with available stock — which means retailers in different areas serve different customers, and retailers in the same area benefit from each other’s inventory coverage.

What does a retailer need to join?
An existing health retail operation, an online store on a supported platform (Shopify, WooCommerce, and others), and a willingness to fulfill orders within the network’s SLA windows: one hour to accept, three hours to confirm fulfillment.

The customers leaving your store for Amazon are not choosing Amazon. They are choosing availability.

Give them availability and they choose you.

IHR is now accepting independent health retailers into its founding network.


Le problème de site web que rencontrent tous les détaillants indépendants en produits de santé — et la solution qui prend 20 minutes

0

Vous n’avez rien à refaire. Il vous suffit de disposer de la bonne infrastructure derrière ce que vous avez déjà.Il existe une version de cette histoire qui se répète chaque semaine dans les magasins de produits de santé à travers le Canada.

Un client entre. Il achète ce pour quoi il est venu. En sortant, il mentionne qu’il avait une question à vous poser : avez-vous une marque particulière de glycinate de magnésium ? Un probiotique spécifique recommandé par son naturopathe ? Une poudre de légumes verts qu’il a vue sur Instagram ?

Vous ne l’avez pas. Vous le lui dites. Il hoche la tête, vous remercie et s’en va.

Plus tard dans la soirée, il le trouve en ligne. Pas dans votre magasin — votre site web ne répertorie que les produits que vous avez physiquement en stock — mais ailleurs. Sur Amazon, probablement. Ou sur le site d’une marque vendant directement aux consommateurs. Ou chez un concurrent situé à trois villes de là qui, par hasard, l’avait en stock et expédiait dans tout le pays.

Vous n’avez pas perdu ce client à cause d’une erreur de votre part. Vous l’avez perdu à cause d’un problème structurel auquel les détaillants indépendants du secteur de la santé sont confrontés depuis des années : le fossé entre ce qu’un client s’attend à trouver et ce qu’un détaillant disposant d’un seul point de vente peut raisonnablement stocker, présenter et livrer.

Jusqu’à récemment, combler ce fossé nécessitait des investissements considérables. Un développeur. Une nouvelle plateforme. Un partenariat avec un entrepôt. Un contrat logistique. Des semaines de travail d’intégration et une facture qui arrivait avant même la première vente.

La question qu’il convient de se poser en 2025 est de savoir si tout cela est encore nécessaire.

Le problème d’infrastructure qui se cache derrière un problème de stock

Discutez avec suffisamment de détaillants indépendants du secteur de la santé et une tendance se dessine rapidement. La conversation commence par le stock — « nous ne pouvons pas tout proposer » — mais elle ne s’y attarde pas longtemps.

Car le problème de stock est en réalité un problème de site web. Et le problème de site web est en réalité un problème d’infrastructure.

Une grande chaîne de pharmacies peut proposer 4 000 références de produits de santé naturels en ligne car elle dispose de relations avec des entrepôts, d’une infrastructure de traitement des commandes et d’une équipe technique chargée de la maintenance de l’intégration. Elle peut offrir la livraison le lendemain dans toutes les provinces car elle dispose de centres de distribution dans plusieurs régions. Elle peut mener des campagnes promotionnelles sur Meta, Google et TikTok car elle dispose d’un service marketing.

Rien de tout cela n’est reproductible au niveau des détaillants indépendants — ou du moins, ça ne l’était pas. Les outils qui alimentent cette infrastructure ont toujours été tarifés, dimensionnés et conçus pour des opérateurs disposant de ressources que les détaillants indépendants n’ont tout simplement pas.

Ce qui a changé, ce ne sont pas les outils eux-mêmes. Ce qui a changé, c’est le modèle.

Ce qu’un plugin fait réellement et qu’une refonte de site web ne fait pas

L’instinct, lorsqu’un détaillant de produits de santé décide que son site web n’est pas performant, est de le refaire. Un nouveau thème. De meilleures photos. Une navigation plus claire. Parfois, une migration vers une toute nouvelle plateforme.

Ce ne sont pas de mauvaises décisions prises isolément. Mais elles résolvent un problème de présentation alors que le véritable problème est un problème de produit et d’infrastructure. Un site web magnifiquement conçu avec 150 références reste un site web avec 150 références.

Le plugin IHR aborde le problème sous un autre angle.

Plutôt que de demander aux détaillants de refaire leur vitrine, il s’intègre à la boutique qu’ils possèdent déjà — Shopify, WooCommerce, BigCommerce, Wix, Squarespace et autres — et la connecte à un réseau actif de fournisseurs de produits de santé naturels agréés et de centres de traitement des commandes à travers le Canada.

Le site web du détaillant ne change pas. L’expérience client sur ce site web ne change pas. Ce qui change, c’est ce qui y est disponible et ce qui se passe sur le plan opérationnel lorsqu’une commande est passée.

Les produits des fournisseurs agréés du réseau IHR peuvent être consultés, sélectionnés et ajoutés à la boutique en ligne d’un détaillant en une seule session. Les images, les descriptions et les prix sont fournis prêts à l’emploi. Pas de photographie. Pas de rédaction. Pas de saisie de données. Lorsqu’un client passe commande, la logistique est automatiquement acheminée vers le centre de distribution le plus proche disposant d’un stock disponible. Les revenus sont répartis entre le détaillant vendeur, le centre de distribution et le fournisseur — sans que personne ne gère la transaction manuellement.

Le processus de configuration, de l’installation du plugin à la mise en ligne des premiers produits sur le site d’un détaillant, prend moins de 20 minutes pour la plupart des utilisateurs. Il ne nécessite aucune connaissance en codage, aucune relation avec un développeur et aucune modification de l’infrastructure existante de la boutique.

La question de la sélection

Une préoccupation qui revient régulièrement chez les détaillants de produits de santé indépendants lorsqu’ils entendent les mots « élargissez votre catalogue » est compréhensible : Je ne veux pas devenir une boutique générique.

C’est une préoccupation légitime. L’identité d’un détaillant indépendant de produits de santé — ce qui le rend préférable à une grande surface — réside souvent précisément dans la sélection. Le propriétaire qui connaît parfaitement ses gammes de produits. Le magasin qui ne propose pas tout, mais propose ce qu’il faut. La philosophie spécifique qui transparaît dans ce qui se trouve en rayon.

IHR n’est pas une place de marché qui remplace cette identité. C’est un catalogue qui l’élargit.

Les détaillants choisissent exactement les marques qu’ils ajoutent et celles qu’ils n’ajoutent pas. L’intégralité du catalogue IHR est consultable, filtrable et sélectionnable au niveau des références (SKU). Un dispensaire de naturopathie recherchant uniquement des gammes de qualité professionnelle peut filtrer exactement selon ce critère. Un détaillant de nutrition sportive souhaitant se diversifier dans les aliments fonctionnels peut parcourir le catalogue par catégorie. Une boutique de bien-être ayant une forte préférence pour les marques fabriquées au Canada peut effectuer une recherche par lieu d’implantation du fournisseur.

Rien n’est ajouté sans un choix délibéré. Rien n’est imposé à la liste d’un magasin. Et tout ce qui est ajouté peut être supprimé instantanément — pas de contrat, pas d’engagement minimum par produit, pas de pénalités en cas de changement d’orientation à mesure que les besoins du magasin évoluent.

Le catalogue offre une gamme. Le détaillant juge de ce qui convient.

Pourquoi « Aucun codage requis » mérite d’être pris au sérieux

L’expression « aucun codage requis » est devenue un cliché dans le marketing des logiciels — si souvent utilisée qu’elle a largement perdu son sens. Il vaut la peine de préciser ce qu’elle signifie réellement dans ce contexte, car les implications sont pratiques et importantes.

Pour qu’un détaillant de produits de santé ajoute IHR à sa boutique Shopify existante, les étapes sont les suivantes :

Trouvez le plugin IHR dans l’App Store de Shopify. Cliquez sur « Installer ». Connectez-vous à votre compte IHR. Connectez-vous. Parcourez le catalogue. Sélectionnez les produits souhaités. Cliquez sur « Ajouter à la boutique ».

C’est tout le processus. Il n’y a aucun fichier de configuration à modifier, aucun code de thème à changer, aucun webhook à configurer manuellement, aucune clé API à rechercher et à coller quelque part. La connexion entre le plugin et la boutique est gérée via un flux OAuth standard — le même mécanisme d’authentification utilisé par des dizaines d’autres applications Shopify — et l’importation des produits est une opération via l’interface utilisateur, et non une opération technique.

Pour les commerçants WooCommerce, le processus est tout aussi simple. Installez le plugin depuis le tableau de bord WordPress. Saisissez les identifiants API générés dans votre compte IHR. Parcourez et ajoutez des produits via l’interface IHR.

Tout cela ne nécessite pas l’intervention d’un développeur. Il faut simplement être prêt à consacrer 20 minutes à un processus de configuration simple — ce qui, vu le résultat, est tout à fait raisonnable.

Le changement déjà en cours dans le commerce de détail de la santé au Canada

Les détaillants qui subissent le plus de pression actuellement ne sont pas ceux qui proposent les mauvais produits. Ce sont ceux qui ont les bons produits mais une portée insuffisante — limitée par la géographie, par les contraintes d’un stock centralisé et par des sites web conçus pour présenter leur gamme plutôt que pour développer leur offre.

Les outils permettant de changer cela ne nécessitent plus d’investissements à l’échelle d’une grande entreprise. Ils nécessitent un plugin, une configuration de 20 minutes et la volonté de laisser un réseau prendre en charge une partie du poids de l’infrastructure que les détaillants indépendants ont jusqu’à présent supporté seuls.

Pour les magasins qui adoptent cette infrastructure tôt, l’avantage est décuplé. Plus de produits signifie plus de raisons pour les clients de revenir. Une plus grande capacité de traitement des commandes signifie une livraison plus rapide. Une livraison plus rapide signifie moins de clients qui vont chercher ailleurs.

Pour les magasins qui attendent, l’écart se creuse.

Une remarque pratique avant que vous ne rejetiez cela comme étant trop beau pour être vrai

Il est raisonnable d’être sceptique face à toute technologie promettant la simplicité dans un domaine qui a toujours été synonyme de complexité. Quelques précisions méritent d’être explicitement mentionnées :

La configuration en 20 minutes est réelle, mais elle suppose un magasin existant et opérationnel. Un détaillant qui n’a jamais mis en place de boutique en ligne aura besoin de plus de temps — bien que l’équipe d’intégration d’IHR fournisse une assistance directe pour la première configuration. Le catalogue de produits est bien réel, mais il s’enrichit à mesure que de nouveaux fournisseurs rejoignent le réseau — les premiers détaillants auront accès aux relations avec les fournisseurs fondateurs et bénéficieront d’un accès prioritaire aux nouvelles marques ajoutées. Le modèle sans stock est bien réel, mais il fonctionne dans les limites de la capacité de traitement des commandes du réseau — les détaillants doivent s’attendre à une amélioration de la couverture à mesure que le réseau s’étend à travers les provinces.

Rien de tout cela ne diminue la proposition de base. Cela la contextualise avec précision. Le plugin IHR n’est pas magique. C’est une infrastructure — du type de celle à laquelle les grands opérateurs ont accès depuis des années, désormais mise à la disposition du détaillant indépendant sans le coût et la complexité qui la rendaient auparavant inaccessible.

Foire aux questions

L’installation du plugin IHR modifie-t-elle l’apparence de mon site web pour mes clients ? Non. Le design, l’image de marque et la navigation de votre boutique restent entièrement inchangés. Les produits IHR apparaissent sous forme de listes supplémentaires dont le style s’adapte à votre format de produit existant. Vos clients voient un catalogue plus vaste. Ils ne voient pas une boutique différente.

Dois-je acheter ou détenir un stock pour vendre des produits du catalogue IHR ? Non. Lorsqu’un client commande un produit du catalogue IHR depuis votre boutique, la gestion de la commande est assurée par le réseau — acheminée vers le nœud agréé le plus proche disposant d’un stock disponible. Vous percevez une commission sur la vente sans avoir à détenir ni expédier le produit vous-même.

Que faire si je souhaite n’ajouter qu’un petit nombre de produits pour commencer ? Il n’y a pas de minimum. Les détaillants peuvent ajouter un seul produit ou cinq cents. La plupart des détaillants trouvent utile de commencer par une sélection ciblée de 20 à 50 références dans des catégories proches de leurs points forts existants, puis de s’étendre en fonction de la réaction des clients.

Puis-je fixer mes propres prix sur les produits du catalogue ? La tarification s’effectue dans la fourchette du prix public minimum (PPM) fixée par chaque fournisseur. Les détaillants ne peuvent pas proposer de prix inférieurs au MAP, mais peuvent fixer des prix égaux ou supérieurs à celui-ci. Cette structure protège le positionnement de la marque sur le marché et garantit que les marges des détaillants restent viables.

Que se passe-t-il pour une fiche produit si elle est en rupture de stock sur l’ensemble du réseau ? Le statut de rupture de stock est mis à jour en temps réel. Les produits indisponibles sur l’ensemble du réseau sont automatiquement signalés comme étant en rupture de stock sur votre boutique jusqu’à ce que l’approvisionnement soit rétabli.

Y a-t-il un contrat ou un engagement minimum ? Aucun contrat à long terme n’est requis. Les détaillants peuvent ajouter et retirer des produits à tout moment, et les abonnements sont facturés mensuellement avec la possibilité de résilier.

À qui cela s’adresse-t-il ? À tout détaillant indépendant du secteur de la santé disposant d’une boutique en ligne existante sur une plateforme prise en charge — y compris les magasins d’aliments naturels, les pharmacies, les dispensaires de naturopathie, les cliniques de bien-être et les détaillants de nutrition sportive. La plateforme accueille actuellement des détaillants canadiens, et une expansion est prévue.

Ce qu’il faut faire cette semaine

L’avantage structurel que les grandes chaînes ont acquis par rapport aux détaillants de produits de santé indépendants est bien réel. Mais il repose sur des infrastructures — entrepôts, équipes techniques, contrats logistiques, services marketing — et non sur une supériorité fondamentale en matière de connaissance des produits, de relations clients ou de philosophie commerciale.

Ces avantages sont désormais accessibles sans les coûts d’infrastructure qui les rendaient auparavant inaccessibles.

Le plugin IHR connecte les détaillants indépendants du secteur de la santé à un réseau de traitement des commandes partagé, à un catalogue de fournisseurs agréés et à une suite d’automatisation du marketing — grâce à une configuration de 20 minutes qui ne nécessite aucun codage, aucune refonte et aucune modification de ce que vous avez déjà mis en place.

IHR accepte désormais les détaillants indépendants du secteur de la santé dans son réseau fondateur. Les membres fondateurs bénéficient de tarifs garantis, d’une intégration prioritaire et d’un soutien direct de l’équipe IHR.

Inscrivez-vous sur la liste d’attente à l’adresse ihrmagazine.com/plugin

The Website Problem Every Independent Health Retailer Has — And the Fix That Takes 20 Minutes

0

You don’t need to rebuild anything. You just need the right infrastructure behind what you already have.

There is a version of this story that plays out in health retail stores across Canada every single week.

A customer walks in. They buy what they came for. On their way out, they mention they’ve been meaning to ask — do you carry a particular brand of magnesium glycinate? A specific probiotic their naturopath recommended? A greens powder they saw on Instagram?

You don’t have it. You tell them so. They nod, thank you, and leave.

Later that evening, they find it online. Not at your store — your website only lists the products you physically carry — but somewhere else. Amazon, probably. Or a direct-to-consumer brand site. Or a competitor three cities away who happened to stock it and ship across the country.

You didn’t lose that customer because of anything you did wrong. You lost them because of a structural problem that independent health retailers have been navigating for years: the gap between what a customer expects to find and what a single-location retailer can reasonably stock, display, and fulfill.

That gap, until recently, required significant investment to close. A developer. A new platform. A warehouse relationship. A logistics contract. Weeks of integration work and an invoice that arrived before the first sale did.

The question worth asking, is whether any of that is still necessary.

The Infrastructure Problem Hiding Inside an Inventory Problem
Talk to enough independent health retailers and a pattern emerges quickly. The conversation starts with inventory — “we can’t carry everything” — but it doesn’t stay there for long.

Because the inventory problem is really a website problem. And the website problem is really an infrastructure problem.

A large chain pharmacy can list 4,000 natural health SKUs online because it has warehouse relationships, fulfillment infrastructure, and a technology team maintaining the integration. It can offer next-day delivery across provinces because it has distribution nodes in multiple regions. It can run promotional campaigns across Meta, Google, and TikTok because it has a marketing department.

None of that is replicable at the independent retailer level — or at least, it wasn’t. The tools that power that infrastructure have historically been priced, scoped, and designed for operators with resources that independent retailers simply don’t have.

What’s changed is not the tools themselves. What’s changed is the model.

What a Plugin Actually Does That a Website Rebuild Doesn’t
The instinct, when a health retailer decides their website isn’t performing, is to rebuild it. New theme. Better photography. Cleaner navigation. Sometimes a migration to a new platform entirely.

These are not bad decisions in isolation. But they solve a presentation problem when the actual problem is a product and infrastructure problem. A beautifully designed website with 150 SKUs is still a website with 150 SKUs.

The IHR Plugin approaches the problem from the other direction.

Rather than asking retailers to rebuild their storefront, it plugs into the store they already have — Shopify, WooCommerce, BigCommerce, Wix, Squarespace, and others — and connects it to a live network of authorized natural health vendors and fulfillment nodes across Canada.

The retailer’s website doesn’t change. The customer’s experience of that website doesn’t change. What changes is what’s available on it, and what happens operationally when someone places an order.

Products from authorized vendors in the IHR network can be browsed, selected, and added to a retailer’s live store in a single session. Images, descriptions, and pricing come pre-formatted. No photography. No copywriting. No data entry. When a customer orders, fulfillment routes automatically to the closest node with available stock. Revenue is split between the selling retailer, the fulfilling node, and the vendor — without anyone managing the transaction manually.

The setup process, from plugin installation to first products live on a retailer’s site, takes most users under 20 minutes. It requires no coding knowledge, no developer relationship, and no changes to existing store infrastructure.

The Curation Question
One concern that surfaces regularly among independent health retailers when they hear the words “expand your catalog” is understandable: I don’t want to become a generic store.

It is a legitimate concern. The identity of an independent health retailer — what makes it worth choosing over a big-box alternative — is often precisely the curation. The owner who knows their product lines deeply. The store that doesn’t carry everything, but carries the right things. The specific philosophy visible in what sits on the shelf.

Retailers choose exactly which brands they add and which ones they don’t. The full IHR catalog is browsable, filterable, and opt-in at the SKU level. A naturopathic dispensary looking only for practitioner-grade lines can filter for exactly that. A sports nutrition retailer looking to expand into functional foods can browse by category. A wellness boutique with a strong preference for Canadian-made brands can search by vendor location.

Nothing is added without a deliberate choice. Nothing is forced onto a store’s listing. And anything added can be removed instantly — no contract, no minimum commitment per product, no penalties for changing direction as the store’s needs evolve.

The catalog provides range. The retailer provides the judgment about what fits.

Why “No Coding Required” Is Worth Taking Seriously
The phrase “no coding required” has become something of a cliché in software marketing — invoked so frequently that it has largely lost its meaning. It’s worth being specific about what it actually means in this context, because the implications are practical and significant.

Find the IHR Plugin in the Shopify App Store. Click install. Log into your IHR account. Connect. Browse the catalog. Select the products you want. Click Add to Store.

That is the complete process. There is no configuration file to edit, no theme code to modify, no webhook to set up manually, no API key to locate and paste somewhere. The connection between the plugin and the store is handled through a standard OAuth flow — the same authentication mechanism used by dozens of other Shopify apps — and the product import is a UI operation, not a technical one.

For WooCommerce retailers, the process is similarly contained. Install the plugin from the WordPress dashboard. Enter the API credentials generated in your IHR account. Browse and add products through the IHR interface.

None of this requires a developer. It does require a willingness to spend 20 minutes working through a straightforward setup process — which, given the outcome, is a reasonable ask.

The Shift Already Happening in Canadian Health Retail
The retailers feeling the most pressure right now are not the ones who have the wrong products. They’re the ones with the right products but insufficient reach — limited by geography, by the constraints of single-location inventory, and by websites that were built to present what they carry rather than built to grow what they can offer.

The tools to change that no longer require enterprise-scale investment. They require a plugin, a 20-minute setup, and the willingness to let a network carry some of the infrastructure weight that independent retailers have been carrying alone.

For the stores that adopt this infrastructure early, the advantage compounds. More products mean more reasons for customers to come back. More fulfillment capacity means faster delivery. Faster delivery means fewer customers who go looking elsewhere.

For the stores that wait, the gap widens.

A Practical Note Before You Dismiss This as Too Good to Be True
It is reasonable to be skeptical of any technology promising simplicity in a space that has historically delivered complexity. A few clarifications worth making explicit:

The 20-minute setup is real, but it assumes a functioning existing store. A retailer who has never set up an online store will need more time — though the IHR onboarding team provides direct support for first-time setup. The product catalog is real, but it grows as more vendors join the network — early retailers will have access to founding vendor relationships and first-access to new brand additions. The no-inventory model is real, but it operates within the network’s fulfillment capacity — retailers should expect coverage to improve as the network scales across provinces.

None of this diminishes the core proposition. It contextualizes it accurately. The IHR Plugin is not magic. It is infrastructure — the kind that larger operators have had access to for years, now made available to the independent retailer without the cost and complexity that previously made it inaccessible.

Frequently Asked Questions
Does installing the IHR Plugin change how my website looks to my customers?
No. Your store’s design, branding, and navigation remain entirely unchanged. IHR products appear as additional listings styled to match your existing product format. Your customers see a larger catalog. They do not see a different store.

Do I need to purchase or hold any inventory to sell products from the IHR catalog?
No. When a customer orders an IHR catalog product from your store, fulfillment is handled through the network — routed to the closest authorized node with available stock. You earn a selling commission without holding or shipping the product yourself.

What if I only want to add a small number of products to start?
There is no minimum. Retailers can add a single product or five hundred. Most retailers find it useful to start with a focused selection of 20–50 SKUs in categories adjacent to their existing strengths, then expand as they observe customer response.

Can I set my own pricing on catalog products?
Pricing operates within the MAP (Minimum Advertised Price) range set by each vendor. Retailers cannot advertise below MAP, but can price at or above it. This structure protects the brand’s market positioning and ensures retailer margins remain viable.

What happens to a product listing if it goes out of stock across the network?
Out-of-stock status updates in real time. Products unavailable across the network are automatically marked as out of stock on your store until supply is restored.

Is there a contract or minimum commitment?
No long-term contract is required. Retailers can add and remove products at any time, and subscription plans are billed monthly with the option to cancel.

Who is this suited for?
Any independent health retailer with an existing online store on a supported platform — including health food stores, pharmacies, naturopathic dispensaries, wellness clinics, and sports nutrition retailers. The platform is currently onboarding Canadian retailers, with expansion planned.

What’s Worth Doing This Week
The structural advantage that large chains have built over independent health retailers is real. But it was built on infrastructure — warehouses, technology teams, logistics contracts, marketing departments — not on a fundamental superiority of product knowledge, customer relationships, or retail philosophy.

Those advantages are available now without the infrastructure cost that made them inaccessible.

The IHR Plugin connects independent health retailers to a shared fulfillment network, an authorized vendor catalogue, and a marketing automation suite — through a 20-minute setup that requires no coding, no rebuild, and no changes to what you’ve already built.

IHR is now accepting independent health retailers into its founding network. Founding members receive locked-in pricing, priority onboarding, and direct support from the IHR team.

Join the waitlist at https://retail.ihrmagazine.com/Inventory-Extension-Plugin


Why the Vitamin B6 Clampdown in Australia and Canada Should Worry Every Health Retailer

0

For two decades, vitamin B6 sat in the safest tier of the supplement aisle: cheap, familiar, and rarely questioned. That assumption is now under direct regulatory pressure in two of the world’s most influential natural health markets, and the read for the industry is bigger than a single ingredient.

In Australia, the Therapeutic Goods Administration has finalized a decision to reclassify higher-dose vitamin B6. From 1 June 2027, oral products delivering more than 50 mg per day and up to 200 mg will become Pharmacist Only Medicines, while products above 200 mg per day remain prescription-only. Only doses of 50 mg or less stay on open shelves. The trigger was an accumulation of adverse-event reports: as of October 2025, the TGA’s database held 250 reports of peripheral neuropathy and related nerve conditions linked to B6-containing products, recorded since January 2023. More than 100 products are expected to be affected.

Canada has moved on a parallel track, though with a lighter instrument. In a Summary Safety Review published in March 2026, Health Canada concluded there is a “possible link” between vitamin B6-containing natural health products and peripheral neuropathy at daily doses of 10 mg or higher. The regulator is updating its ingredient monographs and now expects licence holders to add neuropathy warnings to every B6 product at or above that 10 mg threshold. The scale is significant: more than 4,000 vitamin B6-containing NHPs are authorized in Canada at recommended doses of 10 mg or more.

Two regulators, two different mechanisms, one shared conclusion: a vitamin most consumers think of as harmless can carry a genuine safety signal, and “common vitamin equals low risk” is no longer a defensible default.

The science the industry stopped questioning

Peripheral neuropathy from excess B6 is not new. The textbook position held that toxicity appeared only at very high intakes — roughly 250 mg per day and above, sustained over time. That framing kept the category comfortable, because most multivitamins, energy formulas and B-complex products sit well below that line.

What changed is the evidence base. Health Canada’s review cited published cases of neuropathy at daily doses as low as 10 mg, and noted that no clear risk factors yet explain why some users are affected and others are not. The European Food Safety Authority reached a similarly cautious place in 2023, slashing its tolerable upper intake level for adults from 25 mg to 12 mg per day. The Netherlands’ pharmacovigilance centre and Australia’s adverse-event data point the same direction. When four respected regulators independently lower their thresholds within a few years, that is no longer an outlier reading — it is a trend line.

The commercial problem is that B6 is not confined to standalone pyridoxine tablets. It is a routine inclusion in B-complex formulas, energy and “metabolism” products, stress and sleep blends, pre-workout and women’s health lines, and supplemented foods such as energy drinks. The ingredient is everywhere, which means the regulatory exposure is everywhere too.

What this means for retailers

The immediate task is portfolio visibility. Most retailers do not know, off the top of their heads, how many SKUs on their shelves contain 10 mg or more of B6 — let alone how many sit above 50 mg. In the Canadian market especially, that number is likely far larger than category managers expect, because B6 hides inside combination products rather than announcing itself on the front of the pack.

Retailers operating in or sourcing from Australia face the sharper edge. Pharmacist-only status removes a product from open self-selection and places it behind a professional gatekeeper. For independent health food stores without a pharmacist on staff, higher-dose B6 lines simply leave the assortment. For pharmacy-integrated wellness operators, the same change is an opportunity: it pulls a previously commoditized product into the consultation zone, where margin and trust are higher.

In Canada, the near-term action is label compliance and shelf messaging. Products at 10 mg and above will carry neuropathy warnings, and retailers should expect questions at the point of sale. The smart move is to get ahead of the conversation rather than be caught flat-footed by it. Staff who can explain the warning calmly — that the signal concerns sustained high intake, that symptoms are typically reversible on stopping, and that food-sourced B6 is not the issue — protect both the sale and the customer relationship. Staff who shrug erode confidence in the whole category.

There is also a basket implication. B6 warnings invite shoppers to scrutinize their total intake across multiple products they may be stacking — a multivitamin plus a B-complex plus an energy formula. That is a merchandising prompt, not just a risk. It is an opening to move customers toward better-formulated, transparently dosed products and to position knowledgeable retail staff as the trusted filter consumers increasingly want.

What this means for brands

For manufacturers and formulators, the strategic question is whether to reformulate ahead of regulation or defend existing doses. The momentum across jurisdictions suggests reformulation is the lower-risk path for mass-market lines. Brands that proactively bring B6 down to defensible levels — and say so on pack — can turn a compliance chore into a positioning advantage at a moment when consumers are primed to reward restraint.

The harder calculation is for therapeutic positioning. Some B6 use is genuinely clinical — pregnancy nausea formulas, for instance, rely on the ingredient, and regulators have treated prescription pathways differently from open-shelf supplements. Brands with a legitimate higher-dose rationale will increasingly need to live in the pharmacist or practitioner channel rather than the open aisle, which changes packaging, claims and route to market.

Labelling discipline is now table stakes. Combination products that bury B6 content in a long ingredient panel are exactly the formats regulators and journalists scrutinize. Brands that lead with clear per-serving disclosure and a plain-language safety note will weather the news cycle far better than those that appear to be hiding the dose.

The bigger read: the “safe vitamin” era is ending

The most important takeaway is not about B6 at all. It is that regulators are now willing to challenge long-standing safety assumptions about mainstream ingredients, on the strength of pharmacovigilance data rather than catastrophic events. That willingness does not stop at one vitamin. The same logic — accumulating adverse-event reports, lowered upper limits, harmonization pressure — is already circling other high-dose nutrients and botanicals.

For an industry that has long traded on the public perception that vitamins are inherently benign, this is a structural shift. The competitive advantage is moving toward operators who treat dose, transparency and pharmacovigilance as commercial assets rather than regulatory friction. The brands and retailers that win the next decade will be the ones who can say, credibly and proactively, that they understood the risk before the regulator forced the conversation.

Vitamin B6 is the test case. The retailers and brands paying attention now — auditing their shelves, briefing their staff, and reformulating or repositioning where the data points — are not just managing a compliance event. They are rehearsing for the next ingredient, and the one after that.