All In Nutritionals
Home Blog Page 5

The New Merchandising Strategy: Selling Stress Support Through Ingredient Synergy

0

The stress-support category is no longer being driven solely by consumers seeking relaxation. Increasingly, the category is being fuelled by consumers looking for physiological resilience without cognitive impairment. That distinction matters at shelf.

Retailers who continue merchandising stress products exclusively within “sleep” or “calming” sections may be missing a broader behavioural-health opportunity emerging around daytime cortisol modulation, cognitive performance under stress, and nervous system regulation.

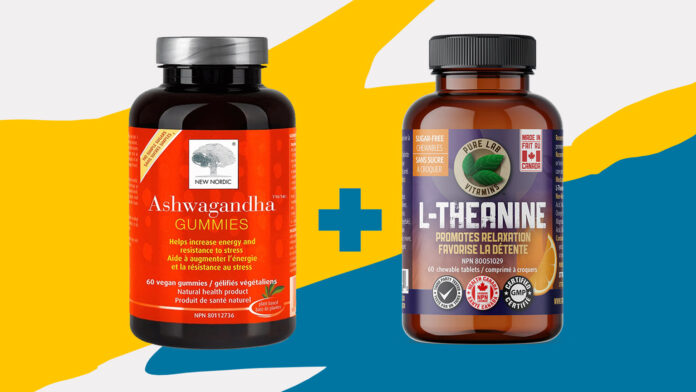
One of the strongest examples of this evolving strategy is the pairing of Ashwagandha with L-Theanine.

While both ingredients individually perform well in the stress-management category, their merchandising power increases substantially when positioned together as a functional stress-response system rather than standalone ingredients.

Why the Combination Resonates With Today’s Consumer

Ashwagandha, particularly clinically studied extracts such as KSM-66 or Sensoril, has become increasingly associated with hypothalamic-pituitary-adrenal (HPA) axis regulation and healthy cortisol modulation. Multiple human clinical trials have demonstrated improvements in perceived stress scores, serum cortisol levels, sleep quality, and fatigue markers.

L-Theanine operates through a different but complementary pathway. Rather than modulating cortisol directly, it influences alpha brain wave activity and neurotransmitter balance, particularly involving GABA, dopamine, and serotonin signalling. The result is a state often described clinically as “relaxed alertness.”

For educated consumers, this distinction is important:

Ashwagandha addresses stress adaptation over time
L-Theanine addresses the acute neurological experience of stress

Together, they create a layered positioning strategy:

Physiological resilience
Cognitive calmness
Non-sedative emotional support
Focus under pressure

This is particularly relevant as consumers increasingly reject formulations that impair daytime productivity.

The Retail Opportunity Is Behavioural, Not Just Nutritional

What makes this pairing commercially powerful is that it maps directly onto real-world use cases consumers already understand:

High-performance professionals
Students
Shift workers
Menopausal women managing stress and sleep disruption
Consumers tapering stimulant dependence
Individuals experiencing “wired but tired” fatigue

Instead of asking consumers to understand mechanisms of action independently, retailers can merchandise the pairing around moments of need:

“Workday Stress Support”
“Calm Focus”
“Mental Recovery”
“Burnout Support”
“Evening Nervous System Reset”

That framing significantly shortens the educational gap at shelf.

Why Basket Size Increases With This Category

Stress support is becoming less of a single-SKU purchase and more of a protocol-driven category.

Consumers purchasing Ashwagandha and L-Theanine are frequently cross-shopping:

Magnesium glycinate
Phosphatidylserine
Rhodiola
Functional mushrooms
Sleep formulas
Electrolyte support
Adaptogenic beverages

This creates strong secondary merchandising opportunities near:

Cognitive health
Sports recovery
Sleep support
Women’s health
Functional beverages

Retailers who merchandise stress support as a “system” rather than a symptom category are often able to increase both dwell time and average basket value.

Education Still Drives Conversion

Despite the category’s growth, one of the largest retail barriers remains consumer confusion around the difference between calming and sedation.

This is where the Ashwagandha/L-Theanine pairing performs exceptionally well from an educational standpoint. The combination allows staff and signage to communicate a nuanced but commercially important message:
“Calm does not have to mean tired.”

That positioning aligns strongly with current consumer expectations around productivity, emotional regulation, and nervous system wellness.

It also reflects a broader evolution occurring across natural health retail: consumers are increasingly seeking ingredients that improve adaptability rather than simply suppress symptoms.

For retailers, that shift may represent one of the most important merchandising opportunities in the modern supplement category.

Bio-K+ Research Highlights Growing Commercial Interest in the Gut-Brain Axis

0

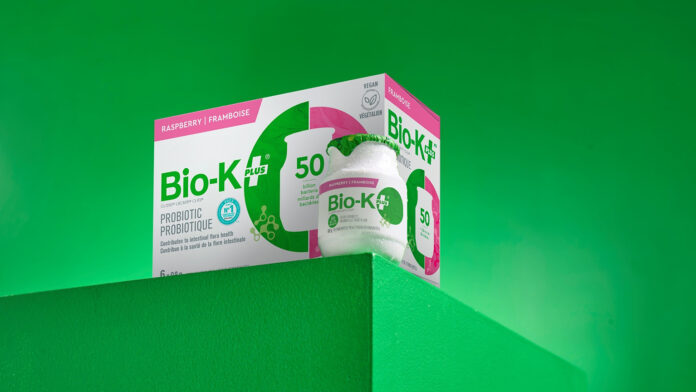
As the gut microbiome category continues to expand across the natural health industry, new clinical findings from Bio-K+® are drawing attention to the growing commercial and scientific potential of microbiome-focused innovation in neurodivergent health support.

The Canadian probiotic brand recently announced promising early-stage findings from an ongoing clinical research initiative examining the relationship between the gut microbiome and Autism Spectrum Disorder (ASD). Conducted in collaboration with the CHU Sainte-Justine Research Centre and supported by the Canadian Institutes of Health Research, the project contributes to the rapidly evolving field of gut-brain axis research.

For retailers, distributors and practitioners, the findings reflect a broader industry shift toward condition-adjacent probiotic positioning supported by clinical evidence rather than general wellness claims alone.

Probiotic Innovation Expands Beyond Digestive Health

The 30-week feasibility study evaluated a raspberry-flavoured vegan Bio-K+ probiotic drink consumed daily by neurodivergent children diagnosed with ASD. Researchers observed a strong safety and tolerability profile, with no adverse events reported during the study period.

Preliminary observations also suggested potential improvements in gastrointestinal symptoms, sleep patterns and behavioural outcomes. Parents participating in the study additionally reported noticeable changes in appetite and overall well-being.

Importantly, some of the observed improvements appeared to diminish following the washout phase, further supporting growing industry interest in continuous microbiome modulation and long-term probiotic supplementation strategies.

The research arrives at a time when retailers are seeing rising consumer awareness surrounding the gut-brain connection, particularly among parents seeking complementary wellness approaches alongside traditional healthcare pathways.

Digestive discomfort remains a major concern within the ASD population, with estimates suggesting a large percentage of neurodivergent children experience recurring gastrointestinal challenges. As a result, microbiome-focused products positioned around digestive balance, mood support and cognitive wellness continue gaining shelf relevance across specialty retail and practitioner channels.

Clinical Validation Becomes a Key Retail Differentiator

One of the most commercially important aspects of the Bio-K+ initiative is its emphasis on scientific validation. The probiotic category has become increasingly crowded, making clinical substantiation a major differentiator for both brands and retailers looking to build long-term consumer trust.

According to Mathieu Millette, the findings contribute to a growing understanding of how the gut microbiome may influence quality of life factors linked to ASD.

While the pilot study was designed to evaluate feasibility rather than establish efficacy, it has already led to the launch of a larger randomized, triple-blind, placebo-controlled trial expected to enrol more than 120 children. Researchers will examine behavioural markers, gastrointestinal symptoms, sleep profiles, microbiome activity, metabolomics and blood chemistry.

For the natural health sector, this signals continued momentum toward evidence-backed formulations capable of supporting premium positioning at retail.

The Gut-Brain Axis Remains One of the Industry’s Fastest-Growing Opportunities

The microbiome category is increasingly moving beyond digestion into adjacent areas including mood, cognition, immunity, metabolic wellness and paediatric health. Research initiatives like the Bio-K+ study reinforce how scientific exploration of the gut-brain axis may influence future product development, merchandising strategies and consumer education.

For retailers, the opportunity lies not only in stocking clinically supported products, but also in understanding the evolving language consumers are bringing into stores. Questions surrounding probiotics, behavioural wellness, microbiome diversity and neurological health are becoming more frequent as public awareness around the gut-brain connection continues to grow.

As clinical research accelerates, brands investing in transparent science, targeted formulations and condition-specific innovation are likely to command increasing attention across the natural health retail landscape.


GLP-1 Success Creates a New Challenge: Keeping the Weight Off

0

As GLP-1 medications continue reshaping the weight-management conversation, a growing issue is emerging behind the dramatic before-and-after stories: long-term weight maintenance. New clinical findings published in the prestigious journal Nature Medicine suggest the gut microbiome may soon play a larger role in helping consumers maintain metabolic progress after initial weight loss.

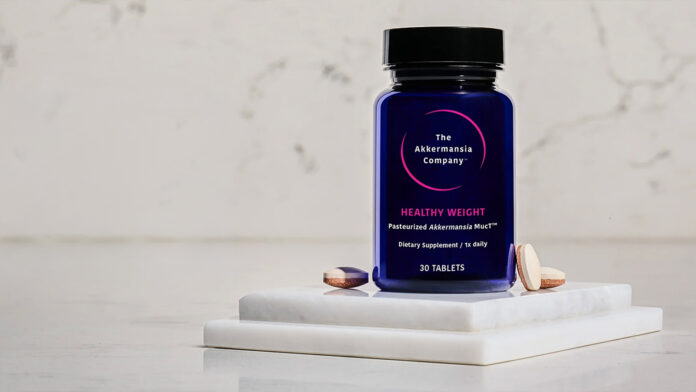
A newly published randomized, placebo-controlled clinical trial involving pasteurized Akkermansia muciniphila MucT® found that participants regained significantly less weight following a structured weight-loss intervention when supplementing daily with the proprietary strain developed by The Akkermansia Company.

The findings arrive at a critical moment for the natural health industry, particularly as retailers and practitioners navigate increasing consumer interest surrounding GLP-1 drugs, metabolic health, gut microbiome science, and sustainable weight-management strategies.

The Next Phase of Weight Management

The clinical trial followed 90 adults with overweight or obesity who first completed an eight-week low-energy diet program designed to trigger at least 8 per cent weight loss. Participants then entered a 24-week maintenance phase during which they either received daily supplementation with pasteurized Akkermansia muciniphila MucT® or a placebo while following a non-calorie-restricted diet.

The difference between the two groups became significant during the maintenance period.

Participants taking the MucT® strain regained an average of only 1.2 kilograms compared to 3.2 kilograms in the placebo group. Researchers also observed that approximately 40 per cent of participants receiving the microbiome strain continued losing weight during the maintenance phase, compared with only about 5 per cent in the placebo group.

Equally important, no significant side effects associated with the supplementation were reported during the study.

For retailers, the study highlights a rapidly evolving category where consumers are increasingly looking beyond short-term weight loss and focusing on long-term metabolic resilience. As GLP-1 medications gain mainstream adoption, many users are now beginning to ask what happens after the medication phase, especially given growing concerns surrounding weight rebound once treatment stops.

Gut Health Moves Into the Metabolic Spotlight

What makes this study particularly noteworthy is that the benefits extended beyond body weight alone.

Researchers observed better preservation of insulin sensitivity among participants taking the MucT® strain, suggesting broader metabolic support following weight reduction. Additional analysis of adipose tissue revealed biological activity associated with healthier energy metabolism and lower inflammatory signalling.

These findings reinforce a broader trend already gaining momentum within the supplement sector: the convergence of microbiome health and metabolic wellness.

Unlike traditional probiotic conversations centred primarily around digestion, emerging microbiome research is increasingly tied to inflammation, insulin regulation, appetite signalling, energy utilization, and obesity management. The category is evolving from digestive support into a far more sophisticated metabolic-health discussion.

That shift could become commercially significant for natural health retailers.

Consumers entering stores today are no longer simply searching for “weight-loss products.” Many are seeking comprehensive metabolic-support solutions that fit into a longer-term wellness strategy. This includes support for satiety, insulin balance, inflammation management, microbiome diversity, and healthy body composition maintenance.

The clinical validation behind specific microbiome strains may also help retailers differentiate evidence-based products from a market increasingly crowded with generalized probiotic positioning.

A Growing Opportunity for the Natural Health Channel

The publication of this study in Nature Medicine also reflects a broader maturation of the microbiome category itself. Scientific credibility is becoming a key competitive advantage as both healthcare professionals and consumers demand stronger substantiation behind wellness claims.

For the natural products industry, this creates an important educational opportunity.

As conversations surrounding GLP-1 therapies continue accelerating, retailers positioned with credible, science-backed complementary solutions may become increasingly valuable to consumers seeking sustainable metabolic support beyond pharmaceuticals alone.

The study also signals a wider industry trend: the future of weight management may become less focused on rapid weight loss and more centred around metabolic maintenance, long-term behavioural support, and microbiome optimization.

In many ways, that shift aligns naturally with the philosophy long championed within the natural health channel — supporting the body’s systems over time rather than chasing short-term outcomes alone.

Canada’s Natural Health Retail Sector: The 2026 Mid-Year Review

0

The first half of 2026 has confirmed what many across Canada’s wellness industry anticipated: the natural health retail landscape is entering a more aggressive, capital-driven era of expansion and transformation.

From major chain growth and wellness-focused quick-service concepts to omnichannel investments and the continued pressure on independents, the sector is evolving rapidly as retailers compete for a more sophisticated and convenience-driven consumer.

Across Ontario especially, the first six months of the year have been defined by strategic store openings, destination-style retail concepts, and increasing overlap between grocery, supplements, prepared foods, and wellness lifestyle retailing.

Healthy Planet Continues Ontario Expansion Push

No retailer has demonstrated more visible physical expansion momentum in the first half of 2026 than Healthy Planet.

The company opened a new 14,000-square-foot Etobicoke location in February, adding another major-format store to its growing Ontario footprint. Additional expansion activity followed with confirmed plans for Burlington and Brampton locations, while the retailer’s highly anticipated Yonge and Eglinton flagship in Toronto continued progressing toward launch during the first half of the year.

The upcoming two-level Toronto flagship reflects how natural health retailing is evolving far beyond the traditional supplement-store format. The location will include a Healthy Planet Kitchen concept focused on prepared foods, grab-and-go offerings, and a broader lifestyle-driven shopping experience.

The strategy mirrors larger global retail trends where consumers increasingly seek integrated wellness ecosystems rather than transactional supplement shopping alone.

For competing retailers, Healthy Planet’s continued expansion also reinforces the growing importance of scale, real-estate positioning, and operational infrastructure within the category.

Heal Wellness Expands the Wellness-QSR Category

The first half of 2026 also highlighted the continued rise of wellness-focused quick-service retail.

Heal Wellness opened a new corporately operated location on Queen Street West in Toronto in April, marking the brand’s eighth corporate store. Parent company Happy Belly Food Group continues aggressively building the concept across Canada and the United States, with more than 169 locations reportedly in development.

The rapid expansion of wellness-QSR concepts signals an important shift within the broader health retail industry. Smoothie bowls, functional beverages, protein-focused menu items, and clean-label convenience foods are increasingly competing directly with traditional cafés and fast-casual chains.

This evolution is especially relevant for natural health retailers because consumer expectations around convenience, immediacy, and experiential wellness continue rising.

The modern wellness consumer increasingly expects wellness products, healthy prepared foods, and lifestyle branding to coexist within the same retail environment.

Omnichannel Retail Became a Larger Priority

The first half of 2026 also reinforced that digital infrastructure is becoming inseparable from physical retail growth.

National Nutrition launched a redesigned e-commerce platform in April featuring upgraded navigation and checkout functionality as part of broader omnichannel investment efforts.

While not tied to a physical store opening, the relaunch reflects one of the year’s most important industry themes: the battle for customer retention is increasingly happening online as much as in-store.

Consumers now move fluidly between social media discovery, online research, subscriptions, same-day fulfilment expectations, and physical retail visits. Retailers investing in frictionless digital experiences are positioning themselves more competitively for long-term loyalty and recurring revenue.

The first half of 2026 showed that successful wellness retail is no longer defined solely by product assortment. Convenience, delivery speed, education, lifestyle positioning, and digital engagement are becoming equally important competitive differentiators.

Independent Retailers Continue Facing Pressure

Despite expansion momentum among larger operators, the first half of the year also highlighted ongoing pressure facing independent wellness retailers.

Toronto-based Strictly Bulk confirmed the closure of its Danforth Avenue location after operating since 1987. The closure represents more than the loss of a single store — it reflects the increasingly difficult environment many independents are navigating.

Rising occupancy costs, labour challenges, tighter margins, and growing consumer expectations around omnichannel convenience continue reshaping the economics of independent retail operations.

At the same time, larger chains with stronger capital access, larger distribution networks, and greater marketing resources continue widening the competitive gap.

While independent openings and closures outside major urban centres often receive limited national attention, the broader trend remains clear: the wellness retail market is becoming more consolidated and operationally demanding.

What the First Half of 2026 Revealed About the Industry

The first six months of 2026 revealed three major themes shaping Canada’s natural health retail channel.

First, scale matters more than ever. Retailers with stronger infrastructure, real-estate strategies, and omnichannel capabilities continue accelerating growth while smaller operators face mounting operational pressures.

Second, the definition of wellness retail continues evolving rapidly. Prepared foods, wellness-QSR concepts, experiential shopping environments, and digitally integrated customer journeys are becoming increasingly central to the category.

Third, consumers are expecting wellness retail to function as a lifestyle experience rather than a traditional transactional shopping model.

As the industry enters the second half of 2026, retailers across the channel are preparing for a more competitive environment where operational sophistication, customer engagement, and experiential differentiation may determine long-term success.

Premium Brands’ $2.1 Billion Quarter Signals a New Era for Protein, Functional Foods and Retail Demand

0

Canadian food giant Premium Brands Holdings has entered 2026 with record-breaking momentum, reinforcing how consumer demand for premium protein, convenience-driven nutrition and functional food innovation continues to reshape grocery and specialty retail across North America.

The company reported first-quarter revenue of $2.05 billion, up 24.6% year-over-year, alongside record adjusted EBITDA of $171.2 million and adjusted earnings per share of $0.83. The results reflect accelerating demand for high-protein foods, healthier convenience products and differentiated specialty offerings — categories that continue to outperform across both retail and foodservice channels.

For retailers, the results offer a broader signal about where consumer spending is heading in 2026: toward premiumized everyday foods that combine convenience, wellness positioning and clean-label appeal.

Protein and Better-for-You Foods Continue to Outperform

One of the most significant takeaways from the quarter was the strength of Premium Brands’ U.S. specialty foods division, which generated $1.5 billion in sales and accounted for 73% of total company revenue. The company reported a combined organic volume growth rate of 9.9% across protein, sandwiches and artisan baked goods despite delays in promotional launches and new product rollouts.

That growth aligns closely with broader North American consumer behaviour. Shoppers continue prioritizing foods perceived as higher in protein, minimally processed and easier to integrate into busy lifestyles. Prepared sandwiches, snackable protein formats, artisan bakery and premium ready-to-eat meals remain some of the fastest-growing categories in retail food.

Premium Brands specifically pointed to consumer demand for products tied to evolving health and lifestyle preferences, including high-protein foods, reduced sugar formulations, organic ingredients and ethically sourced products.

This positioning is increasingly important as retailers look for ways to differentiate from traditional grocery competition and protect margins in an environment where shoppers are becoming more selective with discretionary spending.

The company also highlighted strong growth in seafood and protein opportunities within retail channels, while foodservice demand remained relatively stable.

For independent retailers and specialty health-focused stores, this reinforces a growing market reality: premium protein is no longer a niche category. It has become a core traffic driver across grocery, natural health and convenience retail.

Acquisitions, Operational Scale and Strategic Divestitures Drive Expansion

Premium Brands completed the acquisition of Stampede Culinary Partners during the quarter, further strengthening its position in value-added protein and prepared foods. Management noted that onboarding efforts are progressing well and that several growth and operational synergy initiatives are already underway.

At the same time, the company sold its 74% interest in Shaw Bakers for approximately US$116.9 million as part of a broader strategy to monetize non-core assets. According to President and CEO George Paleologou, the company expects these divestitures to eventually generate more than $1 billion in net proceeds.

The dual strategy of acquisition-led expansion alongside selective divestitures illustrates how major food companies are reshaping portfolios around faster-growth categories tied to wellness, convenience and premiumization.

Premium Brands also continued investing heavily in operational infrastructure, including the start-up of a new 352,000-square-foot sandwich production facility in Tennessee and what management described as the largest single product launch in company history.

These investments suggest growing confidence that demand for prepared premium foods and protein-rich convenience products will continue accelerating through 2026 and beyond.

What It Means for Retailers in Canada

The company maintained its 2026 outlook, forecasting annual revenue between $9.25 billion and $9.55 billion with adjusted EBITDA ranging from $870 million to $910 million.

More importantly, management reaffirmed expectations that the business will exceed its long-term 2027 targets of $10 billion in revenue and $1 billion in adjusted EBITDA — even without further acquisitions.

For retailers, the implications extend well beyond one company’s earnings report.

The categories driving Premium Brands’ growth — high-protein snacks, artisan bakery, functional convenience foods, seafood, ethically positioned products and clean-label offerings — are increasingly shaping shelf allocation, merchandising strategies and consumer loyalty across Canada.

At the same time, the quarter also exposed challenges retailers continue facing. Record-high beef prices and consumer price sensitivity negatively impacted certain categories such as beef jerky, while seafood margins remained pressured due to elevated lobster costs and changing customer purchasing patterns.

This dynamic is pushing retailers to balance premiumization with value perception — a delicate but increasingly important equation in today’s market.

The broader opportunity lies in aligning assortments with evolving consumer priorities. Premium Brands’ results suggest that shoppers are still willing to spend on products that deliver convenience, nutrition, transparency and perceived quality, even amid ongoing economic pressures.

As the boundaries between grocery, wellness and functional nutrition continue to blur, retailers that position themselves around premium everyday foods rather than purely commodity-driven purchasing may be best positioned for sustained growth through the remainder of 2026.

Sandra Sanderson Receives Retail Council of Canada’s Lifetime Achievement Award

0

The Canadian retail industry has recognized one of its most influential marketing leaders. The Retail Council of Canada has awarded Sandra Sanderson, Chief Marketing Officer of Empire Company Limited and Sobeys Inc., with the prestigious Canadian Grand Prix Lifetime Achievement Award, honouring a career that has helped reshape modern retail marketing in Canada.

For retailers, Sanderson’s recognition reflects more than personal achievement. It signals the growing importance of integrated marketing, customer loyalty ecosystems, digital transformation, and purpose-driven retail strategy in today’s competitive marketplace.

Throughout a career spanning consumer packaged goods and retail, Sanderson developed a reputation for understanding the evolving Canadian shopper. Her experience at global brands including Procter & GambleKraft Heinz, and The Coca-Cola Company laid the foundation for a retail leadership journey that later expanded through roles at Canada PostShoppers Drug MartWalmart Canada and other major retail organizations.

Today, Sanderson oversees marketing across one of the country’s largest grocery retail portfolios, including SobeysSafeway CanadaIGA CanadaThrifty FoodsFoodlandFreshCo and Lawtons Drugs. Her leadership has been closely tied to Empire’s transformation strategy during a period when Canadian retailers faced shifting consumer expectations, inflationary pressure, digital disruption, and increased competition from global e-commerce players.

One of Sanderson’s most significant contributions was the modernization of Empire’s marketing infrastructure through the creation of a Marketing Technology & Digital Center of Excellence. This initiative helped strengthen customer personalization, data-driven engagement, and omnichannel retail capabilities — all critical areas for retailers navigating today’s rapidly evolving marketplace.

Her role in transforming the Scene+ loyalty platform further demonstrated the increasing value of ecosystem-based loyalty programs in Canadian retail. With more than 15 million members, Scene+ has become one of the country’s most influential consumer engagement platforms, showing how retailers can leverage rewards ecosystems to drive retention, frequency, and customer lifetime value.

Sanderson also helped position Empire within the expanding retail media landscape through the launch of Empire Media+, reflecting a broader industry trend where retailers are increasingly monetizing first-party shopper data and digital advertising channels.

Beyond commercial performance, Sanderson has consistently emphasized purpose-driven retail leadership. Under her stewardship, Empire launched the Family of Support: Child & Youth Mental Health initiative, strengthening the connection between retail brands and community impact. She also oversaw the company’s “Feed The Dream” Olympic and Paralympic campaigns as Official Grocer of Team Canada, further aligning brand storytelling with national identity and emotional consumer connection.

Her influence extends well beyond corporate leadership. Sanderson currently serves as a board director for Special Olympics Canada and Scene+, while continuing to mentor future industry leaders through academic and professional marketing programs.

For independent retailers and large chains alike, Sanderson’s career illustrates how modern retail success increasingly depends on the intersection of technology, customer experience, loyalty, community engagement, and authentic brand purpose.

As Canadian retail continues to evolve, the leadership principles behind Sandra Sanderson’s success are becoming essential playbooks for the next generation of retail executives.

Sources:
Retail Council of Canada announcement materials; Empire Company Limited corporate information; Sobeys Inc. corporate information.

Extract Labs Expands Functional Wellness Portfolio With High-Potency Organic Mushroom Extract Powders

0

As consumer demand for functional wellness products continues to accelerate, Extract Labs is expanding beyond cannabinoids with the launch of a new line of certified organic Mushroom Extract Powders formulated for potency, purity and transparency.

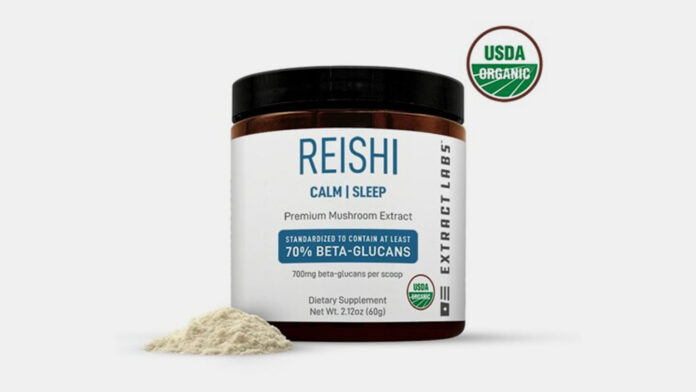
The veteran-owned wellness company has introduced three concentrated mushroom extracts — Lion’s Mane Extract Powder, Reishi Extract Powder and Cordyceps Extract Powder — designed to meet growing consumer expectations for more efficacious adaptogenic and functional mushroom supplements.

The launch reflects a broader shift within the natural health market as consumers increasingly seek clinically relevant formulations rather than commodity-style mushroom powders. Functional mushrooms have become one of the fastest-growing categories in wellness, driven by rising interest in cognitive performance, stress management, immune resilience and natural energy support.

According to the company, many mushroom powders currently available on the market contain roughly 20 per cent beta glucans, the key bioactive compounds associated with many of the wellness-supporting properties of medicinal mushrooms. Extract Labs says its new Mushroom Extract Powders are standardized to contain approximately 70 per cent beta glucans, positioning the products within the premium high-potency segment of the category.

“Our customers are looking for more than trend-driven ingredients. They want products that are thoughtfully formulated and backed by real standards,” said Craig Henderson, founder and CEO of Extract Labs. “Innovation for us means listening closely to our community and creating solutions that genuinely elevate their wellness routines.”

The company’s new product lineup targets several of the category’s most in-demand wellness applications. Lion’s Mane is commonly associated with cognitive support and focus, Reishi has long been used in traditional wellness practices for relaxation and immune support, while Cordyceps is often positioned for natural energy and stamina support.

Each extract is certified organic, packaged in 60-gram jars and retails for US$89.99.

For retailers, the launch highlights the continued premiumization of the mushroom supplement category. Consumers are becoming increasingly educated about extraction methods, active compound concentrations and ingredient sourcing, creating stronger demand for transparent formulations supported by measurable specifications.

The emphasis on beta glucan concentration also aligns with evolving consumer purchasing behaviour in the natural health channel, where shoppers are moving beyond general ingredient recognition toward efficacy-driven comparisons. As a result, brands capable of clearly communicating potency metrics and extraction standards may gain stronger positioning in an increasingly competitive functional mushroom market.

Founded in 2016 by Army veteran Craig Henderson, Extract Labs has evolved from a small garage operation in Arvadainto a 22,000-square-foot cGMP-certified manufacturing facility in Lafayette. The company has built its reputation around clean-label cannabinoid wellness products while steadily expanding into broader plant-based wellness categories.

The company also holds several certifications across its portfolio, including USDA Organic, Leaping Bunny, cruelty-free and cGMP compliance, reinforcing growing consumer demand for transparency and manufacturing accountability within the wellness sector.

Extract Labs’ Mushroom Extract Powders are now available through the company’s online store.

Organic Dairy’s Legal Revolt Against U.S. Milk Pricing: What Canada’s Supply-Managed Industry Can Learn

0

The American organic dairy sector is entering one of the most consequential legal battles in modern agricultural policy. A coalition of organic dairy farmers and processors is challenging the United States Department of Agriculture’s Federal Milk Marketing Order (FMMO) system, arguing that the decades-old pricing structure forces organic producers to subsidize conventional dairy operations while receiving little or no benefit in return.

For Canadian retailers, distributors, and health-focused consumers, the lawsuit represents far more than a regional policy dispute. It highlights a growing international tension within food systems: whether legacy agricultural frameworks are capable of supporting modern premium food categories such as organic, regenerative, and specialty dairy.

The case could reshape how governments worldwide regulate organic agriculture.

A System Built Before Organic Dairy Existed

The FMMO program was originally designed during the 1930s to stabilize milk prices and ensure a reliable supply of conventional dairy products across the United States. At the time, organic dairy did not exist as a commercial category.

Today, however, organic milk has evolved into a major consumer segment. According to the Coalition for Organic Dairy Exemption (CODE), organic dairy now represents approximately 7 per cent of all U.S. fluid milk sales despite accounting for only about 3 per cent of total milk production.

That imbalance is central to the lawsuit.

Organic dairy farmers argue that the FMMO system pools revenues in a manner that redistributes money generated through organic dairy sales into conventional dairy channels. The plaintiffs claim organic producers are effectively subsidizing a supply chain they do not participate in and from which they derive limited economic benefit.

The lawsuit does not seek to dismantle the FMMO program entirely. Instead, it asks for an exemption recognizing that organic milk operates under fundamentally different economics, production standards, supply chains, and regulatory obligations.

Why Organic Dairy Operates Differently

Organic dairy production is structurally more expensive than conventional dairy farming.

Certified organic operations must comply with stringent federal regulations governing feed quality, land management, animal welfare, medication restrictions, and processing standards. Organic milk also requires strict segregation throughout transportation, storage, and manufacturing.

Conventional milk cannot simply be substituted into organic production streams.

That distinction matters because the FMMO system was built on the assumption that all milk entering the pool is interchangeable. Organic producers argue this assumption no longer reflects market reality.

The legal filings also point to rising consumer demand for traceability, sustainability, and premium food sourcing. Organic consumers increasingly view dairy not merely as a commodity, but as a differentiated wellness product tied to environmental stewardship and production ethics.

That positioning places organic dairy closer to functional food categories than traditional commodity agriculture.

Canada’s Dairy System: Different Structure, Similar Questions

Canada’s dairy industry operates under a fundamentally different framework through supply management, which controls production quotas, pricing, and imports to stabilize the domestic market.

Unlike the United States’ FMMO system, Canada’s dairy pricing environment already recognizes differentiated milk classes, including components tied to specialty products and industrial uses.

That distinction may provide Canadian dairy producers with more structural flexibility than their American counterparts.

However, Canada is not immune to the same underlying pressures.

Consumer demand for organic dairy, grass-fed products, A2 milk, regenerative farming, and clean-label nutrition continues to accelerate across Canadian retail shelves. As these categories expand, questions surrounding pricing equity, production incentives, and supply allocation may eventually emerge here as well.

The American lawsuit could therefore become a preview of future policy conversations within Canada’s own dairy landscape.

Retailers Are Watching Consumer Behaviour Shift

For retailers, the story extends well beyond agricultural regulation.

Organic dairy has become a high-value category associated with premium consumers, wellness-oriented households, and younger demographics seeking transparency in food production. These consumers are often willing to pay significantly higher prices for products aligned with environmental values and perceived health benefits.

The legal battle in the United States reveals how rapidly consumer demand can outpace regulatory modernization.

Retailers increasingly face shoppers who no longer see organic as a niche category. Instead, organic dairy is becoming part of a broader lifestyle movement tied to clean eating, sustainability, and preventative wellness.

That trend creates both merchandising opportunities and sourcing challenges.

If policy frameworks fail to support organic production economics, retailers may eventually encounter tighter supply conditions, higher wholesale costs, or reduced category expansion opportunities.

The Bigger Global Question

The most important issue raised by the lawsuit may not be dairy pricing itself.

It is whether agricultural systems originally designed for commodity farming can successfully adapt to premiumized food economies built around differentiation, traceability, and consumer values.

Organic dairy farmers argue that they are operating inside a regulatory structure designed for a completely different era of agriculture. Their claim reflects a broader transformation occurring across the global food industry, where consumers increasingly reward identity-driven production rather than pure volume efficiency.

Canada’s dairy system may currently provide greater insulation from some of these tensions, but the same market forces are clearly emerging here as well.

As organic and specialty dairy continue gaining market share, the pressure to modernize agricultural policy frameworks will likely intensify on both sides of the border.

For the health retail sector, the lawsuit represents an early signal that the future of dairy may depend as much on regulatory evolution as on consumer demand itself.

Sources

Coalition for Organic Dairy Exemption (CODE) statements
United States Department of Agriculture (USDA)
Federal Milk Marketing Order (FMMO) documentation
Organic Trade Association market data
Canadian Dairy Commission information

Yves Relaunch in Canada: A Strategic Reset for Plant-Based Retail

0

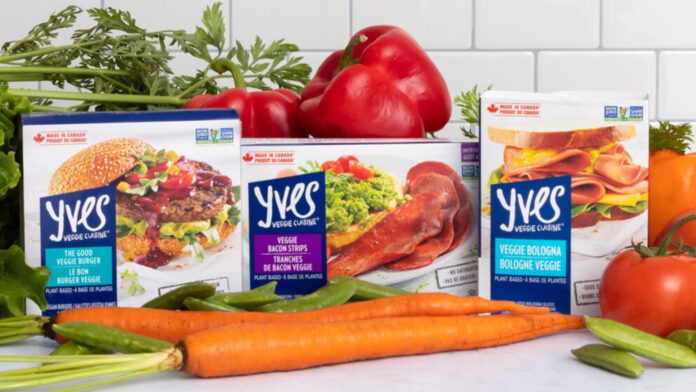
There is a difference between a relaunch and a reset. The return of Yves Veggie Cuisine to the Canadian market, under the stewardship of Maple Leaf Foods, is unmistakably the latter.

For decades, Yves held a defining place in Canada’s early plant-based movement. Long before the category became crowded with global entrants and venture-backed disruptors, it was one of the few brands translating alternative protein into something accessible for everyday consumers. But markets evolve. Expectations sharpen. And familiarity alone is no longer enough to secure shelf velocity.

What is unfolding now is a deliberate, highly disciplined re-entry—one that reflects where plant-based stands today, not where it began.

From First-Mover to Measured Comeback

The plant-based category in Canada has entered a more mature phase. The early years were defined by rapid expansion, innovation cycles, and consumer curiosity. The current moment is more exacting. Shoppers are no longer experimenting—they are evaluating.

Taste must hold. Texture must satisfy. Ingredient lists must justify the claim of wellness. And above all, products must earn repeat purchase.

This is the environment Yves is stepping back into.

The relaunch centres on reformulation, but the implication is broader than improved flavour. It signals a recognition that the modern consumer reads labels as closely as they assess taste. Protein content, sodium levels, and ingredient clarity are no longer secondary attributes—they are decisive factors at the point of purchase.

Repositioning Beyond the Niche

Perhaps the most important shift is not in the product itself, but in who it is for.

Yves is no longer being framed as a brand for vegetarians alone. Its renewed focus is the flexitarian consumer—the individual who is not eliminating meat, but actively reducing it. This is the largest and most commercially relevant segment in plant-based today, and one that aligns naturally with the broader wellness movement.

For retailers, this repositioning changes the conversation at shelf level. The product is no longer an alternative. It is an option—one that sits alongside conventional protein as part of a more balanced lifestyle.

The timing of this relaunch is not incidental. The plant-based sector has experienced a noticeable recalibration over the past two years. Growth has tempered. Assortments have tightened. Consumers have become more selective.

In many stores, the category has shifted from expansion to refinement.

Within this context, the return of a familiar Canadian brand carries weight. Yves does not need to introduce itself. It needs to prove itself again—under a new set of expectations.

That distinction matters.

What It Changes on the Retail Floor

In-store, the opportunity is less about novelty and more about narrative.

A relaunch creates a moment—one that can be leveraged to re-engage consumers who may have drifted away from plant-based altogether. The phrase “back and improved” carries credibility when attached to a name shoppers already recognize.

But conversion will depend on clarity. Today’s consumer is asking more informed questions:

  • How does this compare nutritionally to animal protein?
  • What exactly is in it?
  • How does it fit into daily meals, not just occasional substitutions?

Retail environments that can answer those questions—through staff knowledge, merchandising, and contextual placement—will extract the most value from the relaunch.

For Maple Leaf Foods, the decision to reinvest in Yves is also a signal of intent. Despite broader industry headwinds, the company is not retreating from plant-based. It is refining its approach.

The emphasis has shifted from aggressive expansion to sustainable performance. Fewer products, executed better. Less noise, more consistency. It is a strategy grounded in the belief that the category’s future will be defined not by innovation alone, but by trust.

The Return of Discipline

In many ways, the Yves relaunch reflects a broader maturation of the plant-based sector in Canada. The era of rapid proliferation has given way to something more demanding.

Products must deliver. Brands must evolve. And retailers must curate with greater precision.

Yves is returning to a market that no longer rewards presence—it rewards performance.

That is a more difficult landscape. But it is also a more durable one.

The Trust Collapse: How Low-Quality Products Are Poisoning Amazon Categories

0

A strategic guide for retailers and brands competing in an Amazon marketplace where consumer confidence is at a critical inflection point

If you’ve spent any time browsing Amazon in the past two years, you’ve likely felt it — that creeping uncertainty when you scroll through pages of near-identical products with suspiciously perfect five-star ratings, unpronounceable brand names, and stock photography that could belong to any of a dozen listings. You’re not imagining it. Consumer trust in Amazon’s product categories is eroding, and the data tells a sobering story for everyone competing on the platform.

For retailers and brand managers, this is both a crisis and an opportunity. The brands that understand what is happening — and respond with genuine differentiation rather than race-to-the-bottom tactics — are the ones that will own category authority when the dust settles.

“When Amazon first pioneered customer reviews, a lot of people didn’t understand why Amazon would have potentially negative reviews next to a product they were trying to sell.” — Rebecca Mond, Head of External Relations, Customer Trust & Abuse Prevention, Amazon

The Scale of the Problem: What the Data Actually Shows

The proliferation of low-quality products on Amazon is not anecdotal — it is measurable, documented, and accelerating. A comprehensive study of over 33.5 million Amazon bestseller reviews, analyzed using AI-powered detection tools, found that 43% of Amazon’s bestselling products carry unreliable reviews. In the clothing, shoes, and jewelry category, that figure reaches a staggering 88%. Electronics fared little better, with more than 2.6 million questionable reviews representing 53% of the category’s feedback.

These aren’t abstract numbers. They represent millions of purchasing decisions shaped by manufactured social proof, and they have real consequences for both consumers and the honest brands competing beside the bad actors.

Research from UCLA Anderson Review, drawing on peer-reviewed academic work, makes the market distortion explicit: sellers who purchased fake reviews raised their prices and saw unit sales rise by an average of 27.2%, while honest sellers surrendered market share and were forced to cut prices by an average of 4.4% just to compete. Consumers, meanwhile, are left worse off — paying more for inferior products or distrusting the ratings entirely and making even poorer purchasing decisions as a result.

Bottom line: Fake reviews don’t just harm individual brands. They corrupt the entire category signal, making it harder for every shopper to find what they actually need — and harder for quality sellers to be discovered.

Why Category Trust Collapses — And Why It Matters to You

Amazon’s marketplace hosts over 350 million active products in the U.S. alone. Its algorithm evaluates hundreds of signals simultaneously — relevance, conversion, trust, and behavioral patterns — in approximately 200 to 300 milliseconds per search. The system is designed to surface the products most likely to satisfy a customer. But when review manipulation floods a category with inflated ratings, the algorithm’s inputs become corrupted.

The downstream effects are significant. Amazon’s own internal data indicates that a single negative product experience translates to a $200 to $300 reduction in customer lifetime value. At the category level, when shoppers repeatedly encounter products that disappoint, they stop trusting the category’s star ratings altogether — and that skepticism does not discriminate between legitimate brands and bad actors.

Shoppers who grow suspicious of five-star ratings will become suspicious of your five-star rating, even if you earned every single one. That is the central threat of category trust erosion: the reputational contamination travels sideways.

In categories already identified as high-risk — electronics, supplements, beauty, clothing, and kitchenware — consumer skepticism is measurably higher. A UCLA Anderson Review analysis noted that high ratings alone have become a poor indicator of quality in the current environment, and that shoppers are now applying blanket suspicion to categories they once browsed with confidence.

The Strategic Response: Five Pillars of Genuine Differentiation

In a marketplace where low-quality sellers can temporarily mimic the surface signals of quality brands, the only sustainable path is building differentiation that cannot be faked. Here is how the most resilient brands are doing it.

1. Lead with Product Truth, Not Product Performance

The single characteristic that differentiates products that survive in competitive Amazon categories — according to product research professionals who track these dynamics — is that their improvements originate from genuine user pain points, not cosmetic variation on existing products. This distinction matters enormously.

Mining verified negative reviews in your category is one of the highest-leverage activities available to a brand manager right now. Those reviews are a roadmap to what the market actually needs. A seller who noticed recurring complaints on Reddit about splash-proof water bowls that still made messes went away and designed a genuinely no-spill solution — and reached $35,000 per month in revenue within five months. The solution wasn’t a better listing. It was a better product.

Brands that want to be insulated from category trust collapse need to ask one honest question: if every star rating in our category disappeared tomorrow, would a customer who used our product tell their friend to buy it?

2. Build Brand Architecture That Earns Third-Party Verification

One of the clearest differentiators in a commoditized category is third-party validation that cannot be purchased. This includes quality certifications relevant to your category, clinical testing for supplement and wellness products, professional endorsements in parenting and healthcare products, and sustainability credentials like B Corp or specific material certifications.

Amazon’s own data shows that products in categories like baby and childcare — where the trust factor is treated as non-negotiable — command premium prices and build loyal customer bases precisely because parents treat third-party safety endorsements as a purchasing threshold, not a bonus. The same dynamic is emerging in supplements, beauty, and personal care as consumer health literacy rises.

The practical implication: if you are competing in a category where certifications are obtainable, obtaining and prominently featuring them is not merely a marketing exercise. It is a competitive moat.

3. Invest in Content That Educates, Not Just Converts

Amazon’s A+ Content system gives brand-registered sellers the ability to tell a richer story on their product detail pages. Most sellers use this space for additional lifestyle imagery and generic benefit statements. The brands winning the trust battle use it differently.

High-performing brands are using A+ Content to educate shoppers on what makes a good product in their category, explain their manufacturing process, showcase certifications and testing data, and tell the origin story of the brand and product. This approach does something review manipulation cannot replicate: it creates a framework through which a customer evaluates the entire category using your brand’s standards. Shoppers who understand what to look for will naturally find your product more compelling — and will look back on low-quality competitors with educated skepticism.

Invest in professional photography that serves a specific function in the decision-making process. Include 360-degree product views where relevant. Create short explainer videos that demonstrate genuine product performance. Each piece of rich media adds a layer of credibility that generic listings cannot match.

4. Enforce Pricing Discipline to Protect Perceived Value

One of the most insidious dynamics that low-quality proliferation creates is pressure to lower prices. Unauthorized sellers undercut authorized resellers, triggering a race to the bottom that erodes perceived value even for brands that have done nothing wrong. Implementing and enforcing Minimum Advertised Price policies is a structural defense, not a tactical one.

Research consistently shows that brands with what analysts call ‘established price elasticity trust’ — the ability to hold or raise prices without ranking degradation — are brands that have invested in signaling quality through everything other than price. Competing on price alone in a commoditized category ensures a brand has no floor below which it cannot be undercut. Competing on value creates a ceiling above which price increases become possible.

Products launching in competitive categories in 2025 need to sustain 4.3 or higher star ratings to remain visible in search. Sustaining that rating requires products that genuinely deliver on their promise. But it also requires pricing that signals the product belongs in a quality tier — not just marketing language that says so.

5. Build Brand Equity Beyond the Amazon Listing

The most defensible position on Amazon is not being the best listing on Amazon. It is being a brand that customers look for on Amazon — rather than a category they browse. The difference is enormous. Customers searching for your brand by name, rather than a generic product keyword, are expressing trust that organic category browsing cannot deliver.

Building that kind of brand recognition requires investing in channels outside Amazon: social media presence, influencer and creator partnerships, direct-to-consumer touchpoints, and earned media. The brands leading their categories on Amazon in 2025 are increasingly treating the platform as one channel in a multi-platform brand strategy, not as the totality of their presence.

External traffic that converts on Amazon — which Amazon tracks as validation of genuine market demand — also receives meaningful ranking boosts in the platform’s algorithm, currently estimated at 15 to 20% of ranking contribution. Brands with audiences outside Amazon are rewarded inside it. The brands with no external presence are entirely dependent on a marketplace that is increasingly crowded and increasingly distrusted.

What Amazon Is Doing — And Why Brands Cannot Wait for the Platform to Fix It

Amazon is not a passive observer of the trust crisis. The company invested more than one billion dollars in brand protection efforts in 2024, employing thousands of machine learning scientists, software developers, and investigators dedicated to the problem. It has filed more than 150 lawsuits against fake review services, joined with Google to pursue multi-platform review fraud, and worked with the UK Competition and Markets Authority on binding review integrity agreements.

The FTC enacted new rules in October 2024 barring the purchase and sale of fake consumer reviews, with penalties of up to $52,000 per violation. Amazon’s own detection systems now screen for suspicious review patterns — sudden volume spikes, identical phrasing, unverified purchase sources — and the platform claims that over 99% of viewed product pages display only authentic reviews.

But academic research on the dynamics of review markets is clear: eliminating fake reviews alone does not restore consumer trust. Shoppers who have been burned by manipulated ratings develop generalized skepticism that persists even after the manipulation is removed. The distrust becomes structural. That means brands cannot wait for Amazon to clean up the ecosystem and expect that trust will automatically accrue to them.

Brands that rely on real product performance and customer satisfaction no longer need to compete with operators buying their way to the top of rankings — but only if they have built the genuine signals of quality that distinguish them from those who were.

The Minimum Viable Quality Standard Has Shifted

Five years ago, an Amazon seller could launch a product in a moderately competitive category with a 3.8-star average and expect to find a viable market position. That era is over. Products launching in competitive categories today need to sustain 4.3 or higher ratings to remain visible — and sustaining that requires products that genuinely address real user needs, not just aesthetically differentiated versions of what already exists.

This is not simply an algorithmic threshold. It reflects a consumer population that has become more sophisticated about evaluating product quality signals. They read the most critical reviews first. They look for patterns across multiple reviews before trusting the aggregate. They are, as the UCLA Anderson research showed, increasingly suspicious of suspiciously high ratings — particularly unverified five-star reviews, which spiked to 250,000 per month on Amazon by March 2023 before enforcement actions began.

For brands, this means that investing in genuinely superior products is no longer optional. It is the table stakes for remaining visible in any category where trust has been eroded.

A Checklist for Brands Ready to Differentiate

Use these questions to audit your current Amazon position and identify where trust-building investment is most urgent:

  • Does your product solve a documented, specific customer pain point that you can articulate in one sentence?
  • Do you have at least one form of third-party verification — certification, clinical testing, professional endorsement — that is prominently featured in your listing?
  • Is your A+ Content telling an educational story about your category, not just your product features?
  • Do you have a MAP policy in place and are you actively enforcing it against unauthorized resellers?
  • Are you generating external traffic to your Amazon listings from social channels, influencer partnerships, or owned audiences?
  • Can you articulate a clear answer to why a customer should choose your product at your price, without referencing your star rating?
  • Are you monitoring category review trends to identify emerging quality expectations before they become baseline requirements?

The Strategic Opportunity Inside the Crisis

Category trust erosion is a genuine problem. But it is also, for brands willing to invest in differentiation, one of the most significant commercial opportunities in e-commerce right now. When consumers cannot trust the aggregate signals of a category, they increasingly look for anchors — brands that feel identifiable, accountable, and consistent. The brands that build those qualities deliberately, while competitors race toward the bottom, inherit the customer loyalty that category trust would have distributed more broadly.

Amazon has made plain that its future is as a platform that rewards quality sellers and penalizes bad actors. Its ranking architecture increasingly reflects that intent: external traffic that signals genuine demand, review volume from verified purchasers, conversion rates that reflect real customer satisfaction, and listings rich enough to educate and convert a skeptical shopper. Every one of these signals favors brands that have done the genuine work.

The low-quality proliferation that is eroding category trust is temporary. The consumer habit of expecting more — more transparency, more accountability, more authentic evidence of quality — is not. The brands that build to meet that expectation today will own the categories that emerge on the other side of the crisis.

The question is not whether differentiation is worth the investment. The question is whether your brand can afford to be mistaken for the products that are making your customers distrust your entire category.